EU replaces the paper VAT exemption certificate for diplomats and international bodies with an electronic one
- Jurisdiction
- European Union
- Tax
- VAT
- Change type
- Invoice rules
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 28 February 2025
- Instrument
- EU-DIRECTIVE-2025-425
- Authority
- Official Journal of the European Union (EUR-Lex)
- Verified
- Fetched from official source · high confidence
Diplomatic and consular missions, international organisations, NATO forces and other Article 151 bodies in the EU, and the suppliers who make exempt sales to them.
Diplomatic and international-organisation procurement teams should monitor national transposition timelines ahead of the 2031 deadline.
Council Directive (EU) 2025/425 of 18 February 2025 amending Directive 2006/112/EC introduces a mandatory electronic VAT exemption certificate for supplies to diplomatic missions, international organisations and NATO bodies under Article 151. Member States must use an electronic certificate containing the eligible body's identification, the competent authority's details, an intended-use declaration, goods/services descriptions and values, and supplier information. Member States have until 30 June 2031 to transpose; a transitional option to continue using the existing paper certificate runs until 30 June 2032.
What changed in detail
Council Directive (EU) 2025/425 of 18 February 2025, published in the Official Journal (OJ L, 2025/425) on 28 February 2025, amends the VAT Directive (2006/112/EC) by inserting new Articles 151a and 151b. It entered into force twenty days after publication and sets no separate application date: Member States must bring their national rules into force by 30 June 2031 (Article 2).
- Electronic certificate. Member States must use an electronic certificate to confirm that a transaction qualifies for an exemption under Article 151(1), first subparagraph. The eligible body or individual issues it and signs it electronically together with the host Member State (Article 151a(1)). Where the exemption works by refund and VAT is due in the host state, the electronic certificate is optional (151a(2)).
- Data set. At least: the eligible body’s identification; the certifying authority; a declaration on intended use and the conditions; the description, quantity and value of the goods or services; the host state’s certification; and the supplier’s name, address, Member State and VAT, excise or tax number (151a(3)).
- Official use. Member States may waive the host state’s signature for goods or services intended for official use (151a(5)).
- Transition. For transactions until 30 June 2032, Member States may keep using the paper certificate in Annex II to Implementing Regulation (EU) No 282/2011, or their own systems where VAT is due in the host state (151a(6)).
- The Commission sets the technical format by implementing acts (151a(7)).
- Liability. Where the conditions for the exemption are not met or the goods or services are not used as intended, the eligible body that issued and signed the certificate pays the VAT (Article 151b).
What it means
Nothing changes yet for suppliers: the directive is enacted, but Member States have until mid-2031 to transpose it and may keep the paper form until mid-2032. Until the Commission’s implementing acts fix the electronic format and IT system, there is nothing to build against. Suppliers that regularly sell VAT-free to embassies or international organisations should expect the paper certificate on file to be replaced by an electronically signed record they can retrieve, and should watch for national transposition in the Member States where they make such sales.
Proof
By way of derogation from paragraphs 1 and 2 of this Article, Member States may opt to use for any transaction made until 30 June 2032: (a) the paper certificate set out in Annex II to Council Implementing Regulation (EU) No 282/2011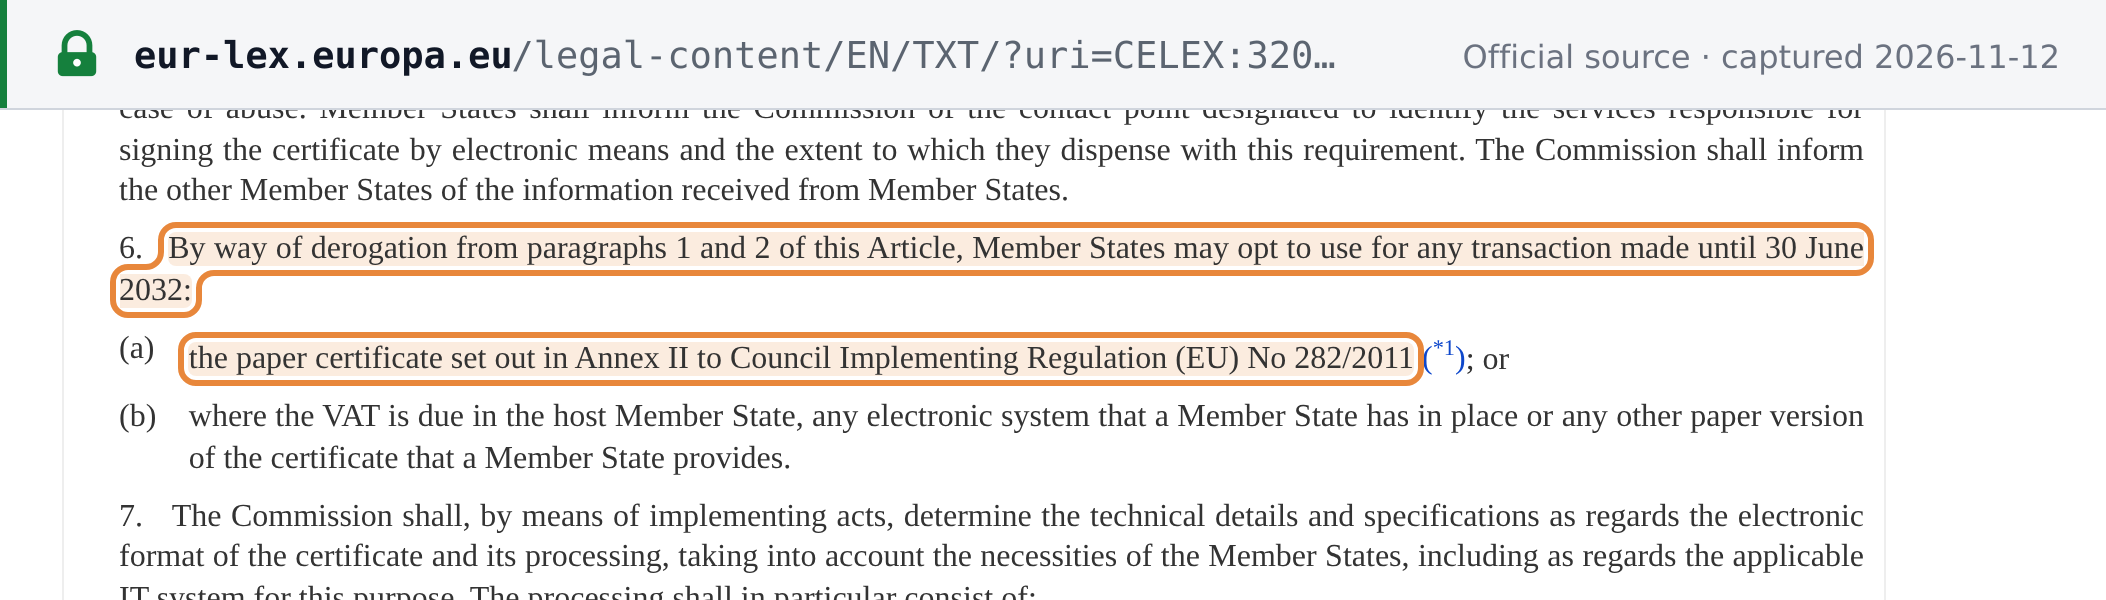 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Council Directive (EU) 2025/425 of 18 February 2025 · OJ L, 2025/425, 28.2.2025 · publications.europa.eu
Member States shall bring into force the laws, regulations and administrative provisions necessary to comply with this Directive by 30 June 2031.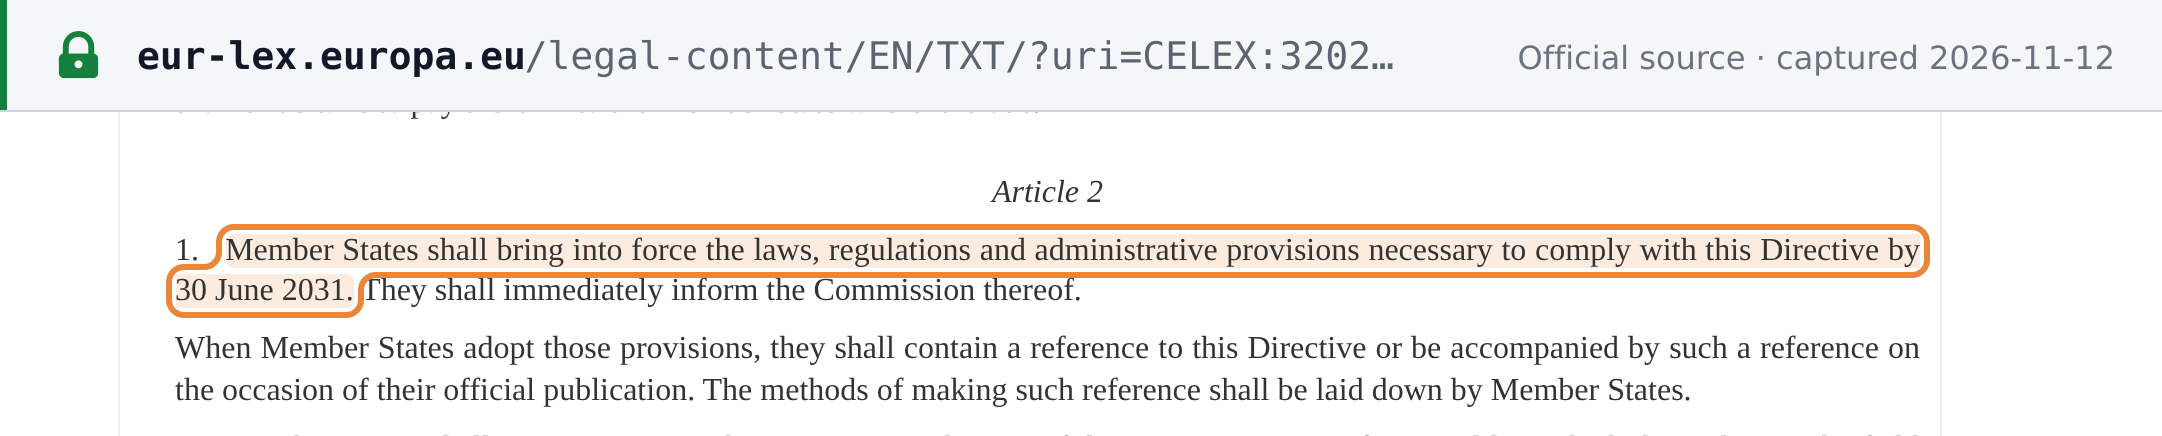 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Council Directive (EU) 2025/425 of 18 February 2025 · OJ L, 2025/425, 28.2.2025 · publications.europa.eu