France taxes renovation works that include a fossil-fuel boiler at the 20% standard VAT rate from 1 March 2025
This page records one dated change. For the rules in France as they stand today, see the France guide →
- Jurisdiction
- France
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 15 February 2025
- Effective
- 1 March 2025
- Instrument
- FR-LOI-Loi-n-2025-127
- Authority
- Journal officiel de la République française (Légifrance)
- Verified
- Fetched from official source · high confidence
Heating installers and renovation contractors in France supplying or installing gas, oil or other boilers able to burn fossil fuels in dwellings, and their customers.
No action required — the 20% standard rate for fossil-fuel boiler installation has applied since 1 March 2025. Maintenance and repair of existing boilers remain eligible for reduced rates.
Article 32 of Loi n° 2025-127 du 14 février 2025 (LF 2025), I 4° and 5°, excluded from the 5.5% rate (new CGI art. 278-0 bis A III bis) and from the 10% rate (art. 279-0 bis 2 bis c) any renovation work that includes the supply or installation of a boiler able to use fossil fuels, which is taxed at the 20% standard rate from 1 March 2025. Work covered by a dated quote accepted by both parties with a deposit cashed before 1 March 2025 keeps the reduced rate.
What changed in detail
Article 32 of Loi n° 2025-127 du 14 février 2025 de finances pour 2025, published in JORF n°0039 of 15 February 2025, removes the reduced VAT rates from works that include a fossil-fuel boiler.
- I 4° inserts III bis in Article 278-0 bis A of the Code général des impôts (CGI): energy-renovation services that include the supply or installation of a boiler able to use fossil fuels are taxed at the standard rate of Article 278, not 5.5%.
- I 5° rewrites 2 bis of Article 279-0 bis, which lists works excluded from the 10% rate on dwellings: alongside cleaning and green-space works, it adds c, works that include the supply or installation of such a boiler.
Under II, the changes apply from 1 March 2025. They do not apply to operations covered by a dated quote accepted by both parties with a deposit cashed before 1 March 2025.
DGFiP’s commentary BOI-TVA-LIQ-30-20-95 of 22 October 2025 links the measure to the EU Energy Performance of Buildings Directive of 24 April 2024, which bars financial incentives for stand-alone fossil-fuel boilers from 1 January 2025. It applies the exclusion to gas and oil boilers of every type, including high-performance and micro-cogeneration models, even when used as back-up, and accepts a cheque handed over before 1 March 2025 as a cashed deposit.
The same article also cut the VAT franchise thresholds; that rule is recorded separately.
What it means
This is in force. The test is the appliance: if the job supplies or installs a boiler that can burn a fossil fuel, the whole service is at 20%, even when the rest of the job is insulation or controls. Hybrid systems with a gas back-up are caught. DGFiP’s finalised doctrine of 9 September 2026 confirms the position (energy-renovation-reduced-rate-2026).
Article 32 also cut the franchise en base thresholds (franchise-tva-lf2025-art32); that part was reversed retroactively by Loi n° 2025-1044, but the boiler rule was not touched and stands.
Proof
« III bis.-Par dérogation au I du présent article, le taux prévu à l'article 278 s'applique aux prestations de rénovation énergétique comprenant la fourniture ou l'installation d'une chaudière susceptible d'utiliser des combustibles fossiles. »“III bis. By way of derogation from I of this article, the rate provided for in Article 278 [the standard rate] applies to energy-renovation services that include the supply or installation of a boiler able to use fossil fuels.”
Archived from the official distribution · JORFARTI000051168565 (article 32) · JORFTEXT000051168007 · NOR ECOX2423405L · JORF n°0039 du 15 février 2025 · echanges.dila.gouv.fr
l’article 32 de la loi de finances pour 2025 exclut l’application des taux réduits de 5,5 % et 10 % de la TVA aux travaux comprenant la fourniture ou l’installation d’une chaudière utilisant des énergies fossilesArticle 32 of the 2025 finance law excludes the 5.5% and 10% reduced VAT rates for works that include the supply or installation of a boiler using fossil fuels
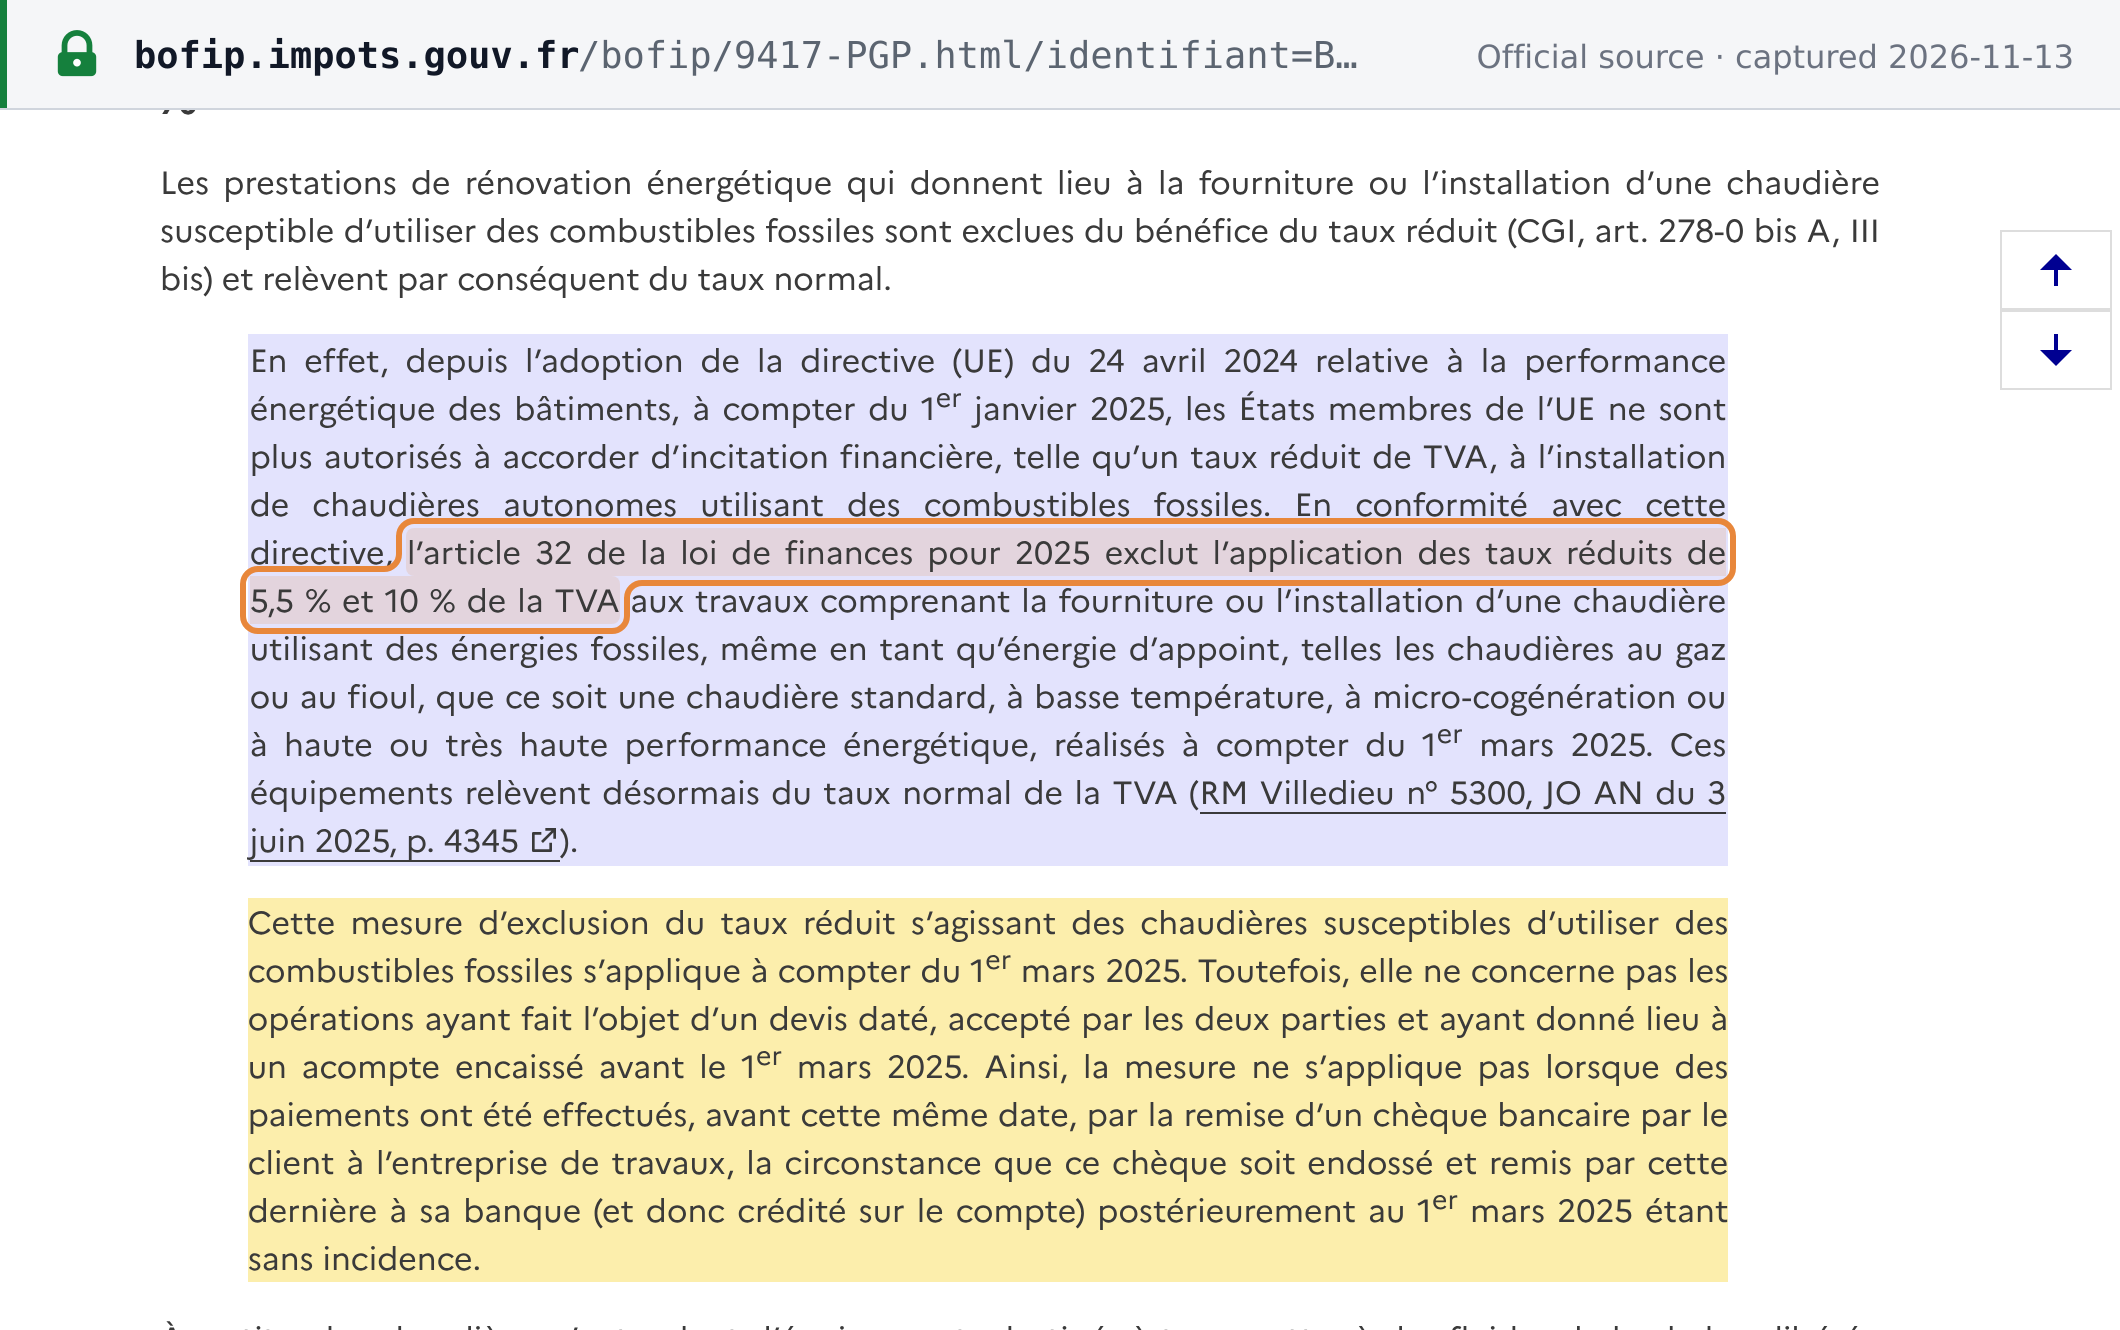 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · BOI-TVA-LIQ-30-20-95-20251022 (BOFiP-Impôts, 22 octobre 2025) · bofip.impots.gouv.fr