France applies the 5.5% VAT rate to residential solar panels up to 9 kWc from 1 October 2025
This page records one dated change. For the rules in France as they stand today, see the France guide →
- Jurisdiction
- France
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 15 February 2025
- Effective
- 1 October 2025
- Instrument
- FR-LOI-Loi-n-2025-127
- Authority
- Direction générale des Finances publiques (DGFiP) — BOFiP
- Verified
- Fetched from official source · high confidence
Installers and suppliers of solar photovoltaic equipment of 9 kWc or less fitted to dwellings in France, and the households buying them.
No action required — the 5.5% rate for qualifying photovoltaic installations has applied since 1 October 2025. Installers should verify that modules meet the carbon footprint and lead/cadmium content criteria in the Arrêté of 8 September 2025. Note: LF 2026 art. 94 (fr-photovoltaic-installer-cert-lf2026-2026) adds a further installer-certification condition from 21 February 2026.
Article 42 of Loi n° 2025-127 du 14 février 2025 (LF 2025) created a 5.5% rate (CGI art. 278-0 bis P) for the supply and installation in dwellings of solar photovoltaic equipment of 9 kWc or less meeting criteria set by order, from 1 October 2025. The Arrêté du 8 septembre 2025 (JORF 9 September 2025) sets those criteria (module carbon footprint, silver, lead and cadmium content, and an energy-management system). By administrative tolerance, work quoted and secured by a deposit or financing offer before 1 January 2026 may still follow the former 10% doctrine.
What changed in detail
Article 42 of Loi n° 2025-127 du 14 février 2025 de finances pour 2025, published in JORF n°0039 of 15 February 2025, adds P to Article 278-0 bis of the Code général des impôts (CGI). The supply and installation, in dwellings, of solar photovoltaic equipment of 9 kilowatts-peak or less takes the 5.5% rate, where its design and characteristics meet criteria set by joint arrêté of the economy and energy ministers. Under II, this applies from 1 October 2025.
The Arrêté du 8 septembre 2025 (JORF n°0209 of 9 September 2025) inserts Article 30-0 E in annex IV, in force on 1 October 2025. The equipment must meet all of these:
- module carbon footprint below 530 kgCO2eq/kWc;
- silver in the cells below 14 mg/W;
- lead below 0.1% and cadmium below 0.01% of the modules;
- an energy-management system that collects production and consumption data in real time and steers consumption to maximise self-use.
DGFiP’s commentary BOI-TVA-LIQ-30-20-97, finalised on 10 June 2026, applies the 9 kWc limit per operation, so panels added to an existing installation can qualify even if the total then exceeds 9 kWc. It withdrew the earlier doctrine that allowed 10% on some installations as renovation works, but lets jobs with a dated, accepted quote and a deposit or financing offer before 1 January 2026 keep that treatment.
What it means
The rate is in force, with an added condition. Article 94 of the 2026 finance law requires installation, fitting and maintenance to be done by a holder of a valid certification or qualification matching the installation, under technical requirements to be set by arrêté (photovoltaic-installer-cert-lf2026-2026). Installers invoicing at 5.5% need product evidence for each of the arrêté’s criteria and should expect qualification to be checked. Operations above 9 kWc, or panels without the energy-management system, follow the general rules.
Proof
La taxe sur la valeur ajoutée (TVA) est perçue au taux réduit de 5,5 % sur la livraison et l’installation, dans les logements, d’équipements de production d’électricité utilisant l’énergie radiative du soleil d’une puissance inférieure ou égale à 9 kilowatts-crête (kWc)VAT is levied at the reduced rate of 5.5% on the supply and installation, in dwellings, of electricity-generating equipment using solar radiation with a power of 9 kilowatts-peak (kWc) or less
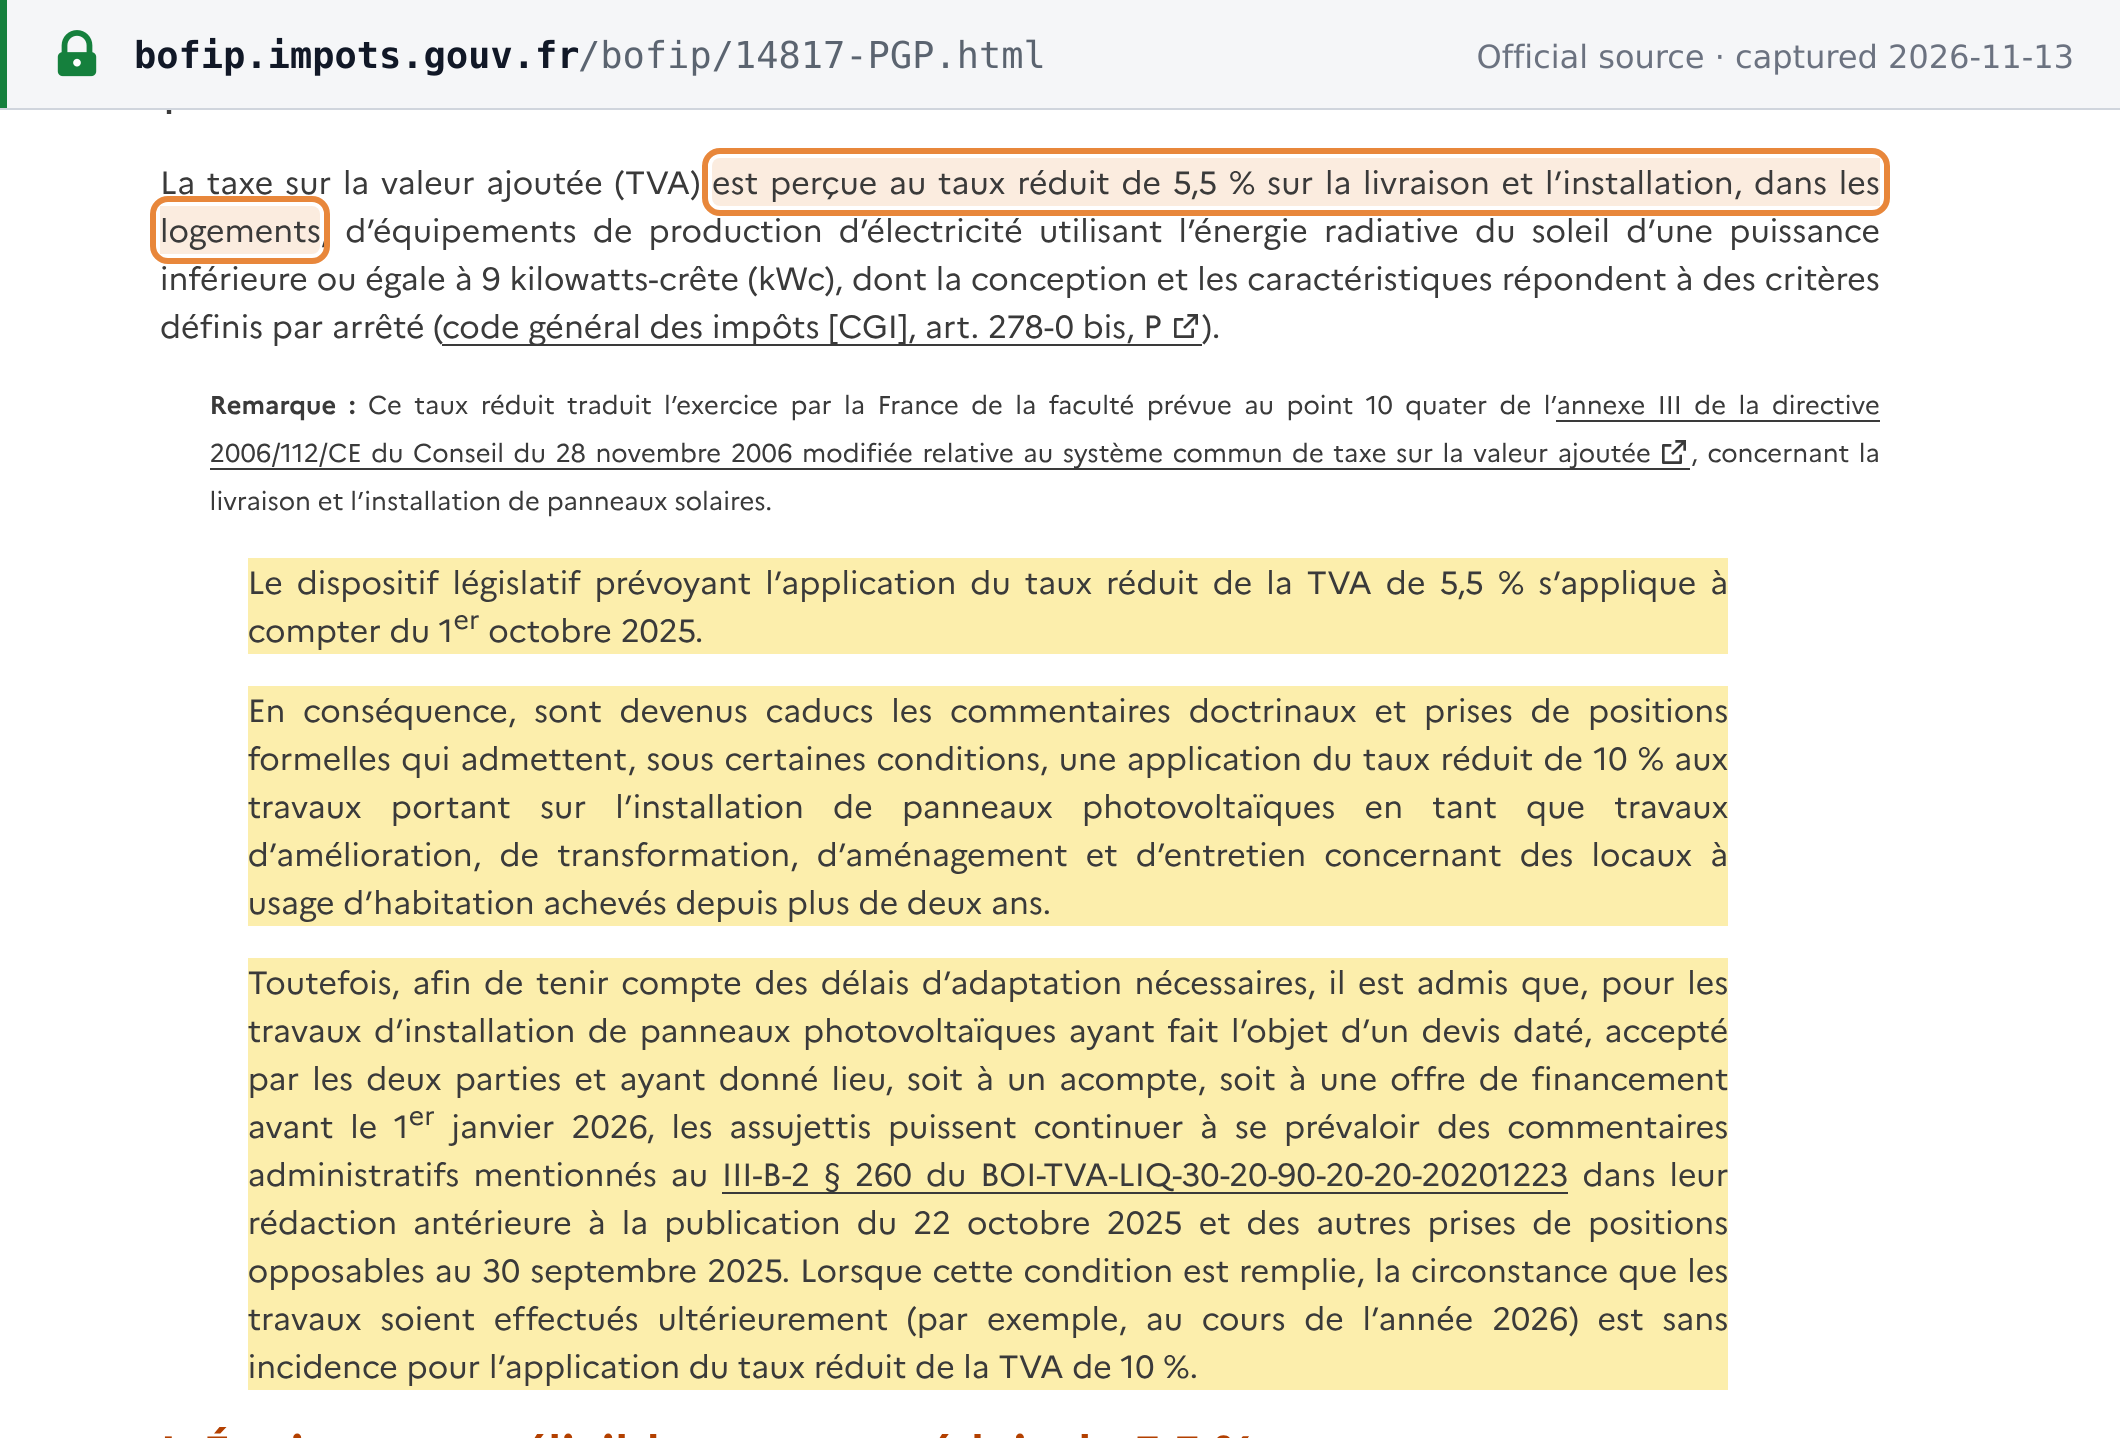 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · BOI-TVA-LIQ-30-20-97-20260610 (BOFiP-Impôts, version du 10 juin 2026) · bofip.impots.gouv.fr
II.-Le I entre en vigueur le 1er octobre 2025.II. I enters into force on 1 October 2025.
Archived from the official distribution · JORFARTI000051168611 (article 42) · JORFTEXT000051168007 · NOR ECOX2423405L · JORF n°0039 du 15 février 2025 · echanges.dila.gouv.fr
« a) Le bilan carbone des modules est inférieur à 530 kgCO 2 eq/ kWc ;“a) The carbon footprint of the modules is below 530 kgCO2eq/kWc;”
Archived from the official distribution · JORFARTI000052212425 (article 1, new annexe IV art. 30-0 E) · JORFTEXT000052212417 · NOR ECOR2524069A · JORF n°0209 du 9 septembre 2025 · echanges.dila.gouv.fr