France replaces the list of energy-renovation works eligible for the 5.5% VAT rate from 1 January 2025
This page records one dated change. For the rules in France as they stand today, see the France guide →
- Jurisdiction
- France
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 24 December 2024
- Effective
- 1 January 2025
- Instrument
- FR-ARRETE-Arr-t-du-4-d-cembre-2024
- Authority
- Journal officiel de la République française (Légifrance)
- Verified
- Fetched from official source · high confidence
Building and renovation contractors invoicing energy-renovation works on dwellings completed more than two years ago in France, and their customers.
No action required — the updated list of energy-renovation works eligible for the 5.5% rate has applied since 1 January 2025. Contractors should ensure works they invoice at 5.5% meet the revised definitions in CGI annexe IV art. 30-0 D.
The Arrêté du 4 décembre 2024 (JORF 24 December 2024), made under CGI art. 278-0 bis A II as rewritten by LF 2023 art. 65, replaced the list of energy-renovation works eligible for the 5.5% rate (CGI annexe IV art. 30-0 D to 30-0 D nonies) from 1 January 2025. The new list covers insulation, renewable heating and hot-water equipment (heat pumps other than air-to-air), ventilation systems, lagging, heating controls, heat-cost meters, ceiling fans and maintenance of very-high-performance boilers. Installing new boilers no longer qualifies; connection to a heat or cooling network qualifies only where the network is mainly supplied by renewable or recovered energy or by cogeneration. Works covered by a dated quote accepted with a deposit cashed before 1 January 2025 keep the former list.
What changed in detail
The Arrêté du 4 décembre 2024, published in JORF n°0304 of 24 December 2024, sets the nature and characteristics of the energy-renovation works that qualify for the 5.5% VAT rate under Article 278-0 bis A of the Code général des impôts (CGI). That article, rewritten by Article 65 of the 2023 finance law, leaves the list to an arrêté. Article 1 replaces Articles 30-0 D to 30-0 D nonies of annex IV.
The new list covers:
- insulation of opaque walls, glazing, entrance doors and insulating shutters, and mobile solar protection;
- renewable heating and hot-water equipment, including heat pumps other than air-to-air, and equipment connecting to a heat or cooling network mainly supplied by renewable or recovered energy or by cogeneration;
- double-flow and humidity-controlled ventilation;
- lagging of heating and hot-water systems, heating controls and heat-cost metering;
- ceiling fans;
- maintenance and repair of very-high-performance boilers.
Compared with the former list, the installation of new condensing or micro-cogeneration boilers no longer qualifies.
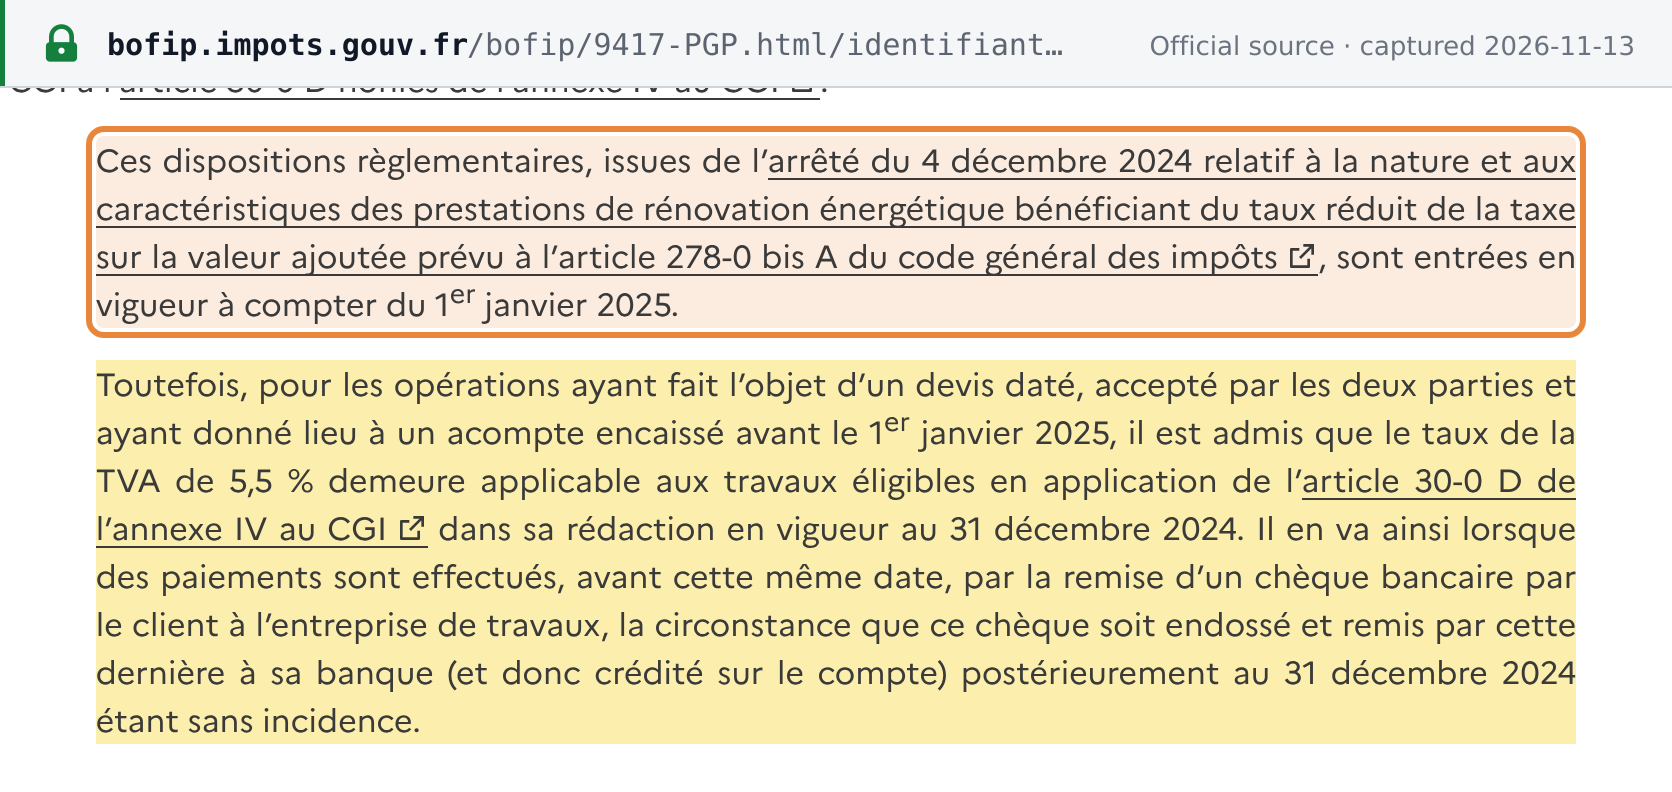
Article 2 brings the arrêté into force on 1 January 2025. Works covered by a dated quote accepted by both parties with a deposit cashed before that date keep the 5.5% rate under the former list. DGFiP’s commentary BOI-TVA-LIQ-30-20-95 of 22 October 2025 confirms the date and adds that a cheque handed over before then counts even if cashed later.
What it means
The list is in force, but it has moved since. Article 32 of the 2025 finance law put any work that includes a fossil-fuel boiler at the standard rate from 1 March 2025 (fossil-boiler-rate-lf2025-2025). Article 92 of the 2026 finance law and the Arrêté du 13 juillet 2026 added qualifying reversible air-to-air heat pumps to the list from 18 July 2026 (pac-rate-lf2026-2026), and an Arrêté du 14 août 2026 corrected that addition. DGFiP’s finalised doctrine of 9 September 2026 sets out the current position (energy-renovation-reduced-rate-2026). Contractors should check each job against the list in force on the date of the quote.
Proof
Toutefois, pour les opérations ayant fait l'objet d'un devis daté, accepté par les deux parties et ayant donné lieu à un acompte encaissé avant le 1er janvier 2025, le taux de taxe sur la valeur ajoutée de 5,5 % demeure applicable aux travaux éligibles en application de l'article 30-0 D de l'annexe IV au code général des impôts dans sa rédaction en vigueur au 31 décembre 2024.However, for operations covered by a dated quote accepted by both parties with a deposit cashed before 1 January 2025, the 5.5% VAT rate continues to apply to works eligible under Article 30-0 D of annex IV to the Code général des impôts as in force on 31 December 2024.
Archived from the official distribution · JORFARTI000050823123 (article 2) · JORFTEXT000050823106 · NOR BCPE2431738A · JORF n°0304 du 24 décembre 2024 · echanges.dila.gouv.fr
sont entrées en vigueur à compter du 1er janvier 2025entered into force from 1 January 2025
 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · BOI-TVA-LIQ-30-20-95-20251022 (BOFiP-Impôts, 22 octobre 2025) · bofip.impots.gouv.fr