Italy opens its VAT franchise to small businesses from other EU countries from 1 January 2025
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- FYI
- Announced
- 30 November 2024
- Effective
- 1 January 2025
- Instrument
- IT-DECRETO-LEGISLATIVO-180-2024
- Authority
- Gazzetta Ufficiale della Repubblica Italiana
- Verified
- Fetched from official source · high confidence
Natural persons established in another EU Member State with EU turnover up to EUR 100,000 and Italian turnover up to EUR 85,000; Italian forfettari selling elsewhere in the EU.
No action — monitoring only.
Legislative Decree 13 November 2024, n. 180 (GU n. 281, 30 November 2024) implemented EU Directive 2020/285 (SME VAT franchise scheme) and Directive 2022/542. It inserts a new Title V-ter (arts. 70-terdecies to 70-duovicies) into the Italian VAT Decree (DPR 633/1972) establishing a cross-border franchise regime (regime transfrontaliero di franchigia). Natural persons established in another EU Member State may apply the VAT franchise in Italy if their Union annual turnover did not exceed EUR 100,000 and their Italian turnover did not exceed EUR 85,000 (Italy's forfettario threshold) in the previous calendar year, after notifying their Member State of establishment and obtaining an EX identification number. Applies from 1 January 2025.
What changed in detail
Legislative Decree 13 November 2024, n. 180, published in the Gazzetta Ufficiale n. 281 of 30 November 2024, transposes Council Directive (EU) 2020/285 on the special scheme for small enterprises, together with Directive (EU) 2022/542.
Article 1 amends the forfettario rules in article 1 of L. 190/2014. Comma 57, letter b) now provides that, for VAT purposes, persons established in another EU Member State apply the franchise scheme as set out in Title V-ter of DPR 633/1972. Article 3 inserts that new Title V-ter, articles 70-terdecies to 70-duovicies, into the VAT Decree. It creates a cross-border franchise regime (regime transfrontaliero di franchigia).
Under article 70-quaterdecies, a natural person established in another Member State may apply the franchise in Italy where, in the previous calendar year, their total turnover in the Union did not exceed EUR 100,000 and their turnover in Italy did not exceed EUR 85,000, the forfettario threshold. They must first notify their Member State of establishment and obtain an identification number with the suffix “EX”. Article 5 applies the new rules from 1 January 2025.
What it means
Since 1 January 2025, a small sole trader from another EU country can supply goods or services in Italy without charging Italian VAT and without full Italian VAT registration, provided both turnover caps are respected and the EX number has been obtained. Italian buyers will see invoices without Italian VAT from such suppliers. From 1 April 2025 those invoices can carry the new FatturaPA regime code RF20 (record).
The scheme is still in force. The DPR 633/1972 articles of Title V-ter, including article 70-quaterdecies, are abrogated from 1 January 2027 and carried into the VAT Testo unico, D.Lgs. 10/2026 (record).
Proof
i soggetti stabiliti in un altro Stato membro dell'Unione europea applicano il regime di franchigia secondo quanto previsto dal titolo V-ter del decreto del Presidente della Repubblica 26 ottobre 1972, n. 633persons established in another Member State of the European Union apply the franchise scheme as provided by Title V-ter of Presidential Decree 26 October 1972, n. 633
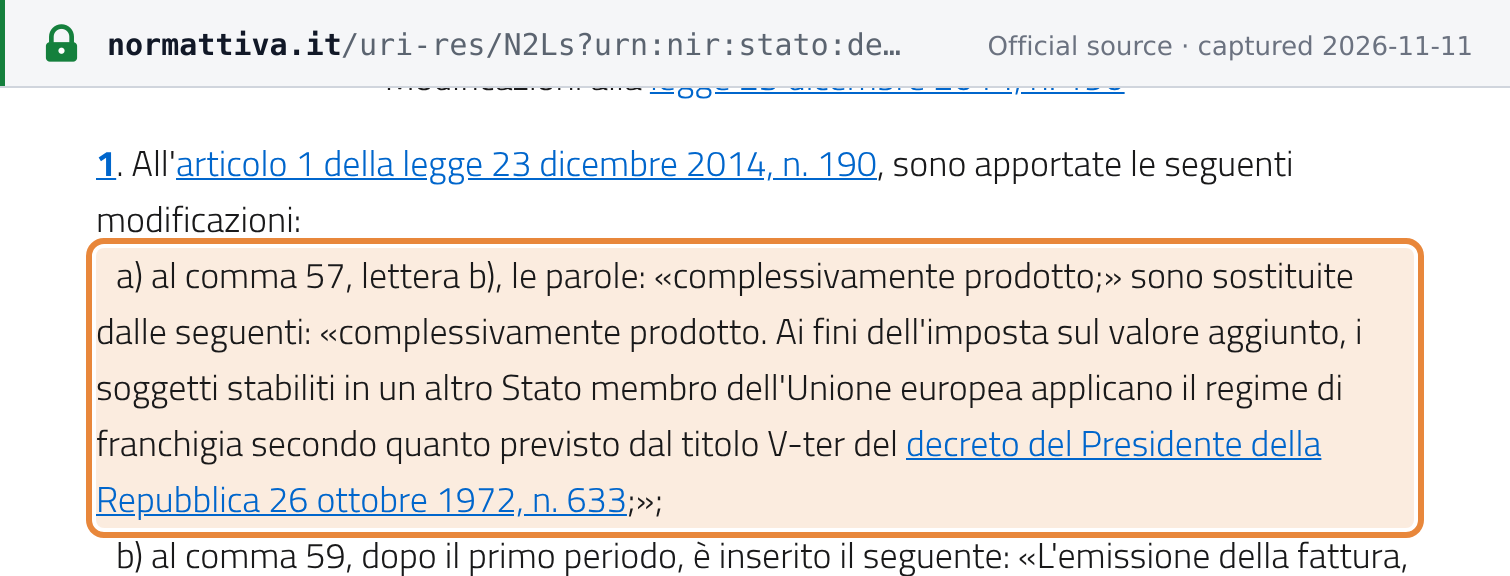 Source snapshot of the official page. Open full size ↗