Italy raises the minimum periodic VAT payment from EUR 25.82 to EUR 100 from 2024
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 12 January 2024
- Effective
- 1 January 2024
- Instrument
- IT-DECRETO-LEGISLATIVO-1-2024
- Authority
- Gazzetta Ufficiale della Repubblica Italiana
- Verified
- Fetched from official source · high confidence
Monthly and quarterly VAT payers in Italy whose periodic VAT due does not exceed EUR 100.
No action — monitoring only.
Legislative Decree 8 January 2024, n. 1 (D.Lgs. 1/2024, GU n. 9 of 12 January 2024), Art. 9, raised the minimum threshold for periodic VAT payments from EUR 25.82 (the euro equivalent of lire 50,000) to EUR 100, applying from periodic settlements for tax year 2024. When the amount due is below EUR 100, payment is deferred to the following month's settlement, but no later than 16 December of the same year. The same article made a parallel increase for minimum withholding payments.
What changed in detail
Legislative Decree 8 January 2024, n. 1, on simplifying tax compliance, was published in the Gazzetta Ufficiale n. 9 of 12 January 2024. Its Article 9 raises the threshold below which a periodic VAT payment can be deferred.
Comma 1 amends article 1, comma 4, of DPR 100/1998, which governs monthly payers. The threshold “lire cinquantamila” (EUR 25.82) becomes “euro 100”. An amount due that does not exceed EUR 100 is paid together with the following month’s amount, and in any case by 16 December of the same year. Comma 2 makes the same change for quarterly payers in article 7, comma 1, letter a), of DPR 542/1999, deferring to the following quarter. That provision also said 16 December, but D.Lgs. 108/2024, article 2, comma 3 (GU n. 182 of 5 August 2024), replaced it with 16 November, so quarterly payers must pay a carried-forward amount by 16 November at the latest.
Comma 3 applies the change to amounts due on the periodic VAT settlements for tax year 2024 onwards. Comma 4 made a parallel increase for minimum payments of withholding tax on self-employment income. That comma has since been repealed by D.Lgs. 33/2025, as amended by DL 200/2025.
What it means
The change has applied since the 2024 settlements and is still in force. Article 1, comma 4, of DPR 100/1998, as in force on 1 November 2026, still reads “non supera il limite di euro 100”.
In practice, a business whose VAT liability for a month or quarter is EUR 100 or less carries it forward and adds it to the next period’s payment. It is not a late payment. The backstops, 16 December for monthly payers and 16 November for quarterly payers, mean no small balance can be carried into the next year. The repeal of comma 4 does not affect the VAT threshold in commi 1 to 3.
Proof
«lire cinquantamila» sono sostituite dalle seguenti: «euro 100»"fifty thousand lire" are replaced by "euro 100"
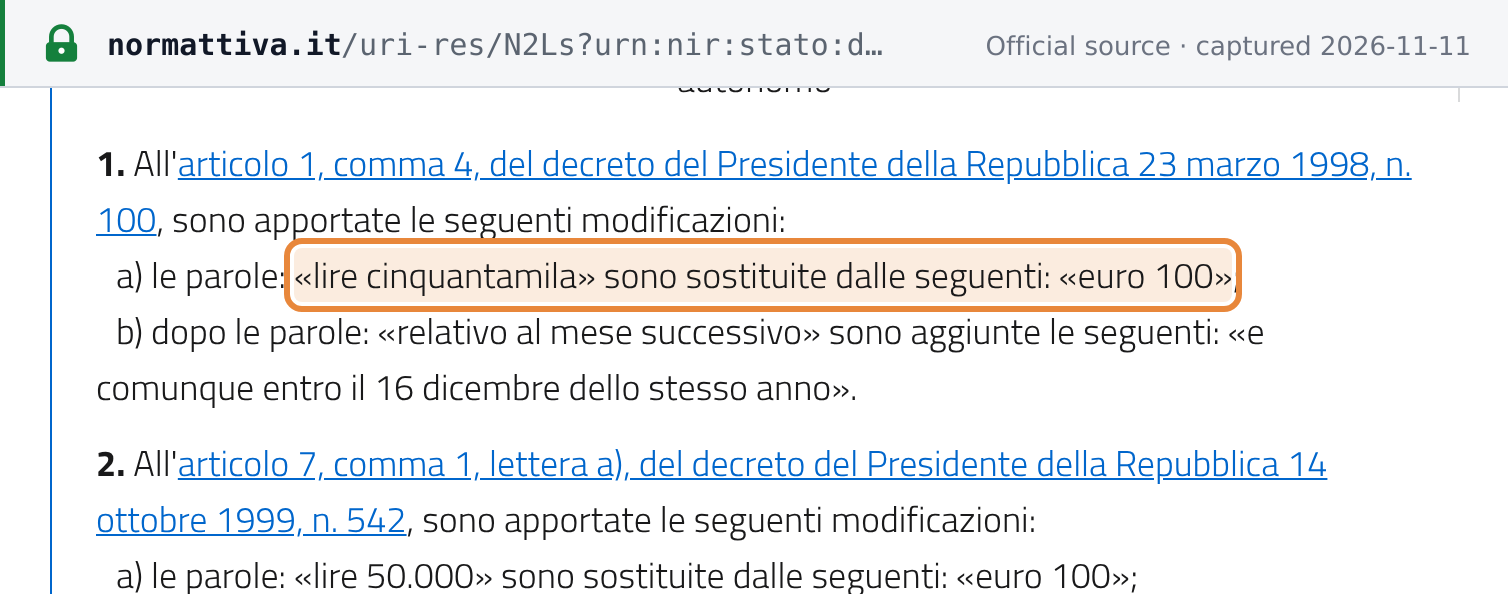 Source snapshot of the official page. Open full size ↗