Italy extends the 5% VAT rate to mountaineering courses given by registered instructors from 2025
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 31 December 2024
- Effective
- 1 January 2025
- Instrument
- IT-ACT-207-2024
- Authority
- Gazzetta Ufficiale della Repubblica Italiana
- Verified
- Fetched from official source · high confidence
Mountain guides and mountaineering schools whose courses are given by instructors enrolled in regional or national registers and are not VAT-exempt.
No action — in force since 1 January 2025. Mountain guides and schools giving mountaineering courses through registered instructors charge 5% VAT on those courses where they are not exempt.
Legge 30 dicembre 2024, n. 207 (Legge di bilancio 2025; GU n. 305 of 31 December 2024, SO n. 43), Art. 1, comma 64, amended number 1-septies of Tabella A, Parte II-bis of DPR 633/1972 (inserted by D.L. 113/2024 for winter-sports courses) from 1 January 2025, extending the 5% VAT rate to courses in mountaineering (attività alpinistica) as defined by Art. 2(1)(c) of Legge 2 gennaio 1989, n. 6 on the mountain-guide profession, when given by persons enrolled in the regional or national registers and not VAT-exempt.
What changed in detail
Law 30 December 2024, n. 207, the 2025 Budget Law (Gazzetta Ufficiale n. 305, supplemento ordinario n. 43, of 31 December 2024), Article 1, comma 64, amends number 1-septies of Tabella A, Parte II-bis, of DPR 633/1972 from 1 January 2025. Number 1-septies had been inserted by Decree-Law 113/2024 to tax winter-sports courses at 5% (record).
Comma 64 makes three changes to its wording:
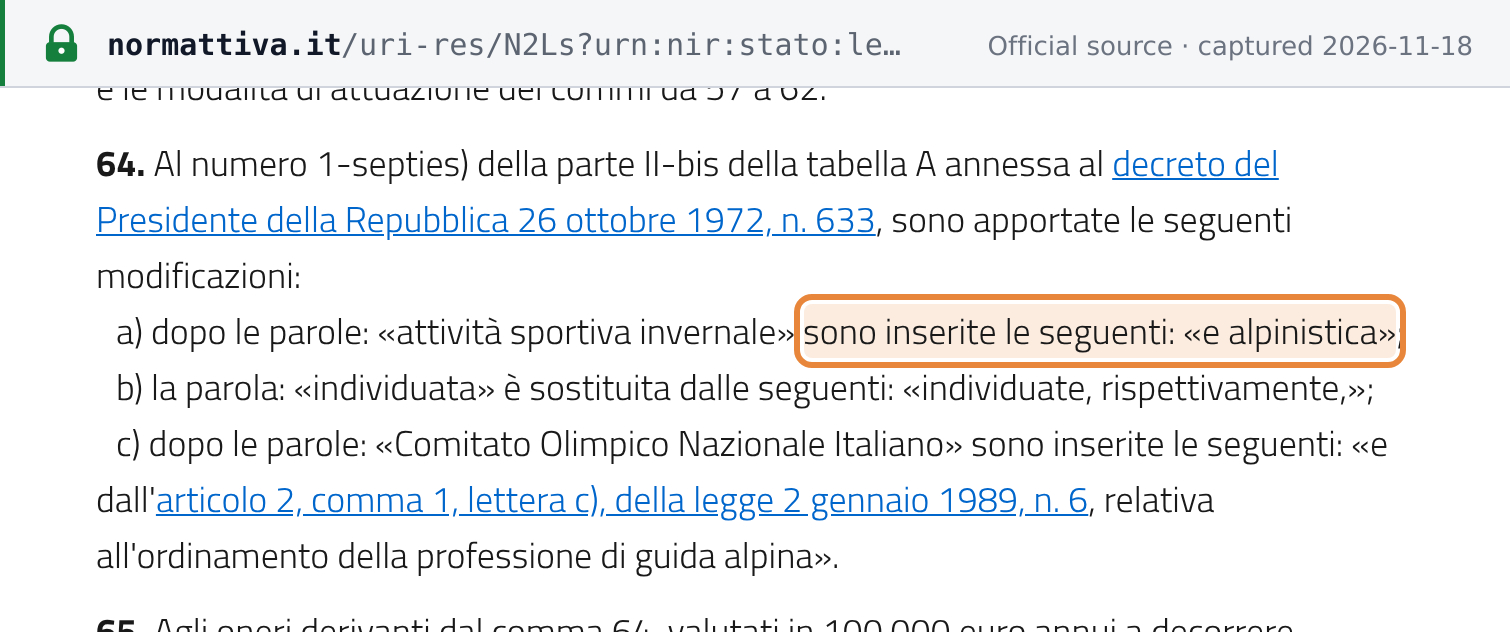
- letter a) adds “e alpinistica” after “attività sportiva invernale”, so the number covers courses in winter sports and in mountaineering;
- letter b) turns “individuata” into “individuate, rispettivamente”, so each activity has its own definition;
- letter c) defines mountaineering by reference to Article 2(1)(c) of Law 2 January 1989, n. 6, on the mountain-guide profession, which covers teaching mountaineering and ski-mountaineering techniques.
The other conditions are unchanged: the courses must be given, including in organised form, by persons enrolled in regional or national registers, and the 5% rate applies only where they are not VAT-exempt. Comma 65 puts the cost at EUR 100,000 a year from 2025.
What it means
The rule is still in force. It covers courses, not guided ascents or mountain-guide services in general, so a guide’s invoice may carry 5% for a course and the ordinary rate for a guided climb. Exempt courses stay exempt.
From 1 January 2027 the VAT Testo unico, D.Lgs. 10/2026, merges the winter-sports and mountaineering wording into number 6 of Parte III of its Tabella A (record). The rate does not change. The same Budget Law also made training for employment agencies taxable (record).
Proof
Al numero 1-septies) della parte II-bis della tabella A annessa al decreto del Presidente della Repubblica 26 ottobre 1972, n. 633, sono apportate le seguenti modificazioni: a) dopo le parole: «attività sportiva invernale» sono inserite le seguenti: «e alpinistica»In number 1-septies) of Part II-bis of Table A annexed to Presidential Decree 26 October 1972, n. 633, the following amendments are made: a) after the words "winter sporting activity" the following are inserted: "and mountaineering"
 Source snapshot of the official page. Open full size ↗