Italy makes training supplied to employment agencies through the bilateral fund subject to VAT from 2025
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 31 December 2024
- Effective
- 1 January 2025
- Instrument
- IT-ACT-207-2024
- Authority
- Gazzetta Ufficiale della Repubblica Italiana
- Verified
- Fetched from official source · high confidence
Training bodies and companies financed through the bilateral fund of Art. 12(4) D.Lgs. 276/2003 that train for authorised employment (temporary-work) agencies, and those agencies.
No action — in force since 1 January 2025. Training bodies and companies (funded through the bilateral fund under D.Lgs. 276/2003 Art. 12(4)) must charge VAT on courses provided to temp-work agencies. Pending litigation on pre-2025 services can be settled under the c.40–43 procedure (pay assessed VAT without interest/penalties). Previously recognised exempt treatment is saved for pre-2025 services not yet definitively assessed.
Legge 30 dicembre 2024, n. 207 (Legge di bilancio 2025; GU n. 305 of 31 December 2024, SO n. 43), Art. 1, comma 38: from 1 January 2025, training services supplied to employment agencies authorised under Art. 4 of D.Lgs. 276/2003 by training bodies and companies financed through the bilateral fund of Art. 12(4) of that decree are subject to VAT. Comma 39 saves earlier behaviour where no assessment has become final (without refunds), and commi 40–44 let pending cases be settled by paying the VAT assessed without penalties or interest.
What changed in detail
Law 30 December 2024, n. 207, the 2025 Budget Law (Gazzetta Ufficiale n. 305, supplemento ordinario n. 43, of 31 December 2024), Article 1, comma 38, applies from 1 January 2025.
It provides that training services supplied to employment agencies authorised under Article 4 of D.Lgs. 276/2003 are subject to VAT when the supplier is a training body or company financed through the bilateral fund set up under Article 12(4) of that decree. This fund finances training for temporary agency workers.
Comma 39 addresses the earlier uncertainty about how these services were treated. Conduct adopted by taxpayers for services supplied before the law entered into force is saved where no act has become final, and no VAT is refunded.
Commi 40 to 44 let pending disputes be settled by paying the VAT assessed, without penalties or interest.
The same Budget Law also changed the 10% waste-management rate (record), extended the 5% rate to mountaineering courses (record) and set up the cash-register/POS pairing duty (record).
What it means
The rule is still in force. Training bodies paid from the bilateral fund invoice VAT on courses for employment agencies; they can no longer treat them as exempt or outside scope. For the agencies, the VAT is input tax whose deductibility follows their own position. Past exempt treatment is protected unless an assessment had become final, and open disputes can be closed by paying the VAT alone.
From 1 January 2027 the VAT Testo unico, D.Lgs. 10/2026, restates comma 38 and the comma 39 saving in its Article 169, letter c) (record).
Proof
Le prestazioni di formazione rese ai soggetti autorizzati alla somministrazione di lavoro ai sensi dell'articolo 4 del decreto legislativo 10 settembre 2003, n. 276, da enti e società di formazione finanziati attraverso il fondo bilaterale costituito ai sensi dell'articolo 12, comma 4, del citato decreto legislativo n. 276 del 2003 sono imponibili ai fini dell'imposta sul valore aggiunto.Training services supplied to persons authorised to supply labour under Article 4 of Legislative Decree 10 September 2003, n. 276, by training bodies and companies financed through the bilateral fund set up under Article 12, paragraph 4, of that Legislative Decree n. 276 of 2003 are subject to value added tax.
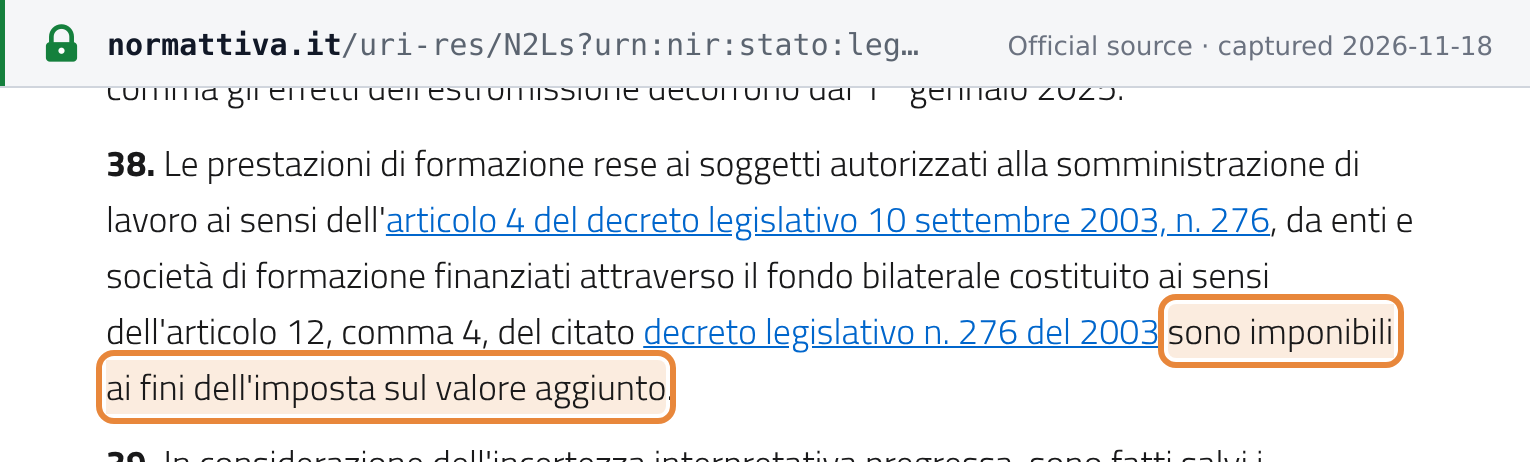 Source snapshot of the official page. Open full size ↗