Italy raises VAT on period products, nappies and infant formula from 5% to 10% from 1 January 2024
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 30 December 2023
- Effective
- 1 January 2024
- Instrument
- IT-LEGGE-213-2023
- Authority
- Gazzetta Ufficiale della Repubblica Italiana
- Verified
- Fetched from official source · high confidence
Manufacturers, distributors and retailers of feminine hygiene products, baby nappies, infant formula and child car seats in Italy.
No action — monitoring only.
Law 30 December 2023, n. 213 (Legge di Bilancio 2024, GU n. 303 S.O. n. 40, 30 December 2023), Art. 1, commi 45–46, ended the 5% reduced rate on these products (most were moved to 5% by the 2023 Budget Law; menstrual cups and compostable or washable period products had been at 5% since 2020 under DL 124/2019). From 1 January 2024: (1) feminine hygiene products (absorbents, tampons, menstrual cups) and baby nappies reverted from 5% to 10%; (2) infant formula (powder/liquid) likewise reverted from 5% to 10%; (3) child car seats reverted from 5% to the standard 22% rate. The 5% provisions were removed from Tabella A, Parte II-bis, DPR 633/1972; the products are re-inserted at 10% in Parte III.
What changed in detail
Law 30 December 2023, n. 213, the 2024 Budget Law (Gazzetta Ufficiale n. 303, supplemento ordinario n. 40, of 30 December 2023), ended the 5% reduced rate on these products. Most of it came from the 2023 Budget Law (L. 197/2022, art. 1, comma 72), which extended 5% to all absorbent products and tampons and to nappies, infant formula and child car seats. Menstrual cups and compostable or washable period products had been at 5% since 1 January 2020 (DL 124/2019, art. 32-ter).
Article 1, comma 45, letter a) abrogates numbers 1-quinquies) and 1-sexies) of Table A, Part II-bis, of DPR 633/1972, the list of goods taxed at 5%. Letter b) amends Part III, the list of goods taxed at 10%: number 65) is rewritten to cover powdered or liquid milk for infants and young children and infant food preparations, and new numbers 114.1) and 114.2) add absorbent products and tampons for feminine hygiene, menstrual cups and baby nappies.
The effect, from 1 January 2024, is:
- feminine hygiene products and menstrual cups: 5% to 10% (5% since 2023 for absorbents and tampons generally, since 2020 for menstrual cups and compostable or washable products);
- baby nappies: 5% to 10%;
- infant formula and infant food preparations: 5% to 10%;
- child car seats, which had been in number 1-sexies) and are not re-listed: 5% to the standard 22% rate.
What it means
For nappies, infant formula, child car seats and conventional absorbents and tampons, the 5% rate lasted one year, 2023. Menstrual cups and compostable or washable period products had been at 5% since 2020. From 1 January 2024, sellers had to apply 10% (22% for child car seats) to supplies made from that date, with price lists and till settings updated to match.
The 10% rate is still in force. The consolidated Table A on Normattiva, in force on 1 November 2026, still lists numbers 114.1) and 114.2) in Part III and shows 1-quinquies) and 1-sexies) as abrogated by L. 213/2023. From 1 January 2027 DPR 633/1972 and its tables are replaced by the VAT Testo unico, D.Lgs. 10/2026 (record). Rate tables that cite Table A, Part III, number 114.1) need their references remapped.
Proof
« 114.1) prodotti assorbenti e tamponi destinati alla protezione dell'igiene femminile; coppette mestruali; 114.2) pannolini per bambini »"114.1) absorbent products and tampons for the protection of feminine hygiene; menstrual cups; 114.2) baby nappies"
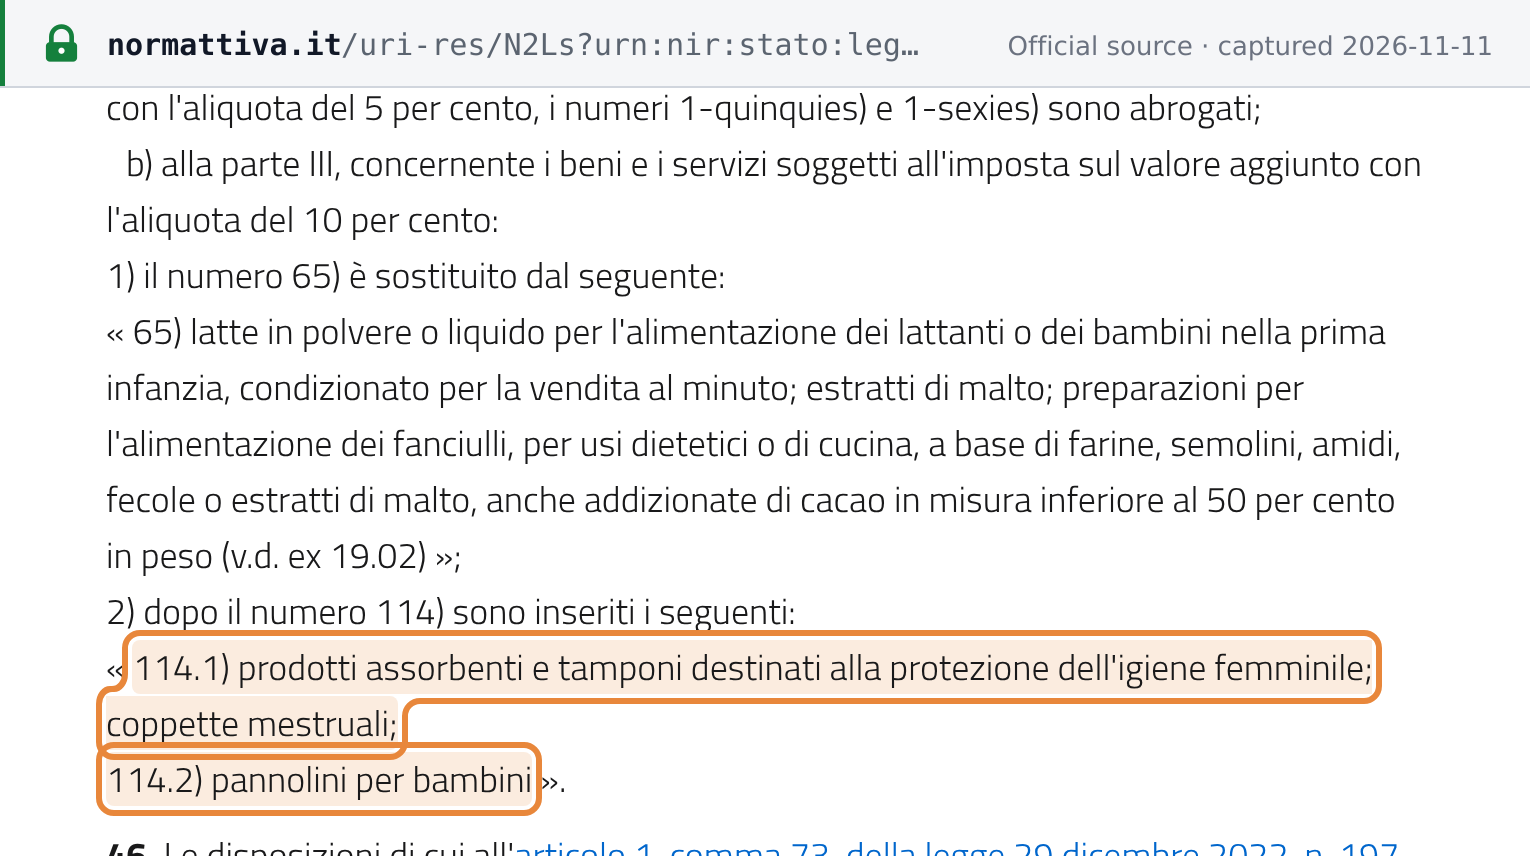 Source snapshot of the official page. Open full size ↗