Italy extends the 5% VAT rate on social, health and education services to social enterprises in company form
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 12 December 2025
- Effective
- 13 December 2025
- Instrument
- IT-LEGISLATIVE-DECREE-186-2025
- Authority
- Gazzetta Ufficiale della Repubblica Italiana
- Verified
- Fetched from official source · high confidence
Social enterprises constituted as companies under Book V, Title V of the Italian Civil Code that supply qualifying social, health, care and education services to the listed categories of people.
No action — in force since 13 December 2025. Social enterprises organised as companies that supply the qualifying social and care services may invoice them at 5% VAT.
Decreto legislativo 4 dicembre 2025, n. 186 (GU n. 288 of 12 December 2025, in force 13 December 2025), Art. 4, extended the 5% VAT rate of number 1 of Tabella A, Parte II-bis of DPR 633/1972 (social, health and education services under Art. 10 nn. 18, 19, 20, 21 and 27-ter supplied to the listed categories of persons) to social enterprises constituted in company form under Book V, Title V of the Civil Code, in addition to social cooperatives and their consortia.
What changed in detail
Legislative Decree 4 December 2025, n. 186 (Gazzetta Ufficiale n. 288 of 12 December 2025, in force 13 December 2025) amends the tax rules for Third-sector entities. Its Article 4 amends number 1 of Tabella A, Parte II-bis, of DPR 633/1972, the list of supplies taxed at 5%.
Number 1 covers the social, health, care and education services listed in Article 10, numbers 18, 19, 20, 21 and 27-ter, of DPR 633/1972, when supplied to the categories of people the number lists, such as elderly and disabled people, drug addicts, minors and people in difficulty. Until this change the 5% rate applied only where the supplier was a social cooperative or a consortium of social cooperatives.
Article 4 adds social enterprises constituted in one of the company forms of Book V, Title V, of the Civil Code (for example an S.r.l. or S.p.A. with social-enterprise status). No separate start date is set, so the change applies from 13 December 2025.
The same decree deferred the VAT reform for associations to 2036 (record).
What it means
The rule is still in force. Social enterprises organised as companies can invoice qualifying care and education services at 5%, as social cooperatives already did, instead of treating them as exempt. That matters because a taxable supply carries a right to deduct input VAT, which an exempt one does not. Each enterprise needs to check that both the service and the recipient fall within number 1.
From 1 January 2027 the VAT Testo unico, D.Lgs. 10/2026, already includes social enterprises in number 1 of Parte III of its Tabella A (record).
Proof
Al numero 1 della tabella A, parte II-bis, allegata al decreto del Presidente della Repubblica 26 ottobre 1972, n. 633, dopo le parole: «cooperative sociali e loro consorzi» sono inserite le seguenti: «e dalle imprese sociali costituite nelle forme di cui al libro V, titolo V, del codice civile».In number 1 of Table A, Part II-bis, annexed to Presidential Decree 26 October 1972, n. 633, after the words "social cooperatives and their consortia" the following are inserted: "and by social enterprises constituted in the forms provided for in Book V, Title V, of the Civil Code".
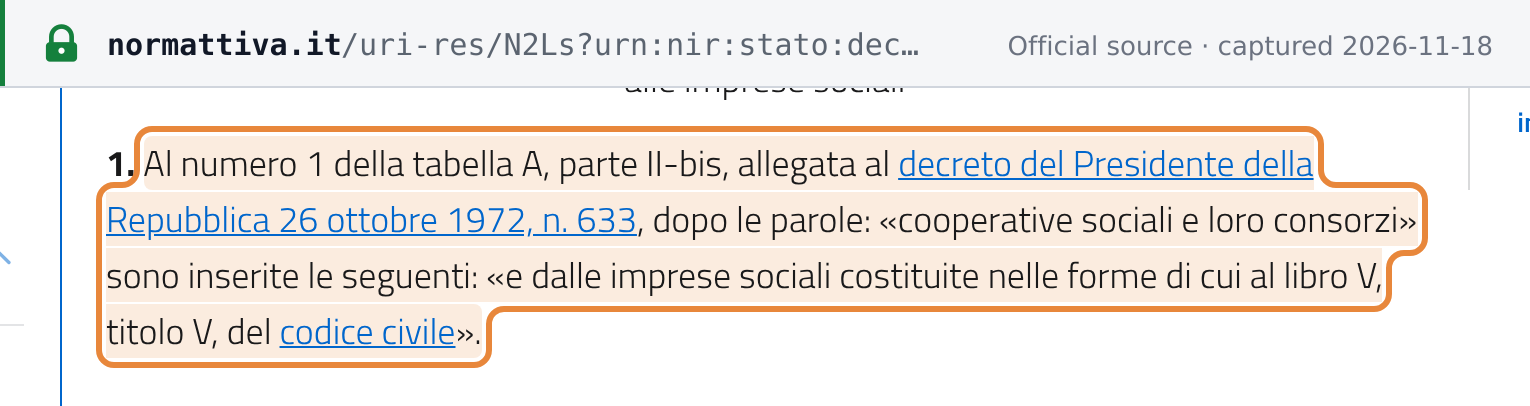 Source snapshot of the official page. Open full size ↗