Italy defers the move of associations' member services from outside VAT scope to exemption until 2036
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- FYI
- Announced
- 12 December 2025
- Effective
- 13 December 2025
- Instrument
- IT-LEGISLATIVE-DECREE-186-2025
- Authority
- Gazzetta Ufficiale della Repubblica Italiana
- Verified
- Fetched from official source · high confidence
Associations and other associative bodies in Italy (cultural, sports, political, trade-union, religious and similar) that supply goods or services to their members against specific fees.
No action — associations keep their current outside-scope VAT treatment of member activities; the move to exempt treatment (and the related VAT registration and filing duties) is deferred to 1 January 2036.
Decreto legislativo 4 dicembre 2025, n. 186 (GU n. 288 of 12 December 2025, in force 13 December 2025), Art. 6, replaced '1° gennaio 2026' with '1° gennaio 2036' in Art. 1(683) of Legge 234/2021. This defers until 1 January 2036 the application of Art. 5(15-quater) of D.L. 146/2021, which moves certain supplies by associative bodies to their members from outside the scope of VAT to VAT-exempt treatment. The change had been due to apply from 1 January 2026.
What changed in detail
Legislative Decree 4 December 2025, n. 186 (Gazzetta Ufficiale n. 288 of 12 December 2025, in force 13 December 2025), Article 6, amends Article 1(683) of Law 234/2021, the 2022 Budget Law. It replaces “1° gennaio 2026” with “1° gennaio 2036”.
Comma 683 sets the date from which Article 5(15-quater) of Decree-Law 146/2021 applies. That provision moves certain supplies by associative bodies to their members and associates from outside the scope of VAT to VAT-exempt treatment.
The move was due to apply from 1 January 2026, less than three weeks after the decree came into force. Article 6 pushes it back by ten years, to 1 January 2036.
The same decree extended the 5% rate to social enterprises in company form (record).
What it means
The deferral is in force. Associations keep treating qualifying member-facing activities as outside the scope of VAT. An exempt supply, unlike an outside-scope one, would have brought a VAT position and filing duties, so associations that were preparing for those from 2026 can stand down.
The VAT Testo unico, D.Lgs. 10/2026, which applies from 1 January 2027, does not change the position. Its Article 169, letter bbb), keeps Article 5(15-quater) applying only from the comma 683 date (record). The open point is EU compatibility: the exempt regime was written to align the treatment with EU VAT rules, and a ten-year deferral leaves the old treatment in place meanwhile.
Proof
All'articolo 1, comma 683, secondo periodo, della legge 30 dicembre 2021, n. 234, le parole: «1° gennaio 2026» sono sostituite dalle seguenti: «1° gennaio 2036».In Article 1, paragraph 683, second sentence, of Law 30 December 2021, n. 234, the words "1 January 2026" are replaced by the following: "1 January 2036".
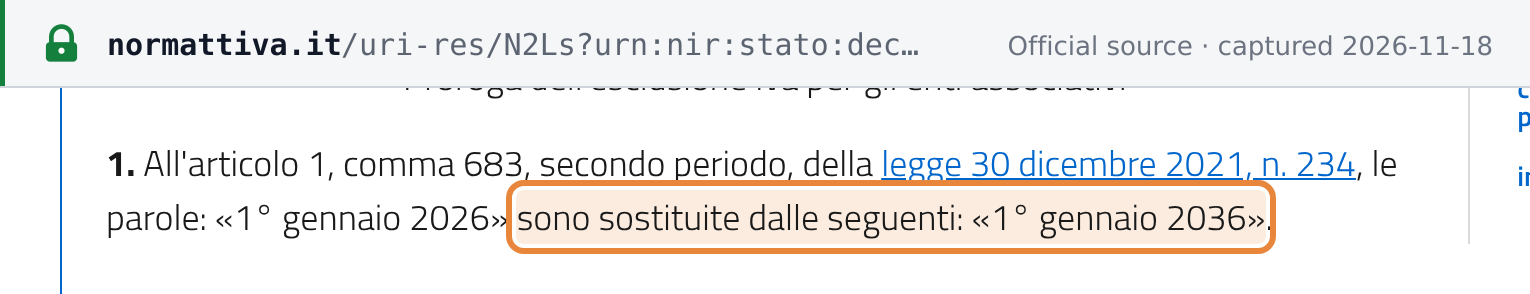 Source snapshot of the official page. Open full size ↗