Japan exempts tuition for advanced courses (専攻科) at specialised training colleges from consumption tax
This page records one dated change. For the rules in Japan as they stand today, see the Japan guide →
- Jurisdiction
- Japan
- Tax
- JCT
- Change type
- Update
- Status
- In force
- Impact
- FYI
- Announced
- 31 March 2026
- Effective
- 1 April 2026
- Instrument
- JP-ACT--8-12
- Authority
- 国会 (National Diet of Japan)
- Verified
- Fetched from official source · high confidence
Operators of specialised training colleges (専修学校) in Japan that run advanced courses (専攻科), and their students.
No action — in force since 1 April 2026. Schools operating advanced courses (専攻科) at specialised training colleges (専修学校) now provide non-taxable educational services; tuition for those courses does not attract JCT.
令和8年法律第12号 (FY2026 Tax Reform Act, promulgated 31 March 2026, effective 1 April 2026) amended CT Act Appended Table 2 Item 11 (別表第二 第十一号) to add advanced courses (専攻科) of specialised training colleges (専修学校) to the non-taxable education provision. Under the amended text, tuition and educational services provided by specialised training colleges in their senior (高等), specialist (専門), general (一般) or advanced (専攻科) courses are non-taxable.
What changed in detail
The FY2026 tax reform act, 所得税法等の一部を改正する法律 (令和8年法律第12号), promulgated on 31 March 2026, amended item 11(ロ) of Appended Table 2 (別表第二) of the Consumption Tax Act. That table lists supplies that are non-taxable.
Item 11(ロ) covers education provided by the founder of a specialised training college (専修学校) under Article 124 of the School Education Act. Before the amendment it named three courses: senior (高等課程), specialist (専門課程) and general (一般課程). The amended text adds advanced courses (専攻科) under Article 125-2(1) of the School Education Act. Tuition and other educational services in those courses are therefore outside consumption tax.
The 2026 Act’s main commencement date is 1 April 2026. Supplementary Art. 1(9)(イ), which defers several consumption tax amendments to 1 April 2028, expressly excludes the amendment to item 11(ロ), so it took effect on 1 April 2026.
What it means
The exemption is in force and unchanged. The current consolidated text on e-Gov, and the revision scheduled for 1 April 2028, both still name 専攻科 in item 11(ロ).
The change keeps consumption tax in line with the School Education Act, which provides for advanced courses at specialised training colleges in Article 125-2. Colleges running 専攻科 programmes stop charging consumption tax on that tuition. Because those fees are now non-taxable sales, they also lower the college’s taxable-sales ratio, which can reduce the input credit it may claim on shared costs.
Proof
学校教育法第百二十四条(専修学校)に規定する専修学校を設置する者が当該専修学校の同法第百二十五条第一項(課程)に規定する高等課程、専門課程若しくは一般課程又は同法第百二十五条の二第一項(専攻科)に規定する専攻科における教育として行う役務の提供The provision of services, as education, by the founder of a specialised training college under Article 124 (Specialised Training Colleges) of the School Education Act, in the senior course, specialist course or general course under Article 125(1) (Courses) of that Act, or in an advanced course under Article 125-2(1) (Advanced Courses) of that Act, of that college.
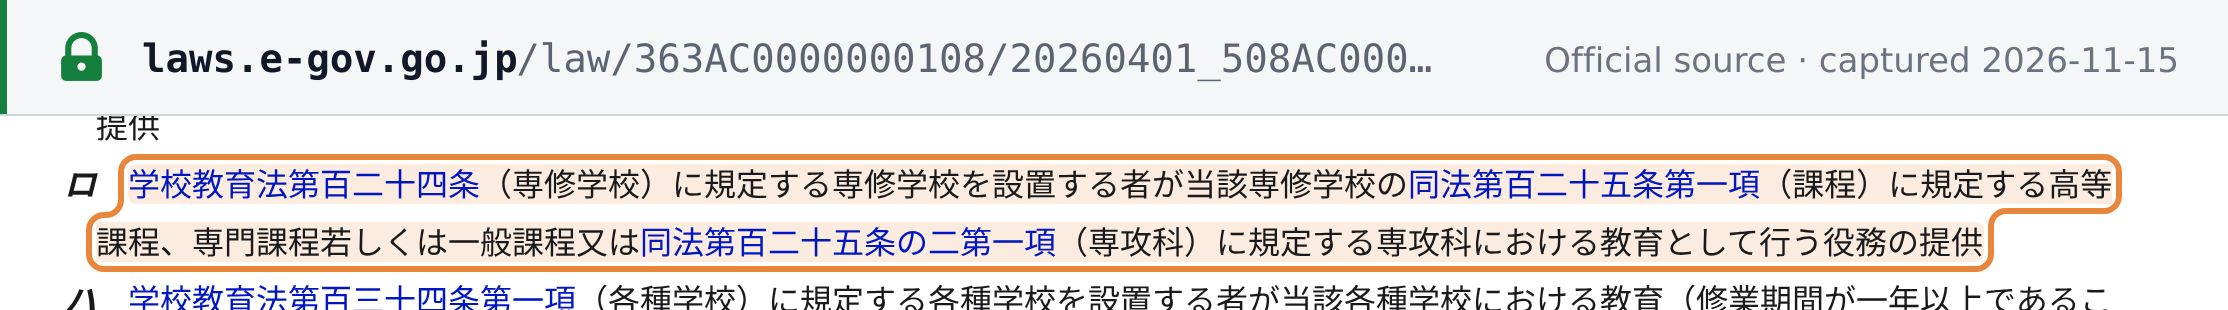 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · 消費税法(昭和六十三年法律第百八号), e-Gov law revision 363AC0000000108_20260401_508AC0000000012 (as amended by 令和八年法律第十二号, in force 2026-04-01), 別表第二第十一号ロ · laws.e-gov.go.jp