Japan denies input credit on goods bought knowing they were sold tax-free to tourists
This page records one dated change. For the rules in Japan as they stand today, see the Japan guide →
- Jurisdiction
- Japan
- Tax
- JCT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 30 March 2024
- Effective
- 1 April 2024
- Instrument
- JP-ACT--6-8
- Authority
- 国会 (National Diet of Japan)
- Verified
- Fetched from official source · high confidence
Businesses in Japan, typically resellers and second-hand or precious-metal dealers, that buy goods knowing they were sold tax-free through the tax-free shop scheme.
No action — in force since 1 April 2024. Businesses (typically resellers / precious-metal dealers) that knowingly buy goods that were sold duty-free through the tax-free shop scheme cannot claim JCT input credit on those purchases.
令和6年法律第8号 (FY2024 Tax Reform Act, promulgated 30 March 2024, effective 1 April 2024) inserted CT Act Article 30 paragraph 12. A business that knowingly acquires goods that were sold duty-free through the tax-free shop (輸出物品販売場) scheme — on which consumption tax was not paid or was exempted — cannot claim input credit (仕入税額控除) for the consumption tax on that purchase.
What changed in detail
The FY2024 tax reform act, 所得税法等の一部を改正する法律 (令和6年法律第8号), promulgated on 30 March 2024 and in force on 1 April 2024, amended Consumption Tax Act Art. 30(12).
Art. 30(12) already denied input credit on taxable goods removed from a bonded area without paying the consumption tax due, where the buyer knew the tax was unpaid. That text came from 令和5年法律第79号. The 2024 Act adds goods on which consumption tax was exempted under Art. 8(1): goods sold tax-free through a tax-free shop (輸出物品販売場) to a non-resident traveller who was meant to take them out of Japan.
A business that buys such goods, knowing at the time of purchase that the tax was exempted, cannot claim input credit (仕入税額控除) on that purchase. A buyer who did not know is not caught. Supplementary Art. 13(9) applies the amendment to taxable purchases made on or after 1 April 2024; earlier purchases follow the old rule.
What it means
The rule is still in force, and the current consolidated text of Art. 30(12) is unchanged. It reaches goods that were bought tax-free and then resold inside Japan instead of leaving the country.
The tax-free scheme itself has since changed. From 1 November 2026, tax-free shops charge consumption tax at the till and refund it once export is confirmed (Japan moves tax-free shopping to the refund method). Art. 30(12) still names Art. 8(1) goods. Dealers buying second-hand luxury goods should keep their checks on where the goods came from.
Proof
第一項の規定は、その課税仕入れの際に、当該課税仕入れに係る資産が納付すべき消費税を納付しないで保税地域から引き取られた課税貨物又は第八条第一項の規定により消費税が免除された物品に係るものである場合(当該課税仕入れを行う事業者が、当該消費税が納付されていないこと又は免除されたものであることを知つていた場合に限る。)には、当該課税仕入れに係る消費税額については、適用しない。Paragraph (1) does not apply to the consumption tax on a taxable purchase where, at the time of the purchase, the asset concerned is taxable goods removed from a bonded area without paying the consumption tax due, or goods on which consumption tax was exempted under Article 8(1) (limited to cases where the business making the purchase knew that the consumption tax had not been paid or had been exempted).
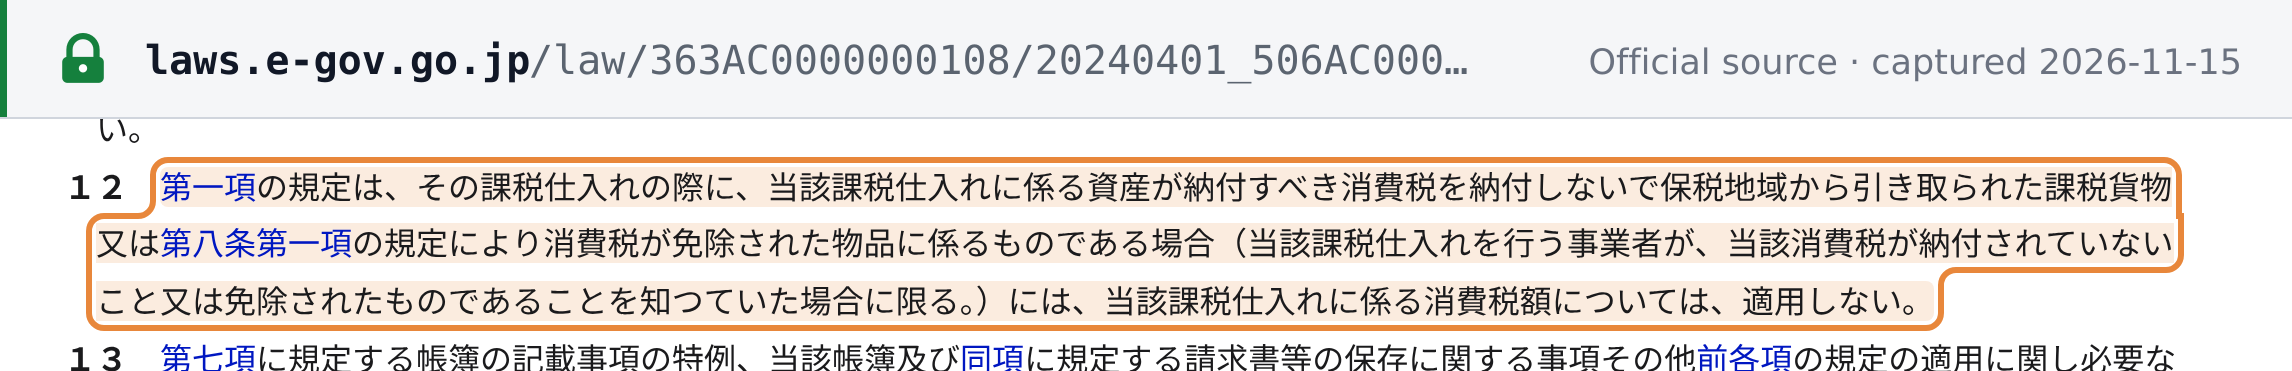 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · 消費税法(昭和六十三年法律第百八号), e-Gov law revision 363AC0000000108_20240401_506AC0000000008 (as amended by 令和六年法律第八号, in force 2024-04-01), Art. 30(12) · laws.e-gov.go.jp