Kenya pre-fills VAT returns from January 2024 and disallows input VAT not validated through eTIMS
This page records one dated change. For the rules in Kenya as they stand today, see the Kenya guide →
- Jurisdiction
- Kenya
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- FYI
- Announced
- 28 November 2023
- Effective
- 1 January 2024
- Authority
- Kenya Revenue Authority
- Verified
- Fetched from official source · high confidence
All VAT-registered persons in Kenya, from the January 2024 tax period.
No action — monitoring only.
KRA public notice of 28 November 2023 announced that VAT returns would be pre-filled with tax information available to KRA with effect from the January 2024 tax period; any input VAT claim not validated through TIMS/eTIMS, or against customs import declarations for import VAT, will not be allowed. The pre-filled return remains a self-assessment return under s.28(4) of the Tax Procedures Act (Cap. 469B).
What changed in detail
In a public notice dated 28 November 2023, “Simplification of the VAT Return Filing Process”, the Kenya Revenue Authority (KRA) announced that the VAT return would be pre-filled with tax information available to KRA, with effect from the January 2024 tax period.
The notice reminded taxpayers of their obligation to issue electronic tax invoices and transmit the invoice details to KRA. It stated that any input VAT claim not validated through TIMS/eTIMS, or, for import VAT, against existing customs import declarations, will not be allowed.
The notice also said that the pre-filled VAT return remains a self-assessment return under section 28(4) of the Tax Procedures Act (CAP 469B), and that a taxpayer is not relieved of the obligation to confirm the accuracy of the declaration before submitting it. KRA pointed taxpayers to its published list of approved eTIMS third-party system-to-system integrators.
What it means
This notice is where eTIMS stopped being only an invoicing obligation and became a condition of input VAT recovery: a purchase invoice that never reached KRA through TIMS/eTIMS no longer supports a claim, whatever the paper copy says. Seen from late 2026, the rule is still the operating basis of Kenyan VAT returns. The practical burden sits with the buyer, who has to chase suppliers to transmit their invoices, and the self-assessment point means a wrong pre-filled figure is still the filer’s error, not KRA’s.
Proof
Please note that any input VAT claim that is not validated through TIMS/eTIMS or against existing customs import declarations for import VAT claims will not be allowed.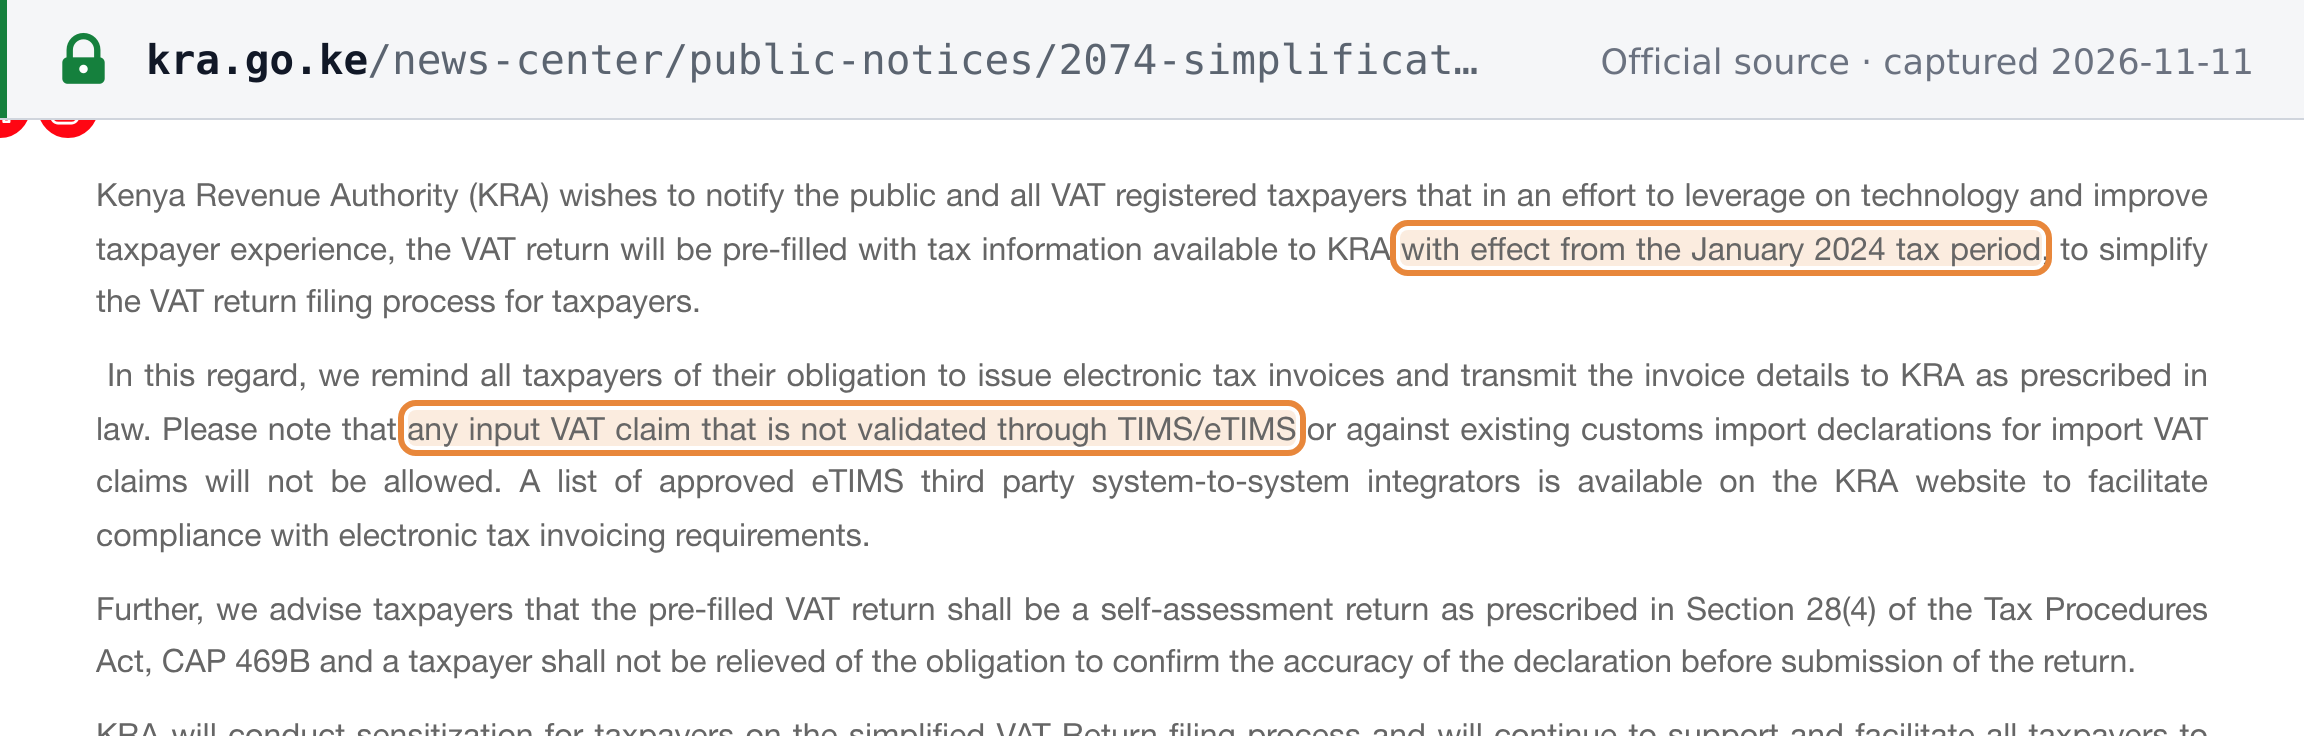 Source snapshot of the official page. Open full size ↗