Kenya gives non-VAT-registered businesses until 31 March 2024 to onboard to eTIMS without penalties
This page records one dated change. For the rules in Kenya as they stand today, see the Kenya guide →
- Jurisdiction
- Kenya
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- FYI
- Announced
- 27 December 2023
- Effective
- 31 March 2024
- Authority
- Kenya Revenue Authority
- Verified
- Fetched from official source · high confidence
Persons carrying on business in Kenya who are not registered for VAT.
No action — monitoring only.
KRA public notice of 27 December 2023 reminded all persons carrying on business, including those not registered for VAT, that they must generate and transmit invoices through eTIMS from 1 September 2023; it allowed non-VAT-registered taxpayers to onboard up to 31 March 2024 without the statutory penalties for failing to issue electronic tax invoices, and stated that from 1 January 2024 business expenditure not supported by a valid electronic tax invoice is not deductible for income tax.
What changed in detail
In a public notice dated 27 December 2023, “Electronic Tax Invoicing for Non-VAT Registered Persons”, the Kenya Revenue Authority (KRA) reminded the public that all persons carrying on business, including those not registered for VAT, are required to generate and transmit their invoices to KRA through the electronic Tax Invoice Management System (eTIMS) from 1 September 2023.
The notice stated that, with effect from 1 January 2024, business expenditure not supported by a valid electronic tax invoice is not deductible for income tax purposes.
KRA notified non-VAT-registered taxpayers that onboarding to eTIMS would be available up to 31 March 2024, and that during the onboarding period the penalties provided in law for failing to issue electronic tax invoices would not be imposed on them. Once onboarded, taxpayers must progressively capture onto the KRA system the manual invoices and receipts they issued between 1 January 2024 and the date of onboarding.
What it means
The penalty relief is spent: it ended on 31 March 2024. What outlived it is the obligation it softened. Every Kenyan business, VAT-registered or not, has been inside the eTIMS mandate since September 2023, and the income tax rule gives buyers the enforcement lever, because a supplier who cannot issue an eTIMS invoice costs its customer the deduction. The back-capture duty also means invoices issued in early 2024 before onboarding were never outside the system, only late to it.
Proof
KRA wishes to notify non-VAT registered taxpayers that onboarding to the eTIMS platform will be available up to 31st March, 2024. During the onboarding period, penalties provided in law for failure to issue electronic tax invoices will not be imposed on the non-VAT registered taxpayers.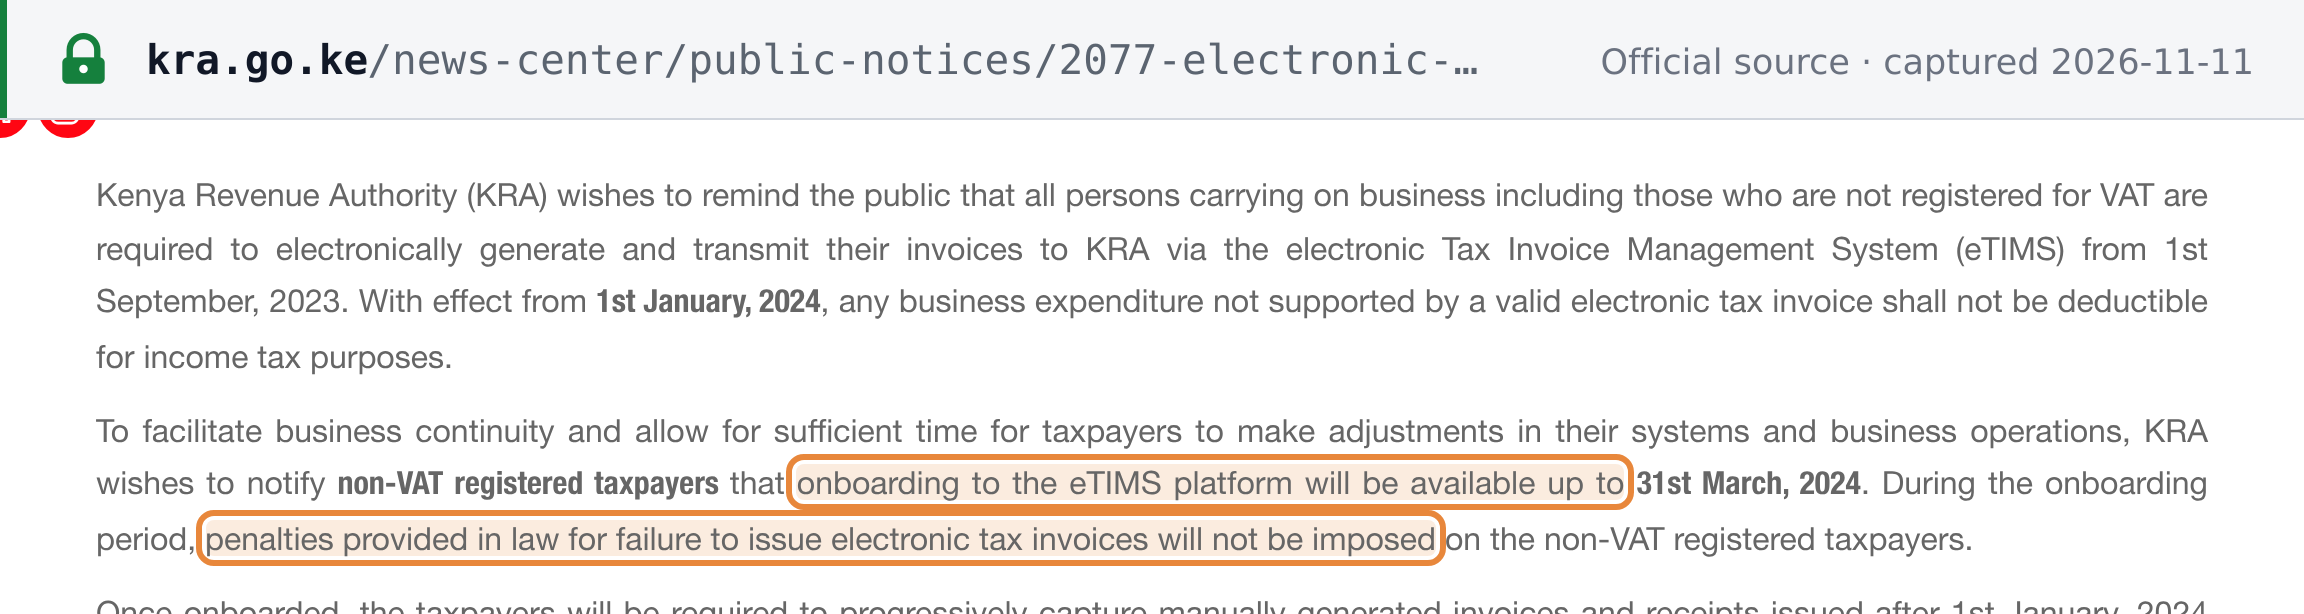 Source snapshot of the official page. Open full size ↗