Kenya exempts the supply of gas meters from VAT (First Schedule paragraph 148, Act No. 3 of 2024)
This page records one dated change. For the rules in Kenya as they stand today, see the Kenya guide →
- Jurisdiction
- Kenya
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 26 April 2024
- Effective
- 26 April 2024
- Instrument
- KE-ACT-Act-No-3-of-2024
- Authority
- National Council for Law Reporting (Kenya Law)
- Verified
- Fetched from official source · high confidence
Importers, manufacturers and sellers of gas meters (tariff 9028.10.00) in Kenya, and their customers.
Suppliers of gas meters (tariff 9028.10.00) do not charge VAT on supply and cannot recover input VAT attributable to those supplies. Purchasers receive gas meters without VAT.
The Statute Law (Miscellaneous Amendments) Act, 2024 (Act No. 3 of 2024), in force 26 April 2024, inserted paragraph 148 into Part I of the First Schedule to the VAT Act, Cap. 476, exempting the supply of gas meters of tariff number 9028.10.00. The same Act deleted paragraph 138 of the First Schedule (an exemption inserted by the Finance Act 2021).
What changed in detail
The Statute Law (Miscellaneous Amendments) Act, 2024 (Act No. 3 of 2024) amended the First Schedule to the Value Added Tax Act, Cap. 476. The consolidated VAT Act records the amendment as made “on 26 April 2024”, the date it took effect.
The Act inserted paragraph 148 into Part I of the First Schedule (exempt supplies of goods):
- The supply of gas meters of tariff number 9028 10 00.
An exempt supply carries no output VAT, and the supplier cannot deduct input VAT attributable to it.
The same Act also deleted paragraph 138 of Part I, an exemption originally inserted by the Finance Act, 2021 (Act No. 8 of 2021, s. 27(a)(xxv)). The consolidation now reads “138. Deleted by Act No. 3 of 2024, Sch.”; it does not reproduce the deleted wording.
What it means
The exemption is still in force. Paragraph 148 sits unchanged in the consolidated VAT Act as at 1 July 2026, after the Finance Act 2025 and the Finance Act 2026 both amended other parts of the First Schedule. Because the item is exempt rather than zero-rated, a local maker or importer of gas meters bears the VAT on its inputs as a cost instead of recovering it. The year’s other First Schedule changes are in the Tax Laws (Amendment) Act 2024 record.
Proof
148. The supply of gas meters of tariff number 9028 10 00.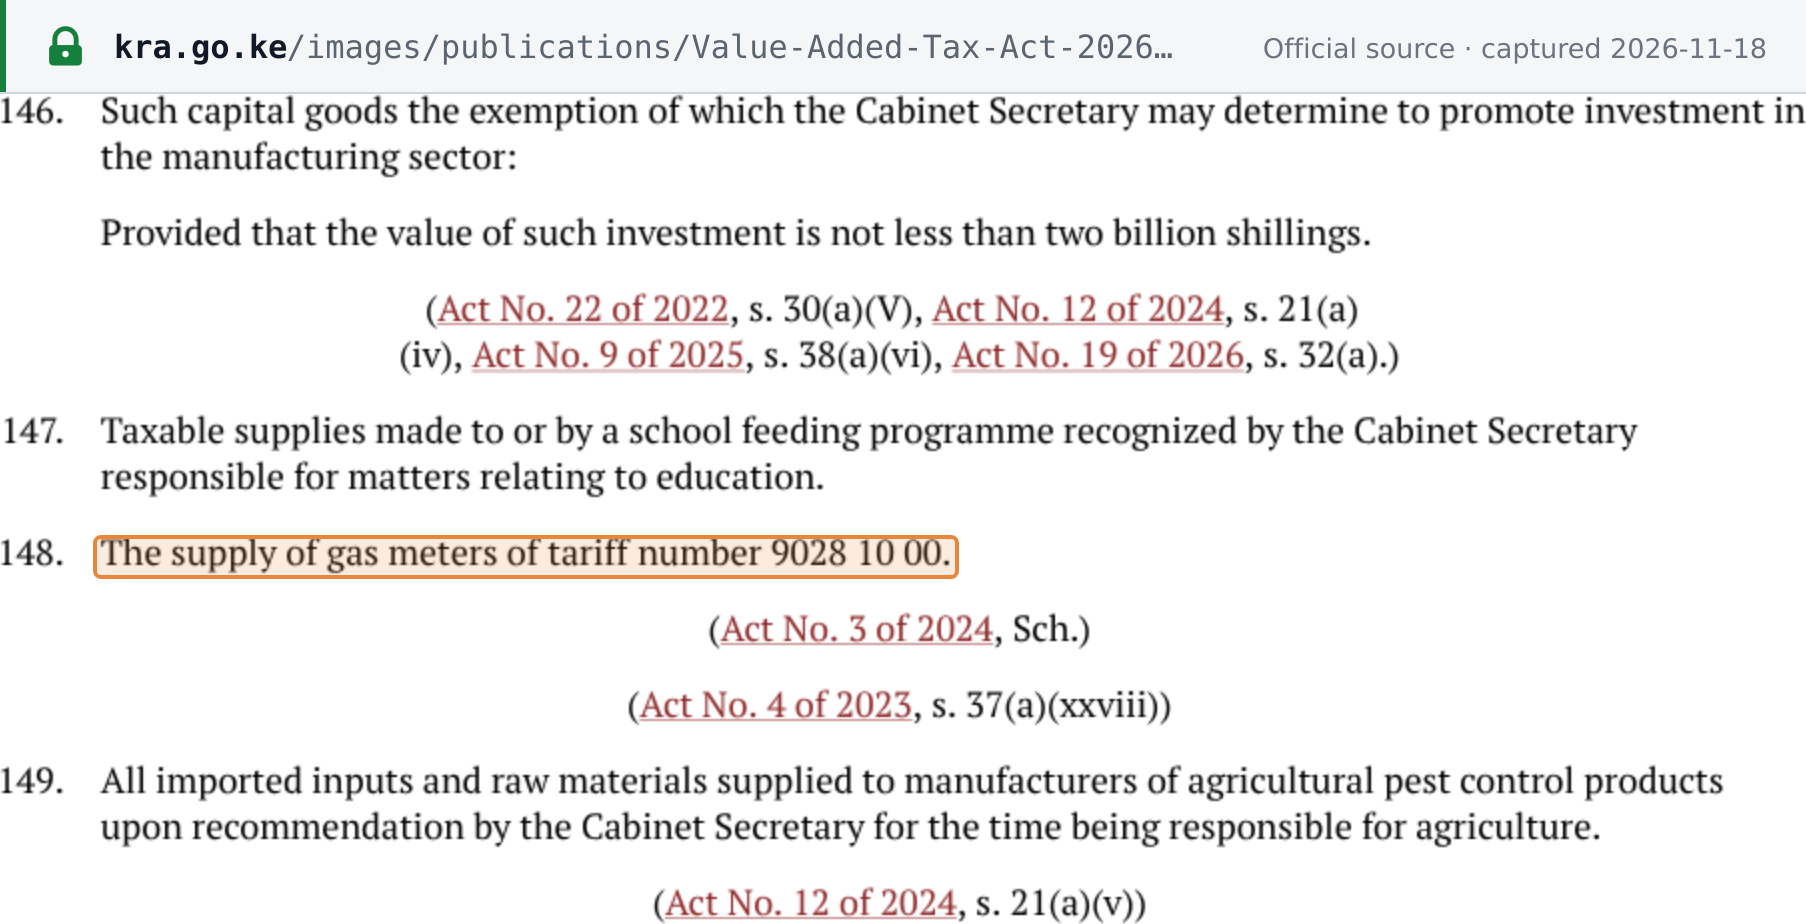 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Value Added Tax Act (Cap. 476), Kenya Law consolidation "Legislation as at 1 July 2026", published by the Kenya Revenue Authority · www.kra.go.ke