Mexico bars insurers from crediting IVA on repairs and replacements bought to settle claims
This page records one dated change. For the rules in Mexico as they stand today, see the Mexico guide →
- Jurisdiction
- Mexico
- Tax
- IVA
- Change type
- Update
- Status
- In force
- Impact
- Action required
- Announced
- 7 November 2025
- Effective
- 1 January 2026
- Instrument
- MX-LEY-DE-INGRESOS-LIF-2026
- Authority
- Diario Oficial de la Federación (DOF)
- Verified
- Fetched from official source · high confidence
Insurance companies that settle claims by repairing damage or replacing the insured property through third parties, including insurers under audit or in dispute over past IVA credits.
Insurance companies cannot credit IVA charged on goods or services they acquire, or IVA paid on imports, when these are used to settle a claim by repairing or replacing the insured property through third parties. This applies from 1 January 2026 (fiscal year 2026). Insurers with past credits of this kind should review the Transitorio Vigésimo Octavo relief.
Article 25, fracción XIV of the Ley de Ingresos de la Federación para el Ejercicio Fiscal de 2026 (DOF 7 November 2025, evening edition), in force from 1 January 2026, makes IVA charged on goods or services acquired, and IVA paid on imports, non-creditable when they are used to fulfil an insurance contract whose indemnity consists of repairing damage or replacing the insured property through third parties. Transitorio Vigésimo Octavo lets licensed insurers treat such IVA as creditable up to 31 December 2024 and grants a stimulus equal to such IVA, or to the related assessed credits with surcharges and penalties, for insurers under audit or in dispute that apply for it.
What changed in detail
Article 25, fraction XIV of the Ley de Ingresos de la Federación para el Ejercicio Fiscal de 2026 (DOF 7 November 2025, evening edition), in force from 1 January 2026, provides that, for the purposes of articles 1o. and 4o. of the IVA law, IVA charged on goods or services acquired, and IVA paid on imports, is not creditable when they are used to fulfil an insurance contract whose indemnity consists of repairing the damage or replacing the insured property through third parties.
Transitorio Vigésimo Octavo deals with the past. Insurers holding a current licence from the Comisión Nacional de Seguros y Fianzas may treat such IVA as creditable for acquisitions up to 31 December 2024. It also grants a stimulus equal to the IVA credited, or to the assessed tax with its surcharges, penalties and enforcement costs, to insurers that are under audit with no assessment issued yet, or that withdraw a pending challenge to an assessment.
The relief required an application by 31 January 2026 and proof that the insurer had corrected its position under the new rule for acquisitions after 31 December 2024, by payment no later than 31 March 2026. That payment could be made in up to 12 instalments ending by 15 December 2026, with surcharges on the IVA waived. Insurers with a final criminal tax conviction, on the 69-B lists or with cancelled CFDI certificates are excluded.
What it means
The measure settles a long-running dispute over whether insurers could credit IVA on the repairs and replacements they buy to pay claims in kind. From 2026 they cannot, so that IVA becomes a cost of claims.
The transitional deal ran in practice from 2025: credits up to the end of 2024 are protected, but 2025 credits had to be reversed by 31 March 2026 to obtain the relief. Those deadlines have passed; only instalment plans running to 15 December 2026 remain live. The bar itself is in force for fiscal 2026 and its continuation depends on the 2027 revenue law.
Proof
no será acreditable el impuesto al valor agregado trasladado en la adquisición de bienes o prestación de servicios recibidos, ni el propio pagado en la importación, cuando dichos bienes o servicios se destinen para dar cumplimiento al contrato de seguro, y la indemnización consista en el resarcimiento de daños o la reposición del bien siniestrado, a través de terceros, conforme a la Ley Sobre el Contrato de Seguro.the value added tax charged on the acquisition of goods or services received, and the tax paid on imports, shall not be creditable when those goods or services are used to fulfil an insurance contract and the indemnity consists of compensating damage or replacing the insured property through third parties, under the Insurance Contract Law.
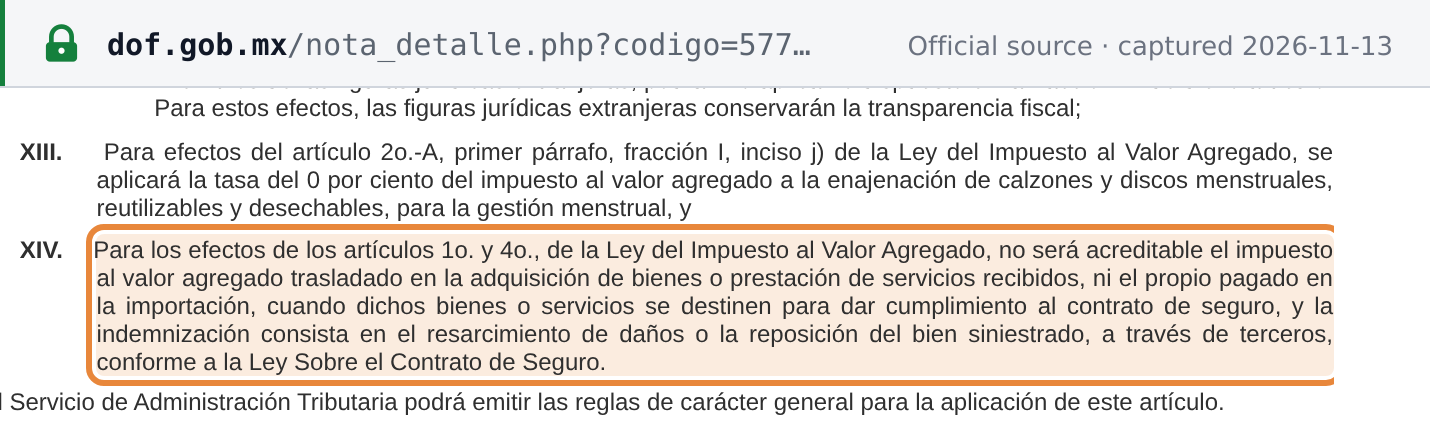 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Ley de Ingresos de la Federación para el Ejercicio Fiscal de 2026, DOF 7 de noviembre de 2025 (Cámara de Diputados text, Nueva Ley DOF 07-11-2025) · www.diputados.gob.mx