Mexico's 2026 revenue law makes crowdfunding platforms withhold 16% IVA on all interest they pay out
This page records one dated change. For the rules in Mexico as they stand today, see the Mexico guide →
- Jurisdiction
- Mexico
- Tax
- IVA
- Change type
- Compliance
- Status
- In force
- Impact
- Action required
- Announced
- 7 November 2025
- Effective
- 1 January 2026
- Instrument
- MX-LEY-DE-INGRESOS-LIF-2026
- Authority
- Diario Oficial de la Federación (DOF)
- Verified
- Fetched from official source · high confidence
Crowdfunding institutions (Instituciones de Financiamiento Colectivo) authorised under the Fintech law whose financing operations generate interest, their lenders, and the borrowers paying the interest.
From 1 January 2026, crowdfunding institutions (instituciones de financiamiento colectivo under the Ley Fintech) whose financing operations generate interest must: withhold IVA at 16% on the nominal value of accrued interest from the persons receiving it; remit it with their monthly IVA return, or by the 17th of the following month at the latest; and issue withholding CFDIs within 5 days after the month of withholding. The paying party can credit the withheld IVA under LIVA article 5o., fraction IV. When the IFC withholds, companies paying interest to individuals no longer withhold under LIVA article 1o.-A, fraction II, subsection a).
Article 25, fracción VIII of the Ley de Ingresos de la Federación para el Ejercicio Fiscal de 2026 (DOF 7 November 2025, evening edition), in force from 1 January 2026, requires crowdfunding institutions to withhold IVA at 16% on the nominal accrued interest paid through them to any recipient, in place of the recipient, and to remit it by the 17th of the following month at the latest. This replaces RMF rule 4.1.12, which covered only interest paid by companies to individuals and was not carried into the RMF for 2026. The withheld IVA is creditable for the payer, and companies paying individuals are relieved of their own withholding under LIVA article 1o.-A, fraction II, subsection a).
What changed in detail
Article 25, fraction VIII of the Ley de Ingresos de la Federación para el Ejercicio Fiscal de 2026 (DOF 7 November 2025, evening edition), in force from 1 January 2026, sets withholding duties for crowdfunding institutions regulated by the Fintech law whose financing operations generate interest. Subsection a) covers income tax; subsection b) covers IVA.
Under subsection b), the institution must withhold from the persons receiving the interest the IVA on those payments, replacing them in paying and remitting it, at 16% on the nominal value of the accrued interest. It withholds when it pays the interest and remits the tax with its IVA payment for that month or, at the latest, by the 17th of the following month, with no crediting, offset or reduction against the amount withheld.
The IVA withheld is creditable for the individual or company paying the interest under article 5o., fraction IV of the IVA law. Where a company pays interest to an individual, the company no longer has to withhold under article 1o.-A, fraction II, subsection a) of the IVA law, provided the platform withholds.
Subsection c) requires the institution to issue tax receipts (CFDIs) showing the interest paid and the income tax and IVA withheld within 5 days after the month of withholding.
What it means
This puts crowdfunding IVA withholding into statute and widens it. RMF 2024 rule 4.1.12 applied only to interest that companies paid to individuals and was framed as a facility; fraction VIII applies to every interest payment through the platform, fixes the rate, deadline and receipts, and bars netting against the withholding. The rule was not carried into the RMF for 2026, and this record supersedes the RMF 2024 rule.
The obligation is in force for fiscal 2026. As it sits in the one-year revenue law, platforms should check whether the Ley de Ingresos for 2027 repeats it.
Proof
Retener a las personas que reciban el pago de intereses y enterar, el impuesto al valor agregado que corresponda a dichos pagos, sustituyéndolas en la obligación de pago y entero del mencionado impuesto. Dicha retención deberá efectuarse aplicando la tasa del 16 por ciento sobre el valor nominal de los intereses devengados.To withhold from the persons receiving interest payments, and remit, the value added tax corresponding to those payments, substituting them in the obligation to pay and remit that tax. Such withholding must be made at the rate of 16 per cent on the nominal value of the accrued interest.
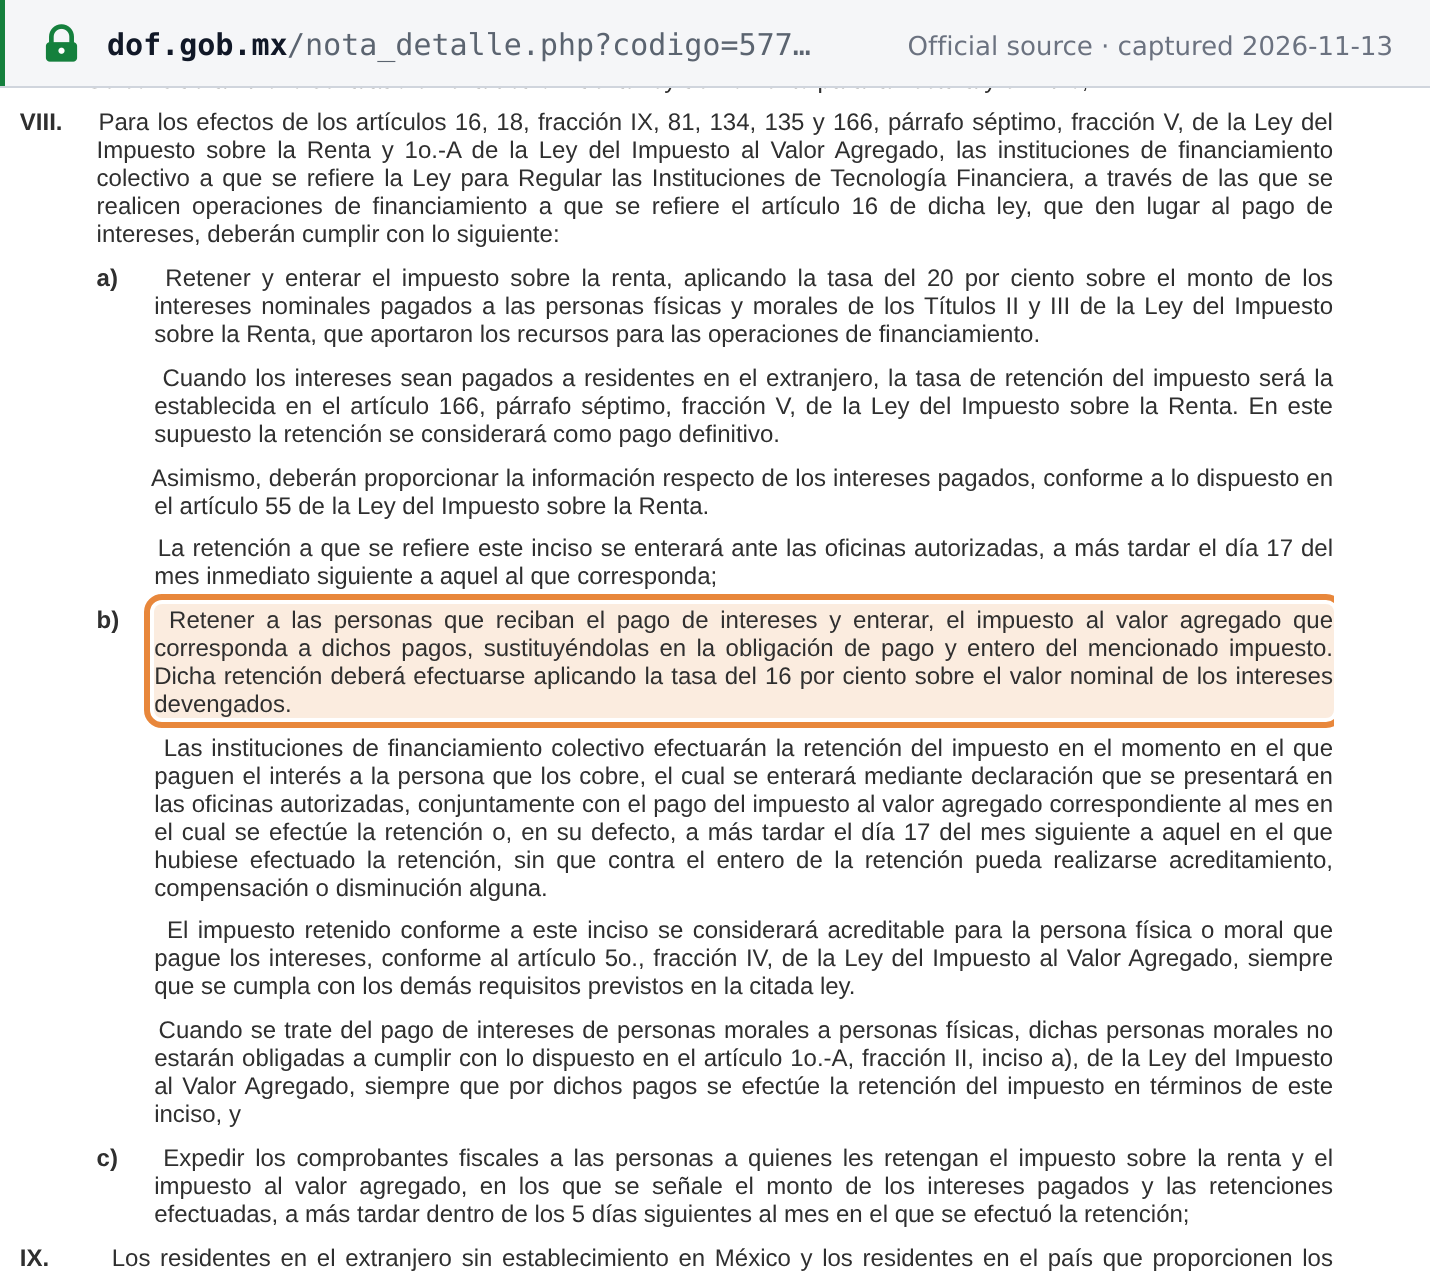 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Ley de Ingresos de la Federación para el Ejercicio Fiscal de 2026, DOF 7 de noviembre de 2025 (Cámara de Diputados text, Nueva Ley DOF 07-11-2025) · www.diputados.gob.mx
Sources
What this replaces
- Mexico makes crowdfunding platforms withhold the IVA on interest companies pay to individuals effective 12 October 2024