Mexico makes digital platforms withhold IVA from company sellers, foreign sellers and foreign-account payouts
This page records one dated change. For the rules in Mexico as they stand today, see the Mexico guide →
- Jurisdiction
- Mexico
- Tax
- IVA
- Change type
- Digital services
- Status
- In force
- Impact
- Action required
- Announced
- 7 November 2025
- Effective
- 1 January 2026
- Instrument
- MX-LEY-DE-INGRESOS-LIF-2026
- Authority
- Diario Oficial de la Federación (DOF)
- Verified
- Fetched from official source · high confidence
Resident and non-resident digital intermediation platforms (LIVA article 18-B, fraction II) that collect the price and IVA for sellers, and the companies, foreign sellers and foreign-account sellers trading through them.
Digital intermediary platforms operating in Mexico must withhold IVA from persona morales transacting through their platform, withhold 100% IVA on amounts paid to foreign sellers without a Mexican establishment, and withhold 100% IVA on amounts deposited to foreign bank or deposit accounts. Platforms must issue CFDI de retenciones to each affected person within five days after month-end.
Article 25, fracción IX of the Ley de Ingresos de la Federación para el Ejercicio Fiscal de 2026 (DOF 7 November 2025, Edición Vespertina), effective 1 January 2026, extends IVA withholding obligations for digital intermediary platforms to: (a) persona morales transacting through the platform (applying art. 18-J, frac. II, inc. a) of the Ley del IVA); (b) foreign sellers without establishment in Mexico who sell goods in territory nacional under LIVA art. 10 (100% withholding); and (c) sellers who receive payment deposits to bank or deposit accounts located abroad (100% withholding). Platforms must also issue a CFDI de retenciones e información de pagos and provide information to SAT under art. 18-J, frac. III.
What changed in detail
Article 25, fraction IX of the Ley de Ingresos de la Federación para el Ejercicio Fiscal de 2026 (DOF 7 November 2025, evening edition), in force from 1 January 2026, adds to the IVA withholding duties that article 18-J of the IVA law already places on digital intermediation platforms.
It applies to platforms, resident or non-resident without an establishment in Mexico, that provide the intermediation services of article 18-B, fraction II of the IVA law and collect the price and the IVA on behalf of the seller, service provider or lessor. Under the IVA law alone, they withhold only from individuals. From 2026 they must also:
- a) withhold IVA from companies (personas morales) selling goods, providing services or granting temporary use of goods through the platform, on the terms of article 18-J, fraction II, subsection a);
- b) withhold 100% of the IVA collected from non-residents without an establishment in Mexico selling goods in Mexican territory under article 10 of the IVA law;
- c) withhold 100% of the IVA collected from any seller, provider or lessor whose proceeds are deposited in bank or deposit accounts abroad;
- d) remit the withholding and issue each of them a CFDI de Retenciones e información de pagos under article 18-J, fraction II, subsections b) and c); and
- e) report their information under article 18-J, fraction III, with additional identification and transaction data for non-resident sellers, in terms of SAT rules.
What it means
From January 2026 marketplaces collect IVA at source from almost every seller they intermediate: individuals under the IVA law, companies at the ordinary withholding rate, and foreign sellers and foreign-account payouts in full. The first modification to RMF 2026 (DOF 9 July 2026, rule 9.1.24) later let platforms skip withholding on airlines, resident or foreign, that meet a treaty or IATA-membership condition. A platform’s onboarding has to capture each seller’s entity type, residence and payout account country, because those three facts now set the withholding rate.
Item c) takes over the 100% withholding that RMF 2024 rule 12.2.10 had imposed on payouts to foreign accounts since 1 January 2025; see the earlier rule. The obligations are in force for fiscal 2026. Because they sit in the one-year revenue law, their continuation in 2027 depends on the next Ley de Ingresos.
Proof
Los residentes en el extranjero sin establecimiento en México y los residentes en el país que proporcionen los servicios digitales a que se refiere el artículo 18-B, fracción II, de la Ley del Impuesto al Valor Agregado, cuando cobren el precio y el impuesto al valor agregado correspondiente a las operaciones de intermediación por cuenta de la persona enajenante de bienes, prestadora del servicio u otorgante del uso o goce temporal de bienes, en adición a las obligaciones establecidas en el artículo 18-J de dicha ley, deberán: a) Retener a las personas morales que enajenen bienes, presten servicios o concedan el uso o goce temporal de bienes, el impuesto al valor agregado, en términos de lo previsto en el artículo 18-J, fracción II, inciso a), párrafo primero, de la Ley del Impuesto al Valor Agregado; b) Retener el 100 por ciento del impuesto al valor agregado cobrado, tratándose de residentes en el extranjero sin establecimiento en México, que enajenen bienes en territorio nacional en términos del artículo 10 de la Ley del Impuesto al Valor Agregado; c) Retener el 100 por ciento del impuesto al valor agregado cobrado, tratándose de personas enajenantes de bienes, prestadoras de servicios u otorgantes del uso o goce temporal de bienes, cuando depositen los montos de las operaciones realizadas en cuentas bancarias o de depósito ubicadas en el extranjeroNon-residents without an establishment in Mexico and residents who provide the digital services referred to in article 18-B, fraction II of the IVA Law, when they collect the price and the IVA on intermediation transactions on behalf of the seller of goods, provider of the service or grantor of the temporary use of goods, must, in addition to the obligations under article 18-J of that law: a) withhold IVA from legal entities that sell goods, provide services or grant the temporary use of goods, under article 18-J, fraction II, subsection a), first paragraph of the IVA Law; b) withhold 100 per cent of the IVA collected from non-residents without an establishment in Mexico that sell goods in Mexican territory under article 10 of the IVA Law; c) withhold 100 per cent of the IVA collected from sellers, service providers or grantors of temporary use of goods that deposit the transaction amounts in bank or deposit accounts located abroad
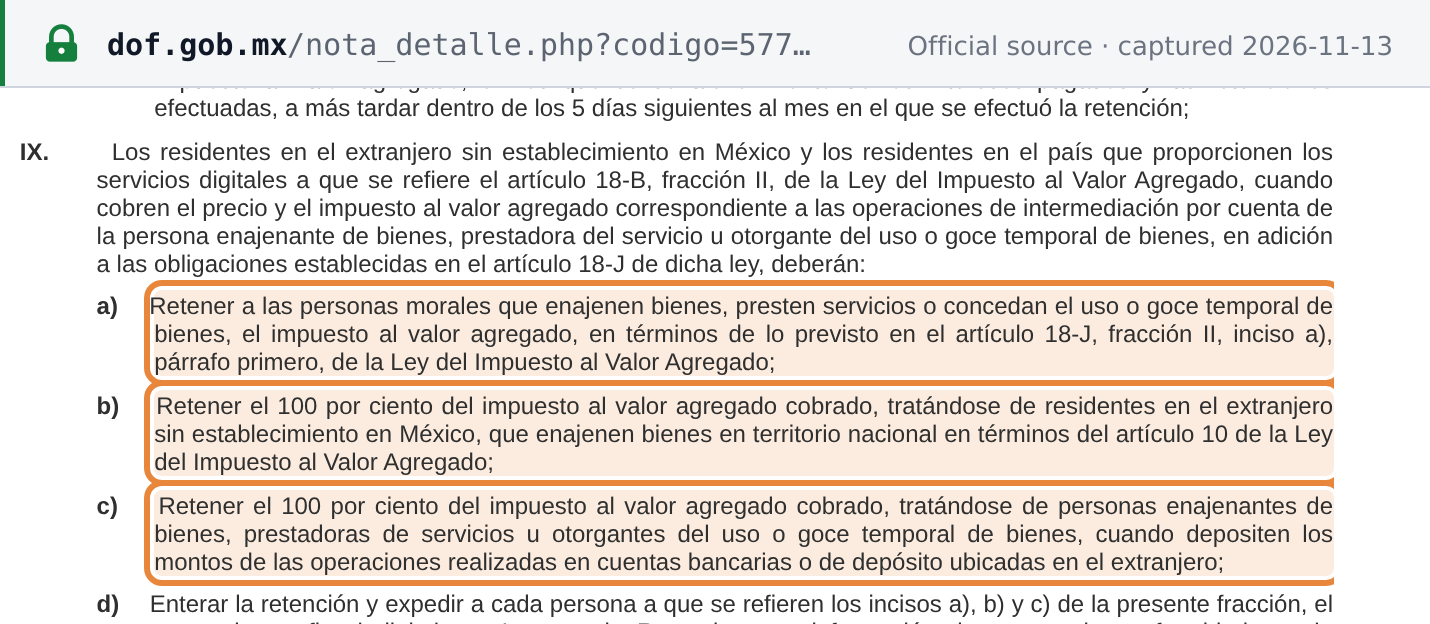 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Ley de Ingresos de la Federación para el Ejercicio Fiscal de 2026, DOF 7 de noviembre de 2025 (Cámara de Diputados text, Nueva Ley DOF 07-11-2025) · www.diputados.gob.mx