Mexico makes digital platforms withhold 100% of the IVA when they pay sellers into foreign accounts
This page records one dated change. For the rules in Mexico as they stand today, see the Mexico guide →
- Jurisdiction
- Mexico
- Tax
- IVA
- Change type
- Digital services
- Status
- In force
- Impact
- Action required
- Announced
- 11 October 2024
- Effective
- 1 January 2025
- Instrument
- MX-ADMINISTRATIVE-RESOLUTION-Segunda-Resoluci-n-de-Modificaciones-a-la-RMF-para-2024
- Authority
- Servicio de Administración Tributaria (SAT)
- Verified
- Fetched from official source · high confidence
Digital intermediation platforms, resident in Mexico or non-resident without a permanent establishment, that collect the price and IVA for sellers of goods and deposit it in bank accounts abroad.
Digital intermediation platform operators (resident in Mexico, or non-resident without a permanent establishment) that collect consideration and IVA on behalf of goods vendors and deposit those funds into bank or deposit accounts abroad must withhold 100% of the IVA from the vendor. They must remit it by the 17th of the following month and issue a CFDI de Retenciones e información de pagos with the 'Servicios Plataformas Tecnológicas' complement within five days after the month of withholding. They must also obtain from each vendor a manifestation, given via the platform's website or app or in writing, identifying the foreign accounts and their country and consenting to the withholding.
The Segunda Resolución de Modificaciones a la Resolución Miscelánea Fiscal para 2024, published in the Diario Oficial de la Federación on 11 October 2024, added new Rule 12.2.10. This rule requires digital intermediation platform operators (resident or non-resident in Mexico without a permanent establishment) that collect consideration for the sale of goods and the corresponding IVA on behalf of sellers and deposit those funds into bank accounts located abroad to withhold 100% of the IVA from the sellers. The obligation applies to intermediation platforms acting as intermediaries for goods sales where funds are deposited in foreign accounts. The resolution entered into force on 12 October 2024, but the Tercera Resolución de Modificaciones a la RMF 2024 (DOF 12 December 2024) amended its First Transitional Article so that rule 12.2.10 entered into force on 1 January 2025.
What changed in detail
The Segunda Resolución de Modificaciones a la Resolución Miscelánea Fiscal para 2024, published in the Diario Oficial de la Federación on 11 October 2024, added rule 12.2.10 to the RMF 2024. The resolution entered into force the day after publication, 12 October 2024, but the Tercera Resolución de Modificaciones (DOF 12 December 2024) amended its First Transitional Article so that rule 12.2.10 itself entered into force on 1 January 2025.
The rule applies to digital intermediation platforms, whether resident in Mexico or resident abroad without an establishment in Mexico, that collect the price and the IVA on behalf of sellers of goods and deposit those amounts in bank or deposit accounts located abroad. Such platforms must withhold 100% of the IVA on the sales they intermediate.
To do so, the platform must:
- obtain from each seller a statement, made through its website or app or in writing, identifying the foreign accounts and their country and agreeing to the withholding;
- pay the tax withheld through the IVA withholding return for technology platforms by the 17th of the following month;
- issue the seller a CFDI de Retenciones e información de pagos with the “Servicios Plataformas Tecnológicas” complement within five days after the month of withholding; and
- report the operations to the SAT under article 18-J of the IVA law.
Sellers may credit the IVA withheld against their tax for the month.
What it means
The rule is aimed at marketplace sellers whose proceeds leave Mexico. When sales are paid out to foreign accounts, the platform now collects the whole of the IVA at source rather than relying on the seller to pay the balance.
The RMF 2025 carried rule 12.2.10 forward in full. For 2026 the 100% withholding moved into the Ley de Ingresos de la Federación 2026 (article 25, section IX, item c), and RMF 2026 rule 12.2.10 now covers only the seller’s declaration of its foreign accounts. The obligation is still in force; cite the LIF 2026 provision, not the 2024 rule, for current periods.
Proof
las plataformas digitales de intermediación entre terceros, residentes en el extranjero sin establecimiento en México y aquellas residentes en el país, que cobren por cuenta del oferente de bienes las contraprestaciones y el IVA correspondiente y depositen en cuentas bancarias o de depósito ubicadas en el extranjero dichas contraprestaciones, deberán retener a los oferentes de los bienes el 100% del IVA correspondiente a las enajenaciones en las que actúen como intermediarios.digital platforms intermediating between third parties, whether resident abroad without an establishment in Mexico or resident in the country, that collect the consideration and the corresponding IVA on behalf of the seller of goods and deposit that consideration in bank or deposit accounts located abroad, must withhold from the sellers of the goods 100% of the IVA on the sales in which they act as intermediaries.
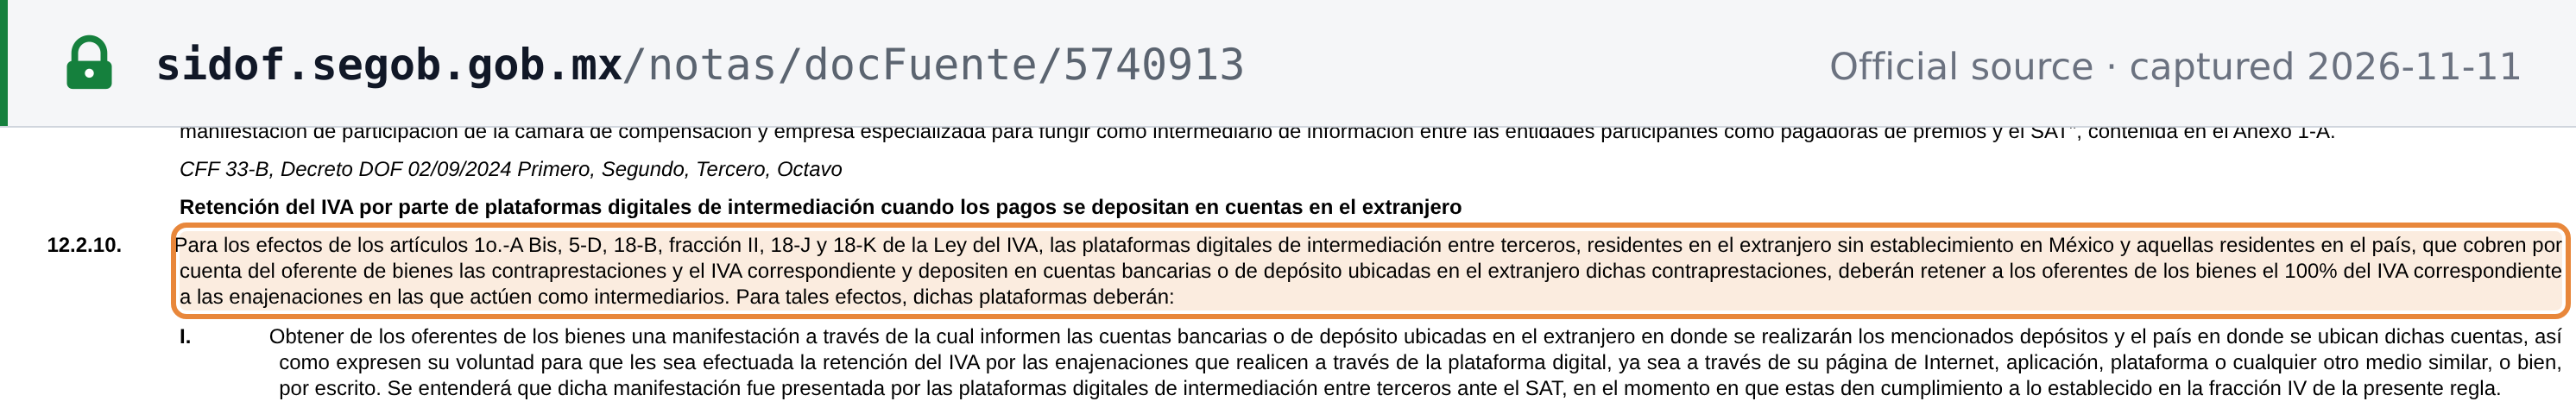 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Segunda Resolución de Modificaciones a la Resolución Miscelánea Fiscal para 2024, DOF 11 de octubre de 2024 (SIDOF nota 5740913) · sidof.segob.gob.mx