Mexico requires digital service platforms to give the SAT online access to their transaction data
This page records one dated change. For the rules in Mexico as they stand today, see the Mexico guide →
- Jurisdiction
- Mexico
- Tax
- IVA
- Change type
- Digital services
- Status
- In force
- Impact
- Action required
- Announced
- 28 December 2025
- Effective
- 1 January 2026
- Instrument
- MX-ADMINISTRATIVE-RESOLUTION-Resoluci-n-Miscel-nea-Fiscal-para-2026
- Authority
- Servicio de Administración Tributaria (SAT)
- Verified
- Fetched from official source · high confidence
Resident and non-resident providers of digital services to recipients in Mexico under articles 1o.-A BIS and 18-B of the IVA law, including intermediation platforms.
Digital platform operators providing digital services under IVA articles 1o.-A BIS and 18-B must maintain transaction data (by next business day, stored for 5 years) accessible online to the SAT, and provide the SAT with login credentials and access guides by filing an escrito libre with the Administración General de Planeación no later than 30 April 2026. Platforms starting operations after that date must file within one month of commencing digital services.
New Rule 2.9.21 of the Resolución Miscelánea Fiscal para 2026 (published in the Diario Oficial de la Federación on 28 December 2025, effective 1 January 2026), issued pursuant to article 30-B of the Código Fiscal de la Federación (CFF), requires digital platform operators that supply digital services under IVA articles 1o.-A BIS and 18-B to maintain detailed per-transaction data (service type, RFC of customer, amounts, IVA, IEPS, ISR, and payment methods) in a database accessible online to the SAT at any time, with data stored for five years. Platforms must provide the SAT with user credentials and access guides via an escrito libre at the Administración General de Planeación by no later than 30 April 2026.
What changed in detail
Rule 2.9.21 of the Resolución Miscelánea Fiscal para 2026, published in the Diario Oficial de la Federación on 28 December 2025 and effective 1 January 2026, implements article 30-B of the Código Fiscal de la Federación. It requires taxpayers that provide digital services under articles 1o.-A BIS and 18-B of the IVA law to give the tax authority online access to set information.
For each service supplied to recipients in Mexico, the data include the type of service, the customer’s RFC where a CFDI is requested, the price without IVA, the IVA charged, the final price, the CFDI folio and the payment method. Intermediation platforms must also give details of each seller or provider: name, RFC or tax ID, address or residence, bank account, the amounts of each operation for ISR, IVA and IEPS, and the ISR, IVA and IEPS withheld.
The data must be loaded by the next day, transaction by transaction, in a database that can be queried individually and in bulk, and kept available for five years. Platforms must give the SAT a username, password and access guides by filing an escrito libre with the Administración General de Planeación by 30 April 2026. A platform that starts operating later files in the month after it starts, and any change to the access details must be notified within ten days.
What it means
The 30 April 2026 deadline has passed, and the obligation is now continuous. In-scope platforms must keep the SAT’s access working and the data current every day.
This is a step beyond periodic reporting: the SAT can look at transaction-level data whenever it chooses. Platforms need a reporting environment the SAT can query, and data that reconciles with their CFDI and withholding returns, because the authority can now compare them directly.
Proof
Para los efectos del artículo 30-B, primer párrafo del CFF, los contribuyentes que proporcionen servicios digitales de conformidad con los artículos 1o.-A BIS y 18-B de la Ley del IVA, deberán permitir a la autoridad fiscal el acceso en línea, exclusivamente, a la información que a continuación se señalaFor the purposes of article 30-B, first paragraph, of the CFF, taxpayers that provide digital services under articles 1o.-A BIS and 18-B of the IVA Law must allow the tax authority online access, exclusively, to the information set out below
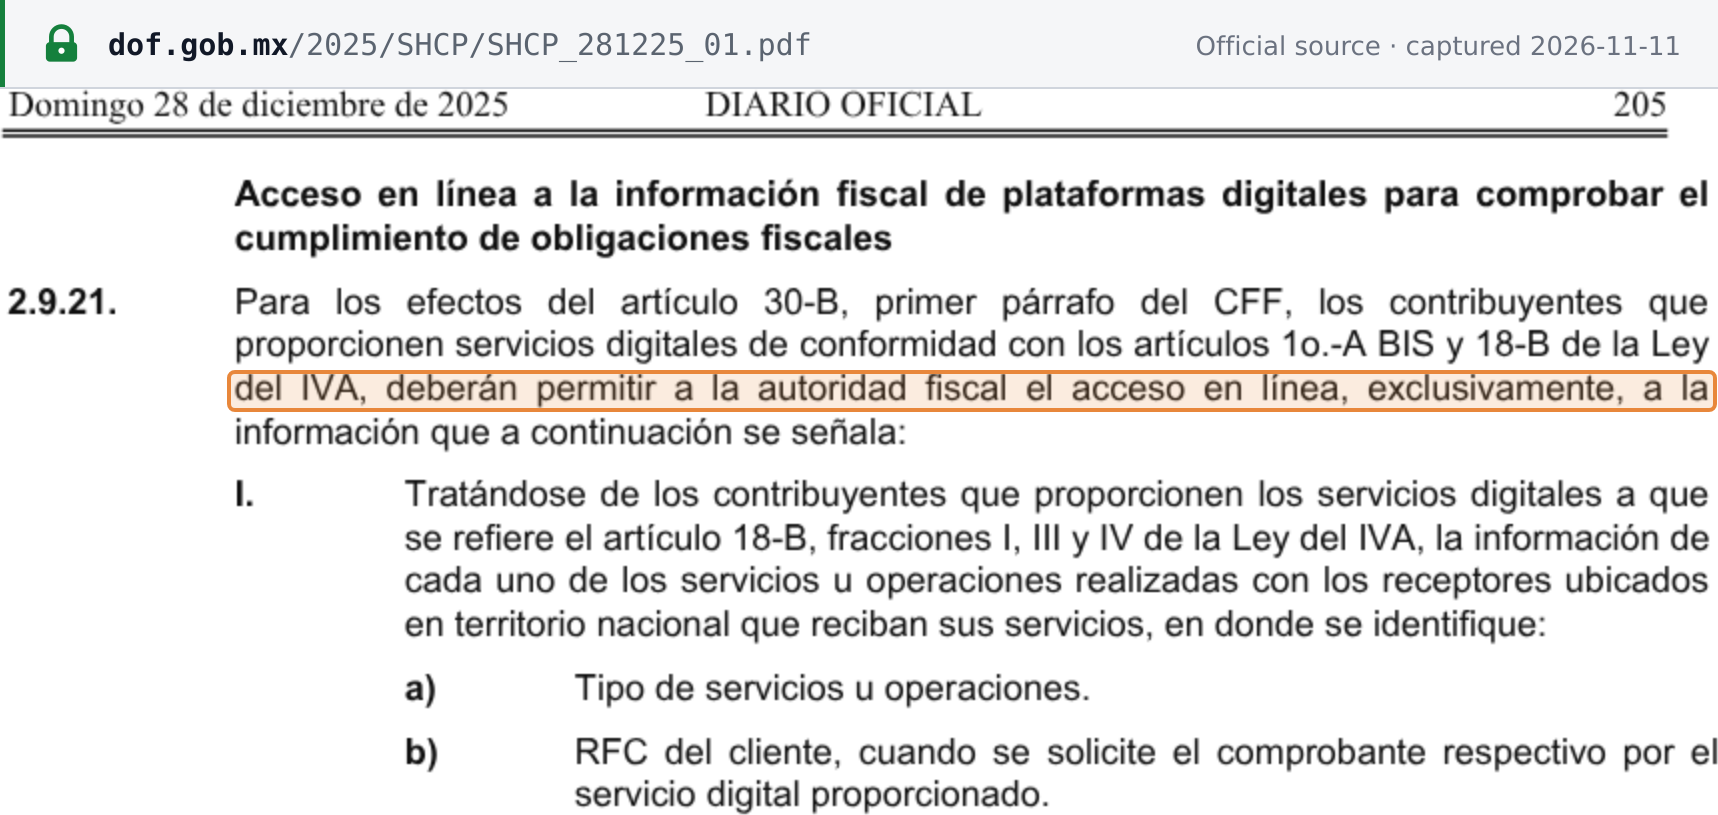 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Resolución Miscelánea Fiscal para 2026, Diario Oficial de la Federación, 28 de diciembre de 2025 · dof.gob.mx