Netherlands enacts a move of culture, sport, media, books and accommodation from 9% to 21% VAT from 2026 (Belastingplan 2025)
This page records one dated change. For the rules in Netherlands as they stand today, see the Netherlands guide →
- Jurisdiction
- Netherlands
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 18 December 2024
- Effective
- 1 January 2026
- Instrument
- NL-ACT-Stb-2024-434
- Authority
- Staatsblad van het Koninkrijk der Nederlanden
- Verified
- Fetched from official source · high confidence
Suppliers of books, art objects, cultural services, cinema, sport, media and accommodation in the Netherlands that charged the 9% reduced rate.
No action — superseded before its effective date except for accommodation (see nl-accommodation-vat-21-2024 and nl-culture-sport-vat-reversal-2025).
The Belastingplan 2025 (Wet van 18 december 2024, Stb. 2024, 434, published 23 December 2024) provided, in article XXI part B, that with effect from 1 January 2026 a number of items would be deleted from Tabel I of the Wet op de omzetbelasting 1968 (Table I, part a, items 29 and 30, and part b, items 2, 3, 11, 14(c), (d) and (f), 17 and 21), moving them from the 9% reduced rate to the 21% standard rate. The items covered books and art objects, cultural services, cinema, sport, media and accommodation. Except for accommodation, this increase never took effect: the Wet behoud verlaagd btw-tarief op cultuur, media en sport (Stb. 2025, 339) narrowed the deletion to accommodation (part b, item 11) before 1 January 2026.
What changed in detail
The Belastingplan 2025 (Wet van 18 december 2024) was published in the Staatsblad on 23 December 2024 as Stb. 2024, 434. Its article XXI amends the Wet op de omzetbelasting 1968 “met ingang van 1 januari 2026” (with effect from 1 January 2026).
Article XXI, part B, deletes a set of items from Tabel I, the list of supplies taxed at the 9% reduced rate: part a, items 29 and 30, and part b, items 2, 3, 11, 14(c), (d) and (f), 17 and 21. Deleted items fall to the 21% standard rate. The items covered books and art objects, cultural services, cinema, sport, media and accommodation.
Article LXII sets a transitional rule: for supplies whose rate rises under article XXI part B, VAT on supplies performed after 1 January 2026 is calculated at the rate in force when the supply is performed.
This is the law as first enacted. Before 1 January 2026, the Wet behoud verlaagd btw-tarief op cultuur, media en sport (Wet van 29 oktober 2025, Stb. 2025, 339) rewrote article XXI part B so that it deletes only part b, item 11 (accommodation).
What it means
This record is superseded. Except for accommodation, the increase never took effect: the Wet behoud verlaagd btw-tarief op cultuur, media en sport narrowed the deletion before its start date, so books, culture, sport and media stayed at 9% on 1 January 2026 and remain there. Do not read this page as the current rate for those supplies.
Only the accommodation part survived. Accommodation (logies) has been taxed at 21% since 1 January 2026; see the accommodation record. Systems that were configured in 2025 to move cultural or sports supplies to 21% from 2026 should have been reverted.
Proof
In tabel I, vervallen, onderdeel a, posten 29 en 30, en onderdeel b, posten 2, 3, 11, 14, onder c, d en f, 17 en 21.In table I, part a, items 29 and 30, and part b, items 2, 3, 11, 14(c), (d) and (f), 17 and 21 are deleted.
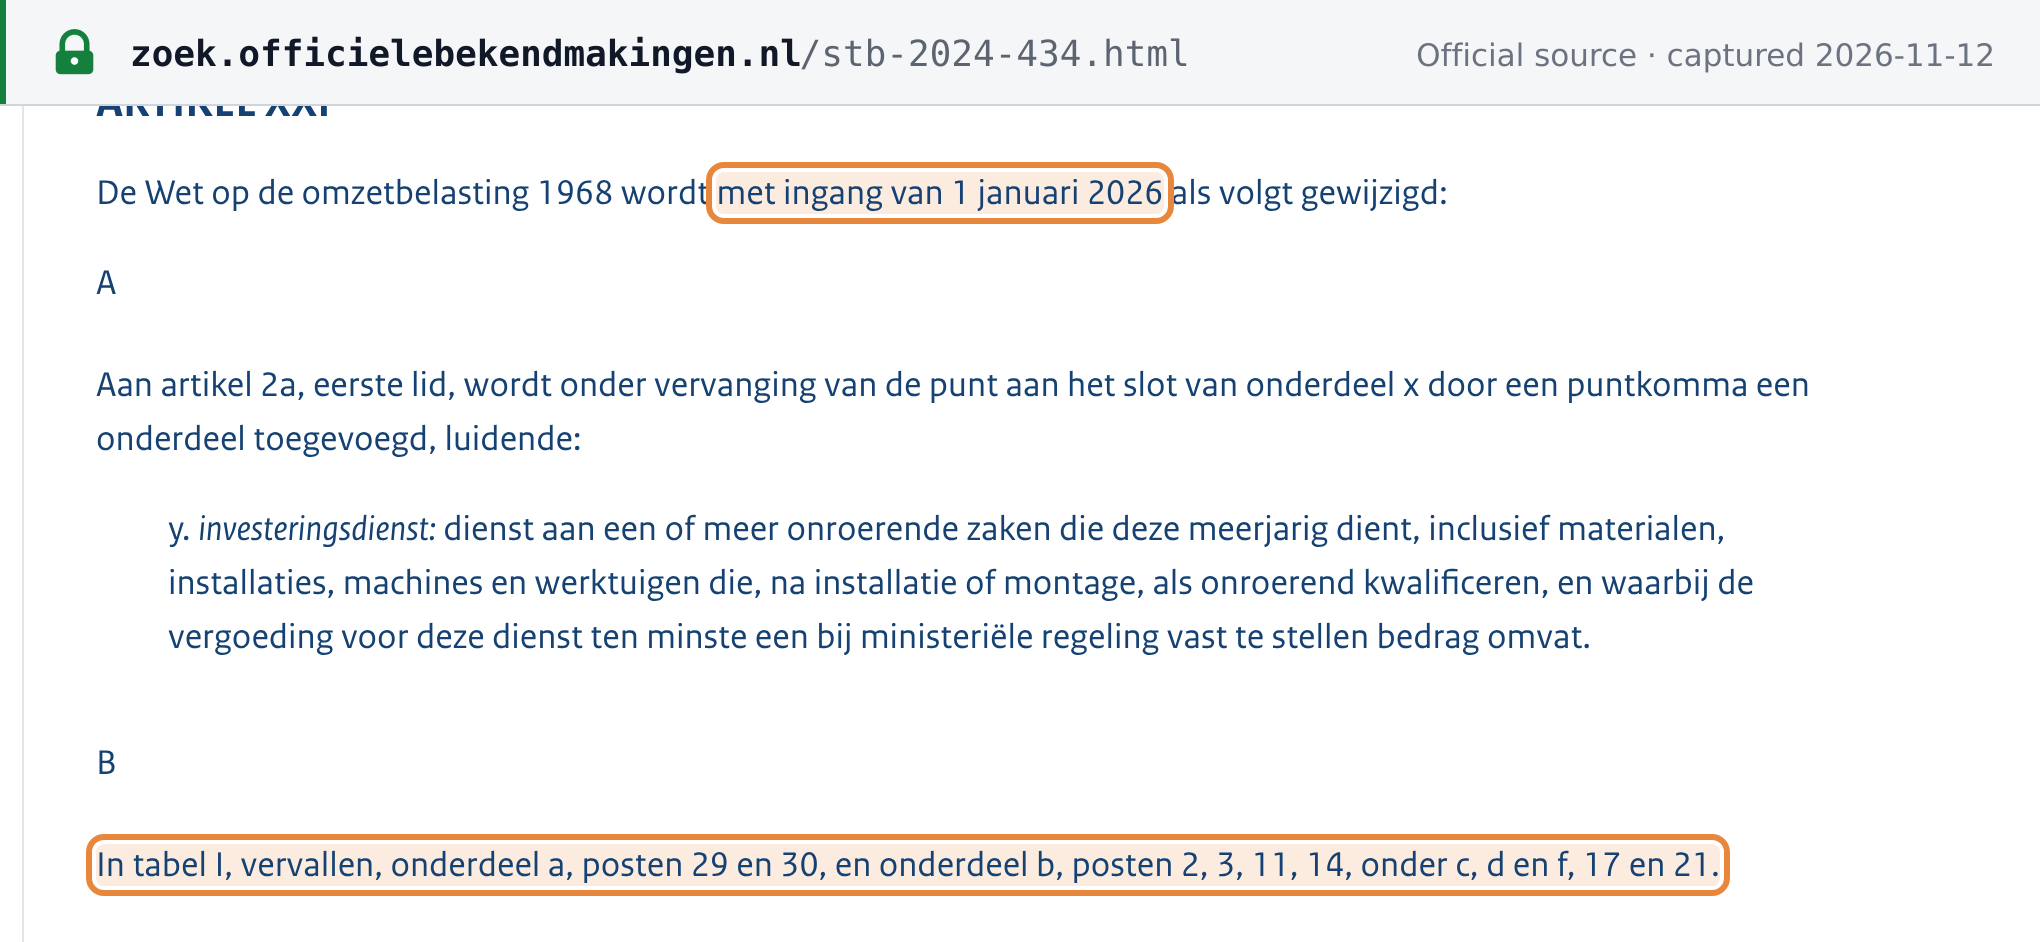 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Staatsblad 2024, 434 (authentic PDF): Wet van 18 december 2024 (Belastingplan 2025), published 23 December 2024 · repository.overheid.nl