Netherlands raises VAT on accommodation (logies) from 9% to 21% from 1 January 2026
This page records one dated change. For the rules in Netherlands as they stand today, see the Netherlands guide →
- Jurisdiction
- Netherlands
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 18 December 2024
- Effective
- 1 January 2026
- Authority
- Staatsblad van het Koninkrijk der Nederlanden
- Verified
- Fetched from official source · high confidence
Businesses providing accommodation (logies) in the Netherlands, and the platforms and intermediaries that price or invoice it.
No action — monitoring only.
In force from 1 January 2026. The VAT rate on the provision of accommodation (logies, Tabel I part b item 11 of the Wet op de omzetbelasting 1968) rose from the 9% reduced rate to the 21% standard rate. The increase was enacted in the Belastingplan 2025 (Wet van 18 december 2024, Stb. 2024, 434, article XXI part B), and the Wet behoud verlaagd btw-tarief op cultuur, media en sport (Stb. 2025, 339) left it as the only surviving deletion from Table I. Article LXII of the Belastingplan 2025 sets the transitional rule: the rate at the time the supply is performed applies to supplies after 1 January 2026.
What changed in detail
From 1 January 2026 the provision of accommodation (logies, Tabel I, part b, item 11 of the Wet op de omzetbelasting 1968) is no longer on the list of supplies taxed at the 9% reduced rate, so it is taxed at the 21% standard rate.
The increase was enacted in the Belastingplan 2025 (Wet van 18 december 2024, Stb. 2024, 434), whose article XXI, part B, deleted item 11 together with several cultural, sport, media and book items with effect from 1 January 2026. The Wet behoud verlaagd btw-tarief op cultuur, media en sport (Wet van 29 oktober 2025, Stb. 2025, 339) then rewrote article XXI, part B, to read: “In tabel I vervalt onderdeel b, post 11.” Accommodation is therefore the only deletion from Tabel I that took effect.
Article LXII of the Belastingplan 2025 sets the transitional rule: VAT on supplies performed after 1 January 2026 is calculated at the rate in force when the supply is performed. The preamble of Stb. 2025, 339 states that this transitional rule applies only to the provision of accommodation.
What it means
The 21% rate on accommodation has applied since 1 January 2026 and is still in force in November 2026. Because the rate follows the date the stay is performed, bookings made and paid in 2025 for stays in 2026 fall under 21%, which affects prices quoted before the change.
The rest of the 2024 package did not happen: books, culture, media and sport stayed at 9% after the 2025 reversal, which superseded the original Belastingplan 2025 deletion. Treat any source that lists those supplies at 21% from 2026 as out of date.
Proof
In het Belastingplan 2025 komt artikel XXI, onderdeel B, te luiden: B In tabel I vervalt onderdeel b, post 11.In the Belastingplan 2025, article XXI, part B, shall read: B In table I, part b, item 11 is deleted.
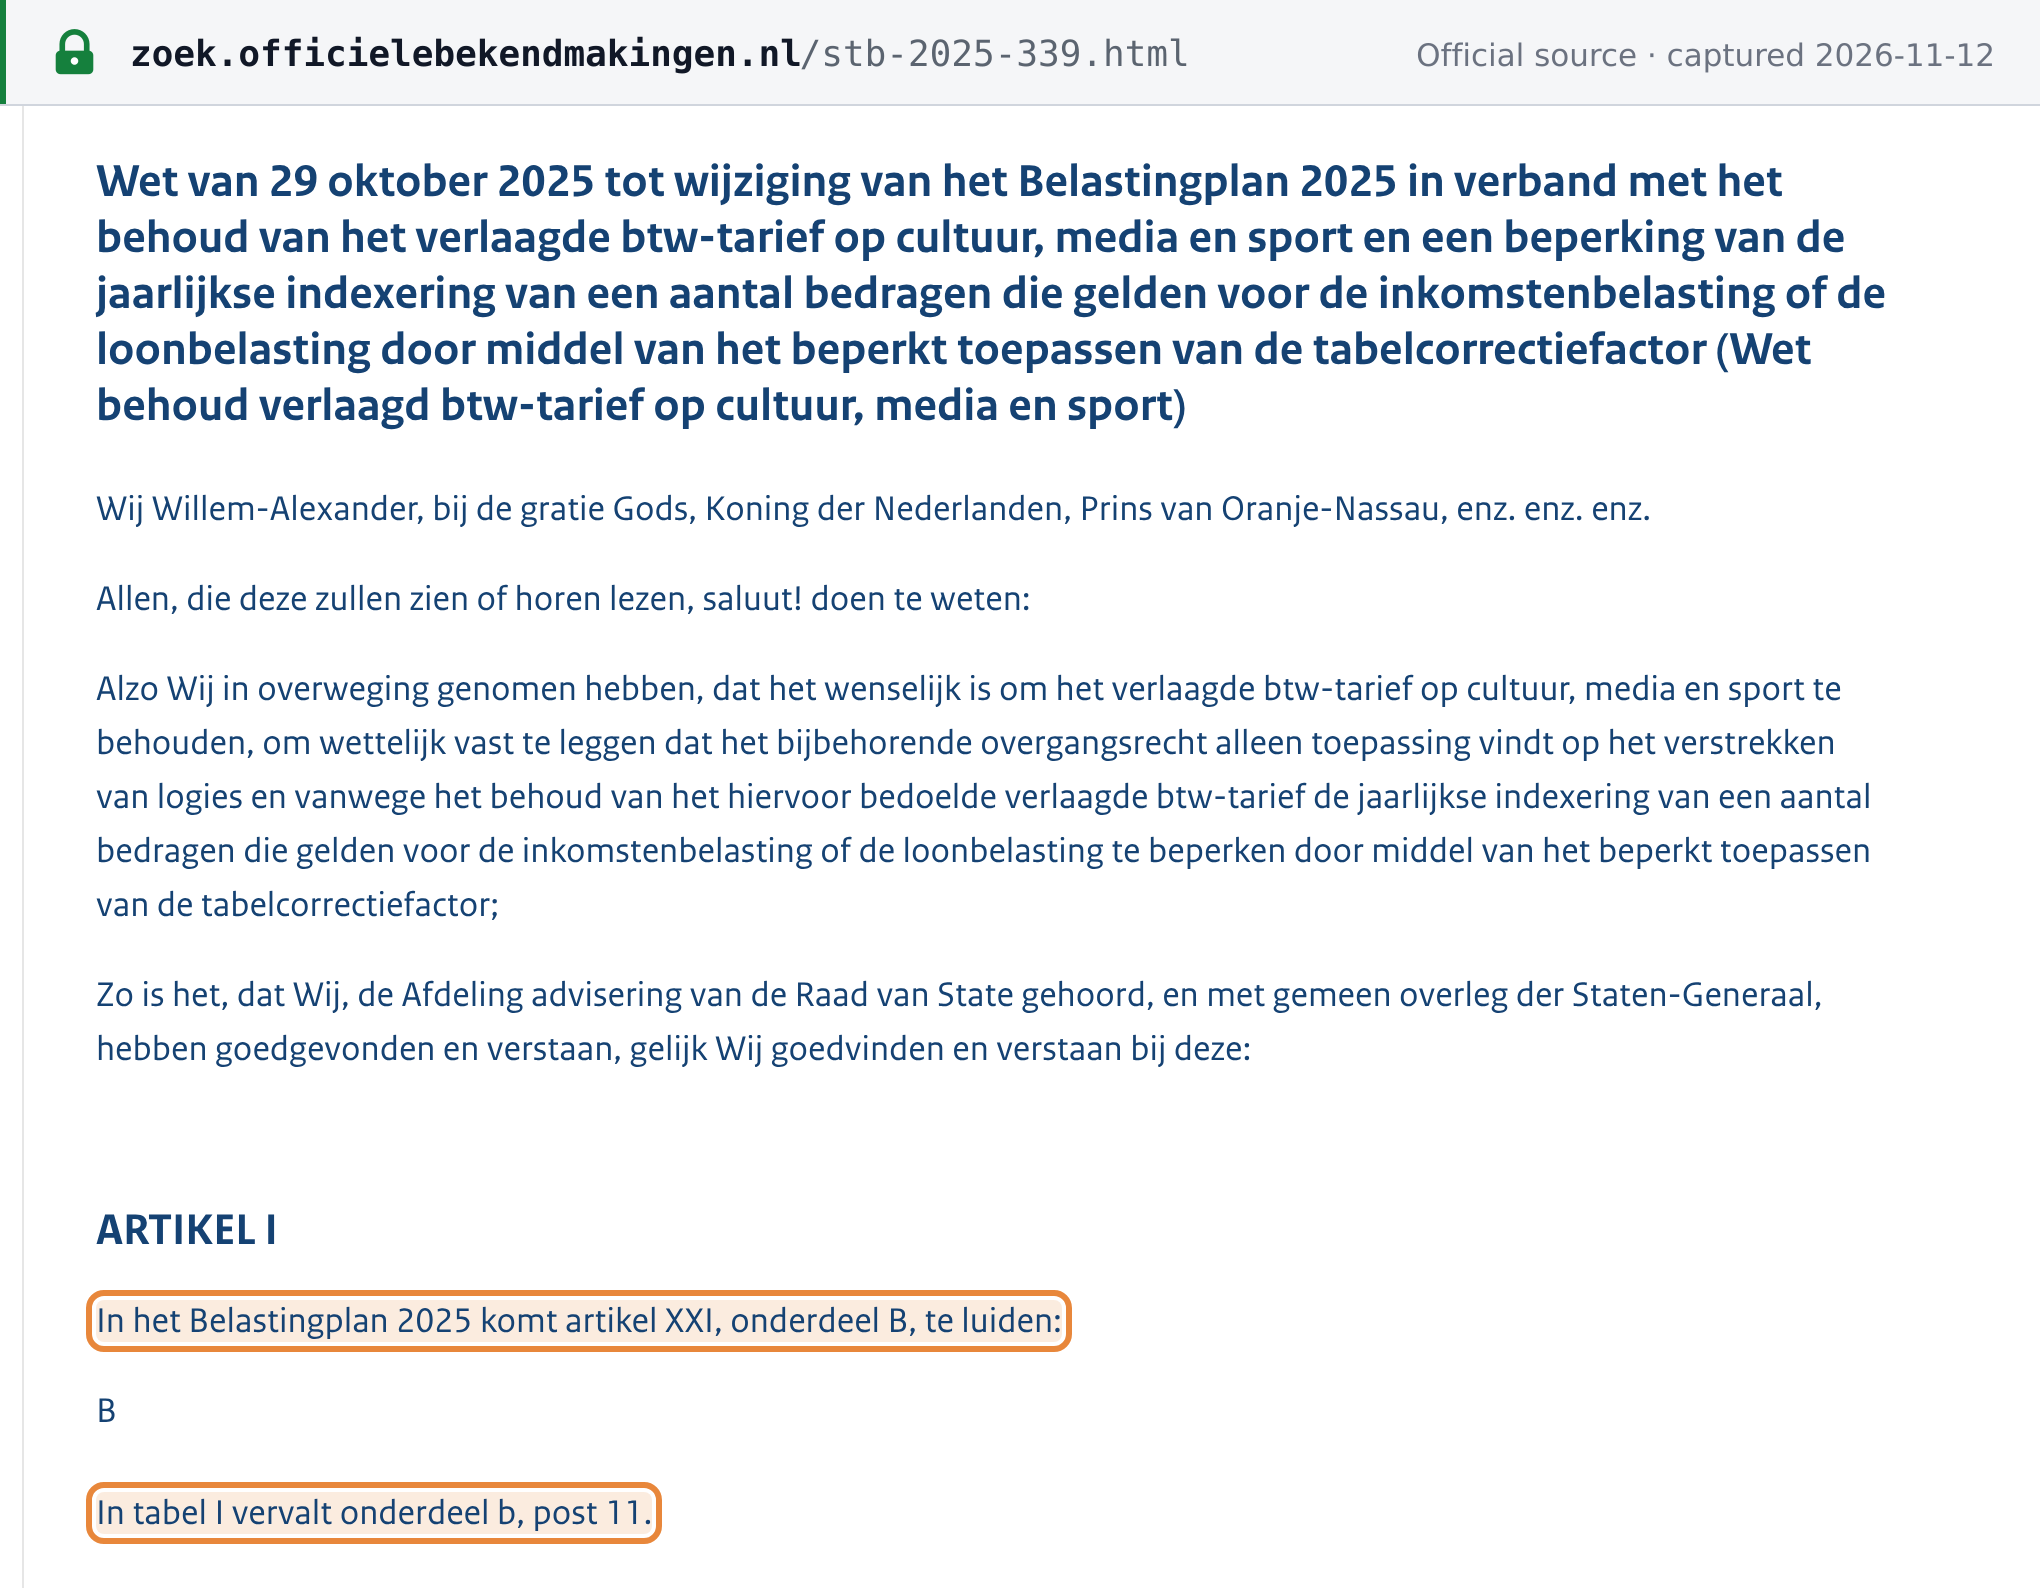 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Staatsblad 2025, 339 (authentic PDF): Wet van 29 oktober 2025 (Wet behoud verlaagd btw-tarief op cultuur, media en sport), published 11 November 2025 · repository.overheid.nl