Netherlands opens its small-business VAT exemption (KOR) to EU businesses from 1 January 2025
This page records one dated change. For the rules in Netherlands as they stand today, see the Netherlands guide →
- Jurisdiction
- Netherlands
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- FYI
- Announced
- 1 January 2025
- Effective
- 1 January 2025
- Instrument
- NL-ACT-Stb-2023-278
- Authority
- Staatsblad van het Koninkrijk der Nederlanden
- Verified
- Fetched from official source · high confidence
Dutch-established entrepreneurs with Dutch turnover up to EUR 20,000; entrepreneurs established elsewhere in the EU with Dutch turnover up to EUR 20,000 and EU-wide turnover up to EUR 100,000.
No action — monitoring only.
In force from 1 January 2025. The Wet implementatie Richtlijn kleineondernemersregeling (Wet van 10 juli 2023, Stb. 2023, 278, published 14 August 2023) implements Directive (EU) 2020/285 by amending the Wet op de omzetbelasting 1968. Dutch-established entrepreneurs whose annual turnover in the Netherlands does not exceed EUR 20,000 may opt for the small-business exemption (KOR); entrepreneurs established elsewhere in the EU may use it in the Netherlands if, in addition, their annual EU-wide turnover does not exceed EUR 100,000. Dutch entrepreneurs using the cross-border scheme must report their turnover per Member State within one month after each calendar quarter. The exemption now runs until the entrepreneur withdraws; after withdrawal it cannot be applied again until the end of the following calendar year (replacing the former three-year minimum period). Notification for the 2025 domestic KOR could be made from 1 October 2024.
What changed in detail
The Wet implementatie Richtlijn kleineondernemersregeling (Wet van 10 juli 2023, Stb. 2023, 278, published 14 August 2023) rewrites the small-business scheme (kleineondernemersregeling, KOR) in the Wet op de omzetbelasting 1968 to implement Council Directive (EU) 2020/285. Its main provisions apply from 1 January 2025; article II applied from 1 October 2024, so notification for the 2025 domestic KOR could be made from that date.
Under the new article 25a:
- an entrepreneur established in the Netherlands whose annual Dutch turnover does not exceed EUR 20,000 may opt for exemption on its Dutch supplies;
- an entrepreneur established elsewhere in the EU may use the exemption in the Netherlands if, in addition, its annual EU-wide turnover does not exceed EUR 100,000;
- an entrepreneur using the exemption has no right to deduct input VAT and may not show VAT on its invoices.
Dutch entrepreneurs using the cross-border scheme in other Member States must report their turnover per Member State within one month after each calendar quarter.
The exemption now runs until the entrepreneur withdraws. Under article 25a(7), after withdrawal it cannot be applied again until the calendar year of withdrawal and the following calendar year have ended. This replaces the former three-year minimum period.
What it means
The scheme has been in force since 1 January 2025 and still applies in November 2026. The EUR 20,000 domestic threshold is unchanged; what changed is who can use it and how it ends.
For EU businesses, the Netherlands is now reachable without Dutch VAT registration if both turnover tests are met, through the home-state notification and EX-number process. For Dutch businesses, the three-year minimum stay became a re-entry bar: after withdrawing you cannot rejoin until both the year you left and the following calendar year have ended (article 25a(7)). Businesses close to EUR 20,000 should plan withdrawals with that in mind.
Proof
Een ondernemer die in Nederland is gevestigd en van wie de jaaromzet in Nederland niet meer bedraagt dan € 20.000 kan kiezen voor toepassing van vrijstelling van belastingAn entrepreneur established in the Netherlands whose annual turnover in the Netherlands does not exceed EUR 20,000 may opt for exemption from tax
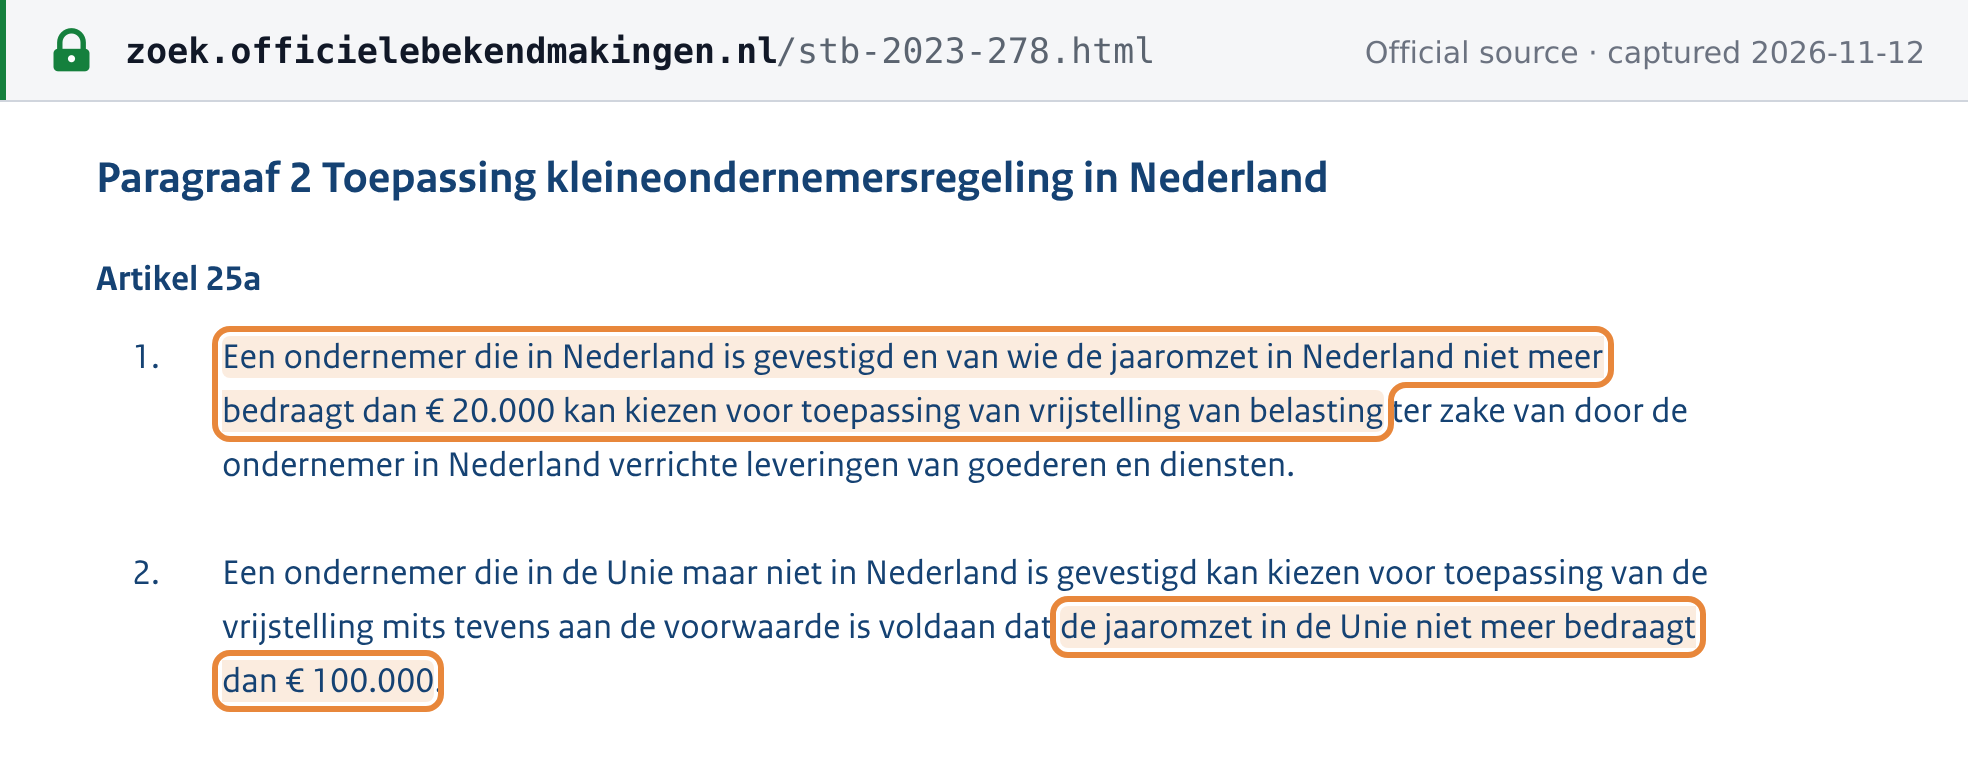 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Staatsblad 2023, 278 (authentic PDF): Wet van 10 juli 2023 (Wet implementatie Richtlijn kleineondernemersregeling), published 14 August 2023 · repository.overheid.nl