Poland lists the six cases exempt from issuing KSeF structured invoices from 1 February 2026
This page records one dated change. For the rules in Poland as they stand today, see the Poland guide →
- Jurisdiction
- Poland
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- Plan ahead
- Announced
- 9 December 2025
- Effective
- 1 February 2026
- Instrument
- PL-MINISTERIAL-REGULATION-DU-2025-1740
- Authority
- Dziennik Ustaw Rzeczypospolitej Polskiej
- Verified
- Fetched from official source · high confidence
Motorway operators, passenger carriers, EUROCONTROL's CRCO, providers of exempt financial and insurance services on reduced-data invoices, and businesses self-billing where a party has no Polish NIP.
Businesses in the listed categories (motorway tolls, passenger tickets, EUROCONTROL route charges, exempt financial/insurance services on simplified invoices, self-billing where a party has no NIP) need not issue those invoices in KSeF; all other invoices fall under the KSeF mandate.
Rozporządzenie Ministra Finansów i Gospodarki z dnia 7 grudnia 2025 r. (Dz.U. 2025 poz. 1740), issued under Art. 106s of the Polish VAT Act and in force from 1 February 2026, specifies the cases in which there is no obligation to issue structured invoices (faktury ustrukturyzowane) in the KSeF system. Exempt from the structured-invoice obligation are: (1) paid-motorway toll services documented by reduced-data invoices; (2) passenger-transport services on any distance (rail, road, sea, inland waterway, ferry, air) documented by single-use tickets; (3) EUROCONTROL route-charge invoices issued by CRCO for the Polish Air Navigation Services Agency; (4) supplies exempt under Art. 43(1)(7) and (37)–(41) (financial and insurance services) documented by reduced-data invoices; (5) self-billed invoices where the buyer is not identified by NIP for the transaction; (6) self-billed invoices where the authorising supplier is not identified by NIP. These exemptions determine the operational scope of the KSeF mandate. Relates to pl-ksef-enabling-law-2025 (Dz.U. 2025 poz. 1203).
What changed in detail
The Minister of Finance and Economy regulation of 7 December 2025 (Dz.U. 2025 poz. 1740), issued under art. 106s of the VAT Act, was published on 9 December 2025 and is in force from 1 February 2026. Under § 2, there is no obligation to issue a structured invoice in KSeF for:
- paid-motorway toll services documented by reduced-data invoices;
- passenger transport over any distance, by rail, road, sea, inland and coastal waterway, ferry, plane or helicopter, documented by single-use tickets that serve as reduced-data invoices;
- air-traffic route charges invoiced monthly by EUROCONTROL’s Central Route Charges Office (CRCO) on behalf of the Polish Air Navigation Services Agency;
- services exempt under art. 43(1)(7) and (37)–(41), the financial and insurance exemptions, documented by reduced-data invoices;
- self-billed invoices where the buyer issuing them is not identified for the transaction by a Polish NIP;
- self-billed invoices where the supplier that authorised the buyer is not identified by a NIP.
Under § 3, structured invoices may still be issued voluntarily in case 5 for an intra-Community supply where the self-billing buyer is identified in another Member State.
What it means
This regulation is in force and has not been amended. It sets the outer edge of the KSeF mandate created by the 2025 KSeF Act, which went live on 1 February 2026 for the largest taxpayers and on 1 April 2026 for the rest.
Every exception is tied to a document type or a missing NIP, not to a sector as a whole. A motorway operator or a bank still issues structured invoices for anything not documented by a reduced-data invoice. Businesses in these sectors should map which invoice flows fall inside § 2 rather than assume they are out of scope.
Proof
§ 2. Obowiązku wystawiania faktur ustrukturyzowanych nie ma w przypadku: 1) świadczenia usług przejazdu autostradą płatną, udokumentowanych fakturami zawierającymi zakres danych węższy niż określony w art. 106e ustawy z dnia 11 marca 2004 r. o podatku od towarów i usług, zwanej dalej „ustawą”§ 2. There is no obligation to issue structured invoices in the case of: 1) paid-motorway transit services documented by invoices containing a narrower set of data than specified in Art. 106e of the Act of 11 March 2004 on goods and services tax ("the Act")
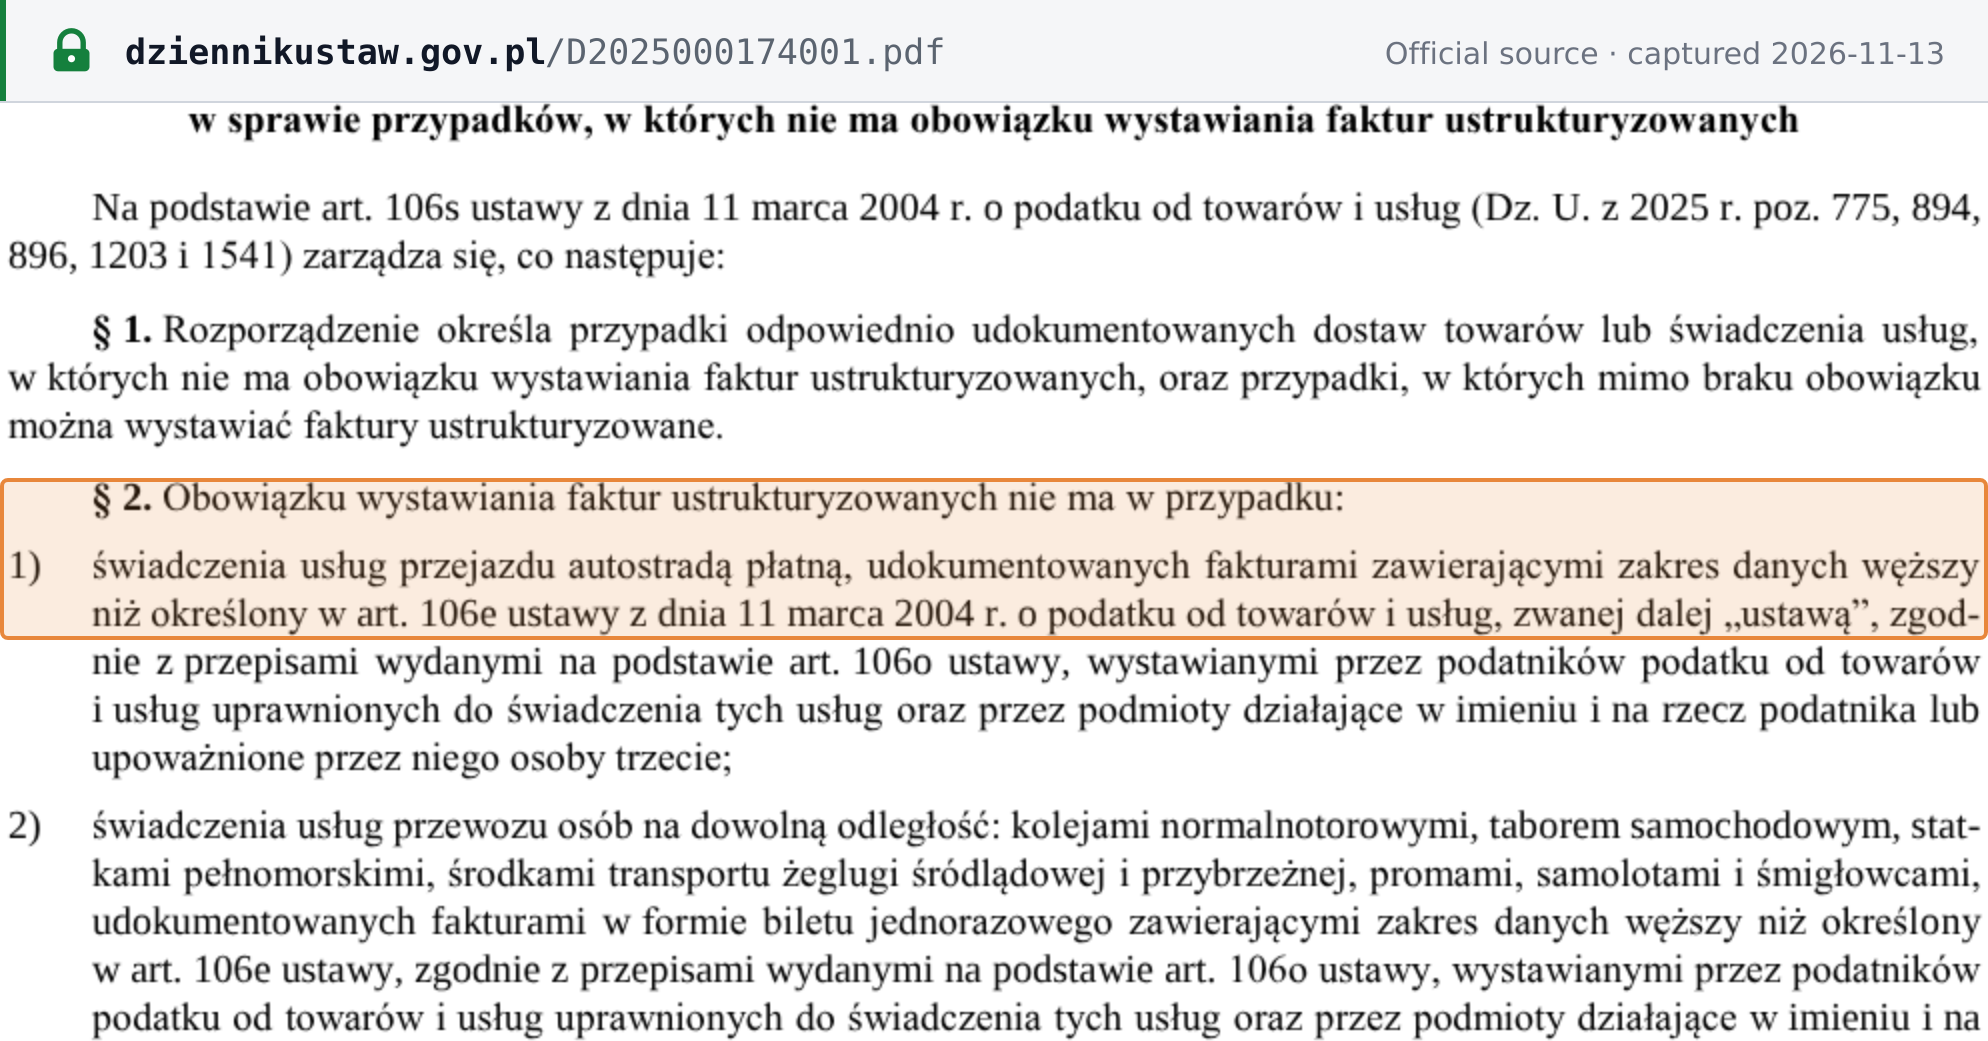 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Dz.U. 2025 poz. 1740 · Rozporządzenie Ministra Finansów i Gospodarki z dnia 7 grudnia 2025 r. · dziennikustaw.gov.pl