Romania raises the small-business VAT exemption threshold to RON 395,000 from 1 September 2025
- Jurisdiction
- Romania
- Tax
- VAT
- Change type
- Threshold
- Status
- In force
- Impact
- FYI
- Announced
- 29 August 2025
- Effective
- 1 September 2025
- Instrument
- RO-ORDINANCE-22-2025
- Authority
- Agenția Națională de Administrare Fiscală (ANAF)
- Verified
- Fetched from official source · high confidence
Taxable persons established in Romania with annual turnover up to RON 395,000, and EU-established small businesses using the cross-border SME scheme in Romania.
No action — monitoring only.
OG 22/2025 (Monitorul Oficial nr. 806 of 29 August 2025) raised the Romanian VAT registration exemption (special small business scheme) threshold from RON 300,000 to RON 395,000, effective 1 September 2025. It also transposed EU Directive 2020/285 for cross-border SME scheme eligibility.
What changed in detail
Government Ordinance (OG) 22/2025 of 28 August 2025, published in Monitorul Oficial nr. 806 of 29 August 2025, amends the Fiscal Code (Law 227/2015) and, under its art. II, applies from 1 September 2025.
The new art. 310(1) lets a taxable person established in Romania whose annual turnover, declared or achieved, does not exceed RON 395,000 apply the special exemption scheme to its supplies, except intra-Community supplies of new means of transport. The previous threshold was RON 300,000; art. III of the ordinance sets transitional rules for persons measured against the old figure. Above the threshold, the person must apply for VAT registration.
The same ordinance retitles art. 310 as the special scheme for small enterprises established in Romania and transposes Council Directive (EU) 2020/285, so that small businesses established in another EU Member State can use the Romanian exemption where their total Union turnover does not exceed EUR 100,000 in the current and the preceding calendar year, after prior notification in their home Member State.
What it means
The RON 395,000 threshold is still in force; no later change to it has been recorded. For a small Romanian supplier, the practical question since 1 September 2025 is whether turnover stays under RON 395,000, not under RON 300,000; businesses that crossed RON 300,000 in 2025 should check the transitional rules in art. III before assuming they had to register. For an EU supplier, the threshold matters only together with the EUR 100,000 Union-wide cap and prior notification in its own Member State.
Proof
declarată sau realizată, nu depăşeşte plafonul de 395.000 lei, poate aplica scutirea de taxă, denumită în continuare regim special de scutire, pentru operaţiunile prevăzute la art. 268 alin. (1), cu excepţia livrărilor intracomunitare de mijloace de transport noi, scutite conform art. 294 alin. (2) lit. b).[whose annual turnover,] declared or achieved, does not exceed the threshold of 395,000 lei, may apply the tax exemption, hereinafter the special exemption scheme, for the operations provided for in art. 268(1), except for intra-Community supplies of new means of transport exempt under art. 294(2)(b).
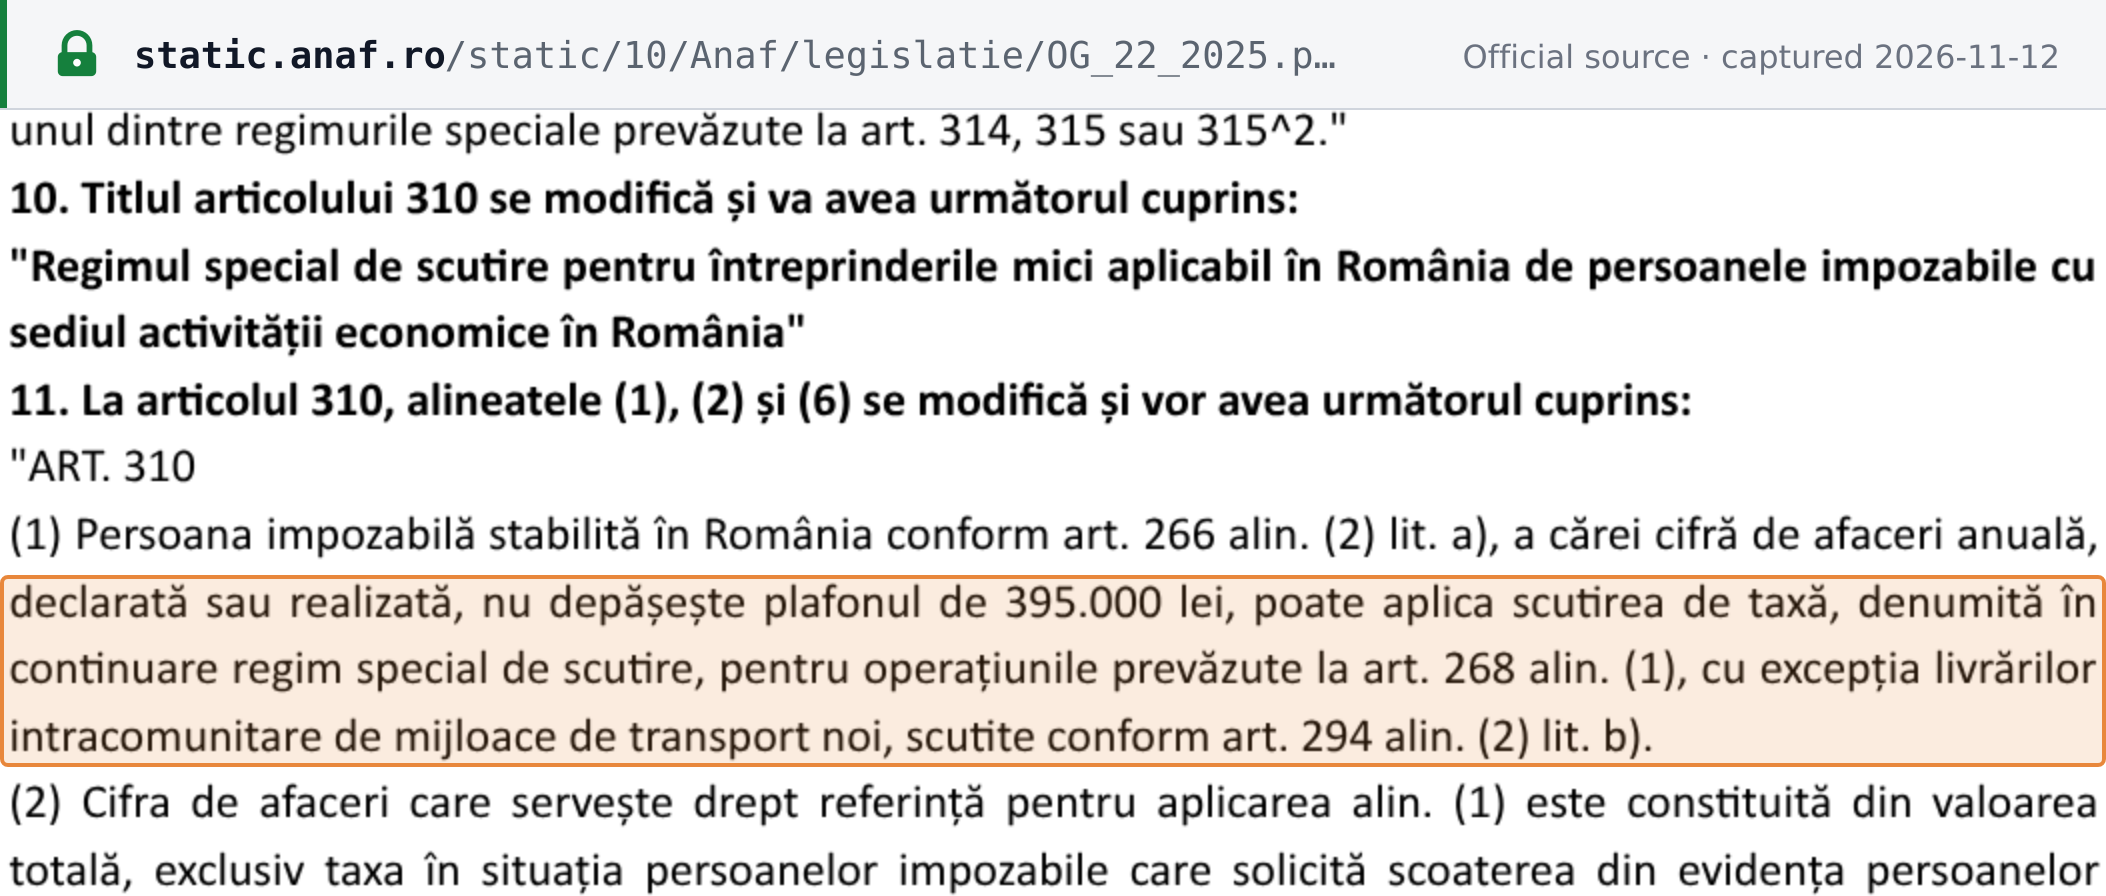 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Ordonanţa Guvernului nr. 22/2025 din 28 august 2025 (Monitorul Oficial nr. 806 din 29 august 2025), ANAF copy OG_22_2025.pdf · static.anaf.ro