Romania raises standard VAT to 21% and merges its reduced rates into 11% from 1 August 2025
- Jurisdiction
- Romania
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 25 July 2025
- Effective
- 1 August 2025
- Instrument
- RO-ACT-141-2025
- Authority
- Agenția Națională de Administrare Fiscală (ANAF)
- Verified
- Fetched from official source · high confidence
All persons making taxable supplies in Romania, and consumers and exempt businesses bearing the VAT; housing buyers relying on the 9% transitional rate.
No action — monitoring only.
Law 141/2025 (Monitorul Oficial nr. 699 of 25 July 2025), promulgated by Decree 791/2025, raised Romania's standard VAT rate from 19% to 21% and merged the 9% and 5% reduced rates into a single 11% reduced rate, effective 1 August 2025 (the 5% rate in art. 291(3) of the Fiscal Code was repealed and its items moved to 11%). Transitionally, one dwelling of up to 120 m2 and RON 600,000 can still be bought at 9% until 31 July 2026 where an advance-payment contract was signed by 1 August 2025.
What changed in detail
Law 141 of 25 July 2025 on fiscal-budgetary measures, published in Monitorul Oficial nr. 699 of 25 July 2025 and promulgated by Decree 791/2025, amends art. 291 of the Fiscal Code (Law 227/2015) with effect from 1 August 2025.
- Standard rate: art. 291(1) raises the standard VAT rate from 19% to 21%.
- Reduced rates: art. 291(2) sets a single reduced rate of 11%, replacing the former 9% rate. Art. 291(3), which held the 5% rate, is repealed, and the items it covered (among them books and newspapers, access to museums and similar venues, social housing, hotel accommodation, restaurant and catering services, and firewood) move into the 11% list.
- Housing transition: under art. III, an individual may buy one dwelling at 9% between 1 August 2025 and 31 July 2026 if it has a usable area of no more than 120 m², is worth no more than RON 600,000 excluding VAT including the land, is delivered by 31 July 2026, and the buyer concluded an advance-payment contract for it by 1 August 2025.
What it means
Romania has had a two-rate structure since 1 August 2025: 21% standard and 11% reduced, with no 5% band. The 9% housing window was transitional and closed on 31 July 2026, so a dwelling delivered after that date takes the 11% rate if it qualifies for the reduced rate at all. When checking an invoice dated before 1 August 2025, the old 19%, 9% and 5% rates still apply to it; supplies made from that date use the new rates, so price lists, POS settings and contracts running across the change date needed repricing at the boundary.
Proof
Art. 291 - (1) Cota standard se aplică asupra bazei de impozitare pentru operaţiunile impozabile care nu sunt scutite de taxă sau care nu sunt supuse cotei reduse, iar nivelul acesteia este 21%. (2) Cota redusă de 11% se aplică asupra bazei de impozitare pentru următoarele prestări de servicii şi/sau livrări de bunuri:Art. 291 - (1) The standard rate applies to the tax base for taxable transactions that are not exempt from tax or not subject to the reduced rate, and its level is 21%. (2) The reduced rate of 11% applies to the tax base for the following supplies of services and/or goods:
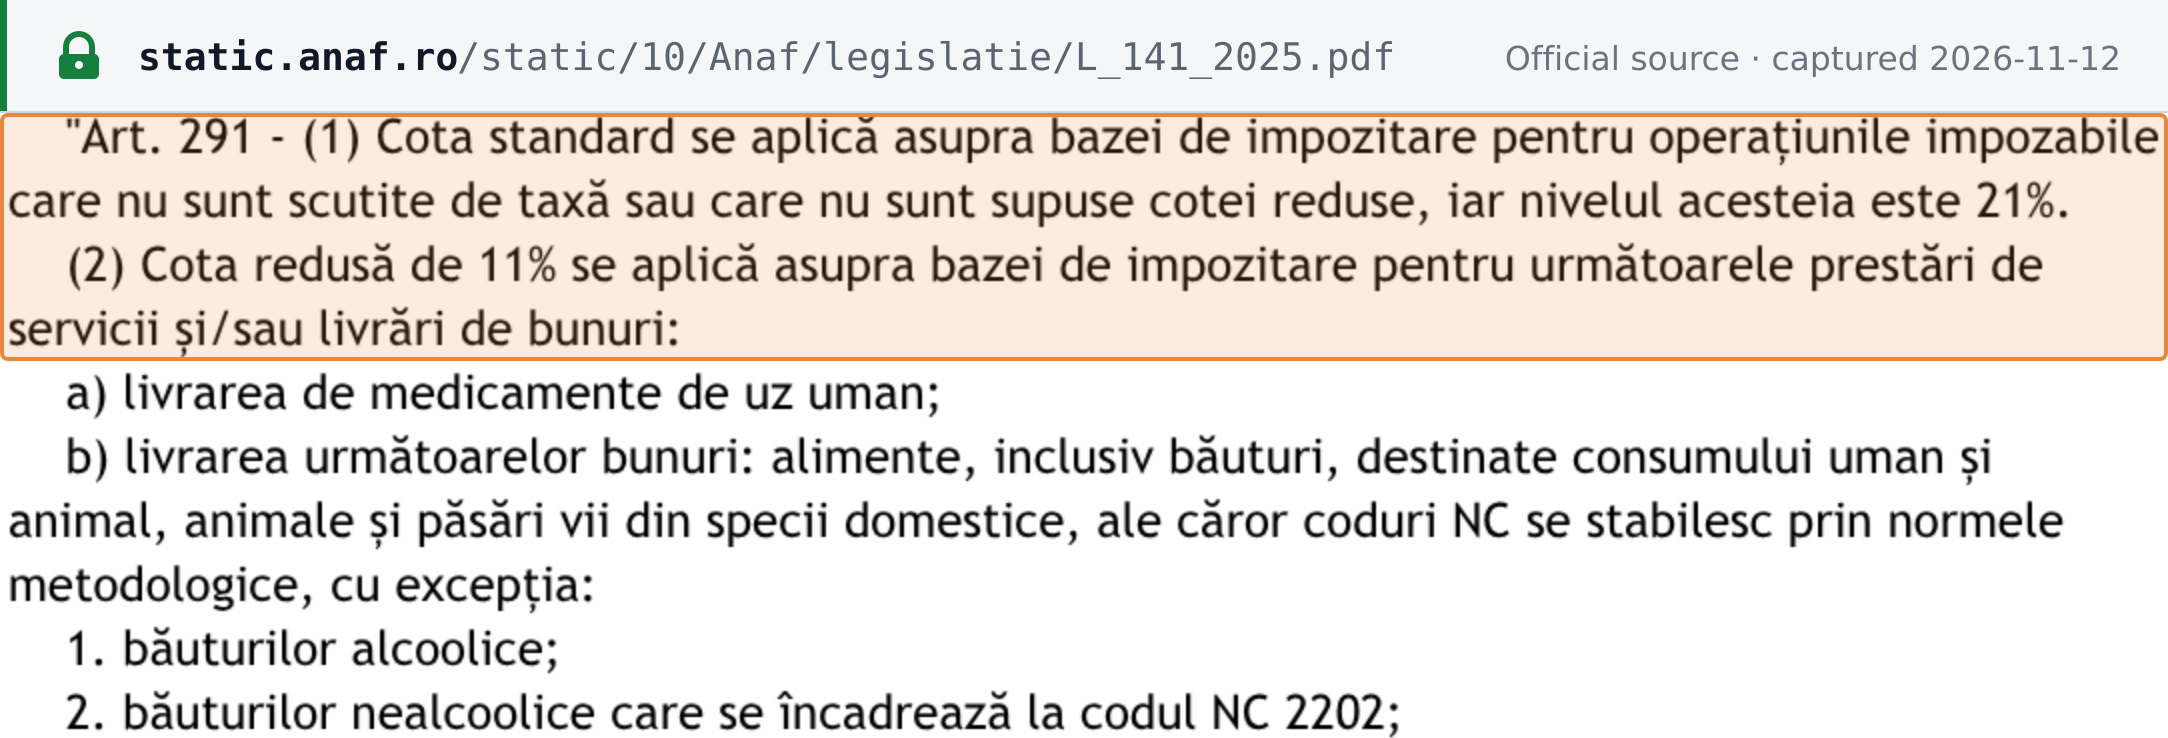 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Legea nr. 141 din 25 iulie 2025 privind unele măsuri fiscal-bugetare (Monitorul Oficial nr. 699 din 25 iulie 2025), ANAF copy L_141_2025.pdf · static.anaf.ro