Slovenia moves drinks with added sugar or sweeteners from 9.5% to the 22% VAT rate from 1 January 2025
This page records one dated change. For the rules in Slovenia as they stand today, see the Slovenia guide →
- Jurisdiction
- Slovenia
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 10 December 2024
- Effective
- 1 January 2025
- Authority
- Finančna uprava Republike Slovenije (FURS)
- Verified
- Fetched from official source · high confidence
Slovenian VAT-registered producers, importers, wholesalers, retailers and vending operators supplying drinks with added sugar or sweeteners, or preparations for making them.
No action — reclassification in force since 1 January 2025; monitoring only.
ZDDV-1O (Uradni list RS 104/2024, published 10 December 2024) amended point 1 of Annex I to ZDDV-1 so that drinks with added sugar or sweeteners, and preparations for making such drinks, no longer qualify for the 9.5% reduced VAT rate and are taxed at the 22% standard rate from 1 January 2025 (transitional rules in Article 47 ZDDV-1O). Drinks without added sugar or sweeteners stay at 9.5%.
What changed in detail
The Act amending the Value Added Tax Act (ZDDV-1O) was published in Uradni list RS No. 104/2024 on 10 December 2024 and entered into force on 11 December 2024. Among the provisions that apply from 1 January 2025, it amends point 1 of Annex I to ZDDV-1, the list of supplies that qualify for the 9.5% reduced rate. Drinks with added sugar or sweeteners, and preparations for making such drinks, are taken out of that list, so they are taxed at the 22% standard rate.
The financial administration’s explanation (FURS, section 3.0 of its note on VAT legislation changes) sets out how this works through the implementing regulation:
- waters, mineral waters, soda waters and other non-alcoholic drinks under tariff heading 2202 stay at 9.5% only if they contain no added sugar or sweeteners;
- sugar syrups and drink preparations under tariff codes 2106 90 30 to 2106 90 59 and 2106 90 98 take the reduced rate only without added sugar or sweeteners;
- juices (2009), liquid food for patients and food supplements (2202 99), and vinegar (2209 00) remain at 9.5%.
Article 47 of ZDDV-1O sets the transitional rule. A supply that straddles 1 January 2025 is taxed in full at 22%. Partial supplies completed before that date may be taxed at 9.5% if they are invoiced by 25 January 2025. A full prepayment received by 31 December 2024 keeps the 9.5% rate.
What it means
The change is not limited to soft drinks in the everyday sense. The test is whether sugar or a sweetener has been added, so a zero-sugar soda with sweeteners moves to 22% along with a sugared one, while plain water and juice without additions stay at 9.5%. Product master data needs a flag for added sugar or sweetener, not just a tariff code.
The rule has applied since 1 January 2025 and is still the position in FURS’s current explanatory documents. The transitional window (invoices by 25 January 2025) is spent. The same Act also raised the small-business threshold, recorded in a separate record.
Proof
Na podlagi spremembe 1. točke Priloge I se iz uporabe nižje stopnje DDV izključuje dobava pijač z dodanim sladkorjem ali sladili ter pripravkov za pripravo pijač z dodanim sladkorjem ali sladili.Under the amendment of point 1 of Annex I, the supply of drinks with added sugar or sweeteners and of preparations for making drinks with added sugar or sweeteners is excluded from the reduced VAT rate.
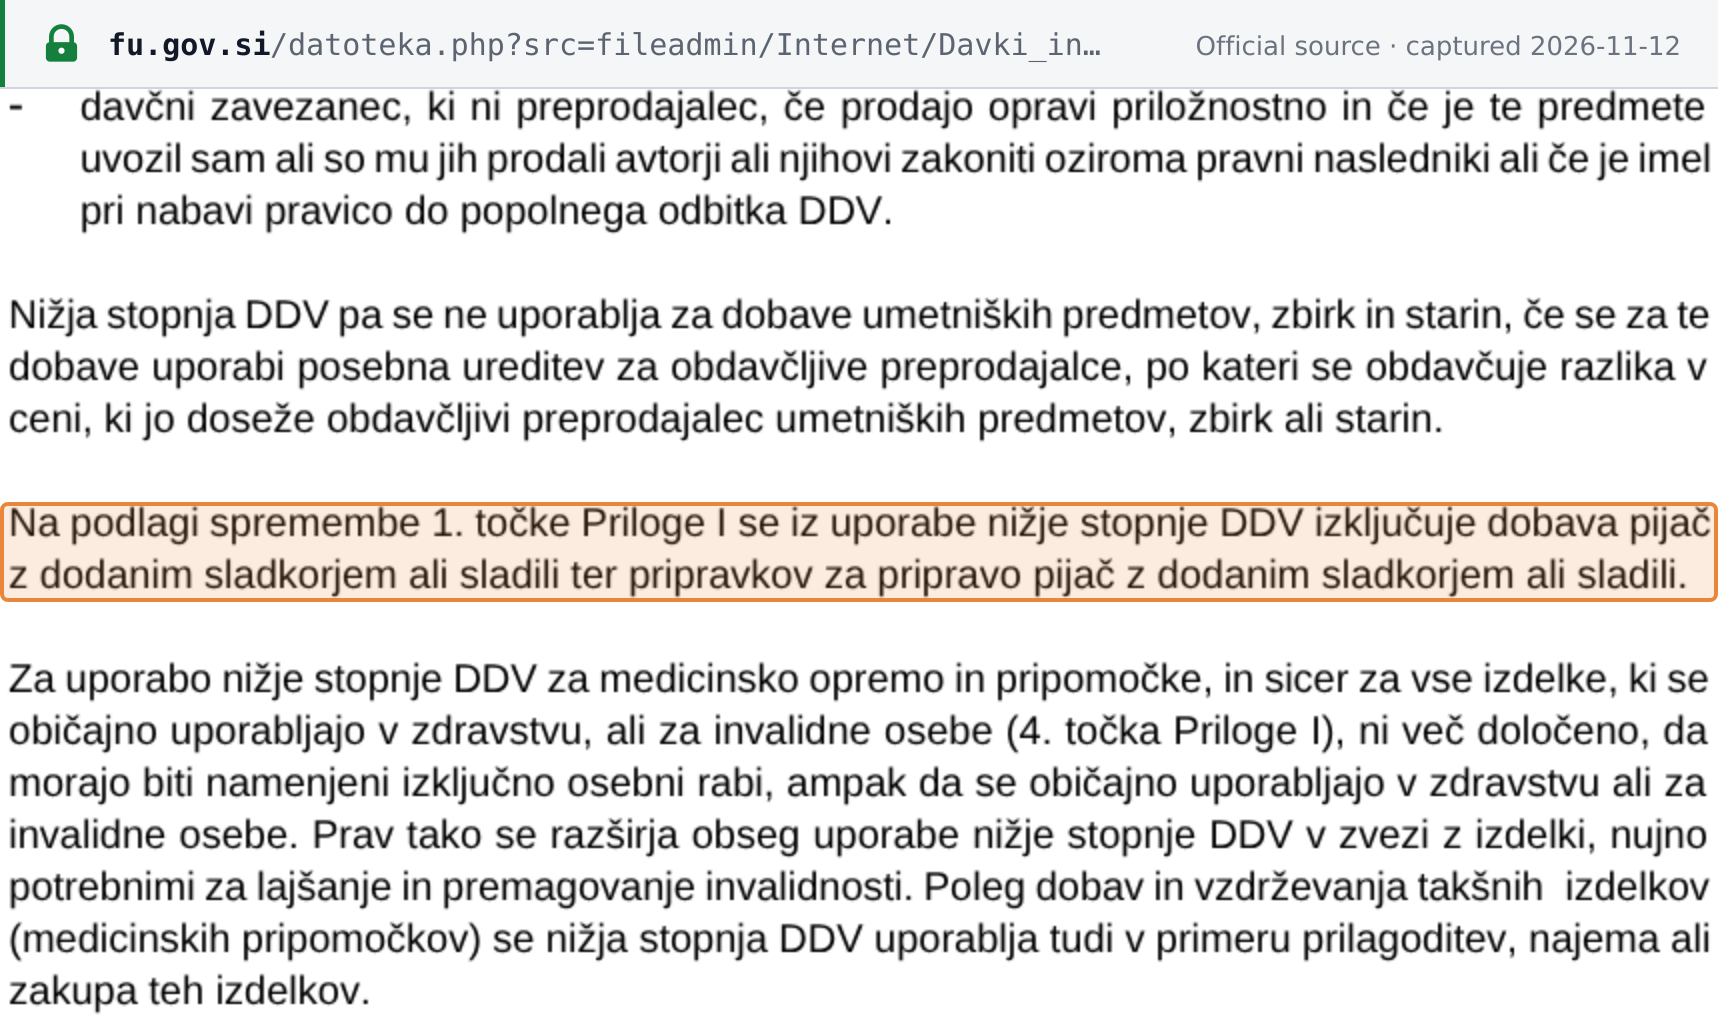 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · FURS, Spremembe zakonodaje na področju DDV (podrobnejši opis), section 3.0: ZDDV-1O · www.fu.gov.si