Slovenia introduces optional VAT groups under ZDDV-1O, available from 1 January 2026
This page records one dated change. For the rules in Slovenia as they stand today, see the Slovenia guide →
- Jurisdiction
- Slovenia
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- FYI
- Announced
- 10 December 2024
- Effective
- 1 January 2026
- Authority
- Finančna uprava Republike Slovenije (FURS)
- Verified
- Fetched from official source · high confidence
Two or more taxable persons established in Slovenia, or Slovenian fixed establishments, that are financially, economically and organisationally linked.
No action — VAT grouping regime in force since 1 January 2026; monitoring only.
ZDDV-1O (Uradni list RS 104/2024, 10 December 2024) introduced a voluntary VAT grouping regime under new Article 5a of ZDDV-1, allowing closely connected taxable persons established in Slovenia (meeting organisational, economic, and financial criteria) to form a VAT group and operate under a single VAT identification number. Transactions between group members fall outside the VAT system. The regime applies from 1 January 2026.
What changed in detail
The Act amending the Value Added Tax Act (ZDDV-1O), published in Uradni list RS No. 104/2024 on 10 December 2024, used the option in Article 11 of the VAT Directive and added a VAT grouping regime to ZDDV-1 as Article 5.a. The regime has applied since 1 January 2026.
As described by the financial administration (FURS):
- two or more taxable persons established in Slovenia, or a fixed establishment in Slovenia (a branch entered in the Slovenian court register), may be treated as one taxable person;
- they must be financially, economically and organisationally linked, all three at once and continuously; financial links mean more than 50% of the capital or voting rights;
- one member acts as the group’s representative and applies on form DDV-P2s through eDavki, with the consent of every joining member, for a single VAT identification number;
- transactions between group members are not subject to VAT, and invoices between members are not VAT invoices;
- the group’s tax period is the calendar month, and members are jointly and severally liable for the VAT arising from their membership.
What it means
Membership is optional. Groups with significant intra-group service flows, especially where some members cannot fully deduct VAT, such as financial or insurance businesses, can take those flows out of VAT altogether. The cost is joint liability and a group-wide deduction position, so the decision is not purely administrative.
The regime has been available since 1 January 2026 and remains in force. The same Act raised the small-business threshold, recorded in a separate record.
Proof
Možnost obravnave več oseb kot skupine za DDV se je v slovenski pravni red prenesla z Zakonom o spremembah in dopolnitvah Zakona o davku na dodano vrednost (ZDDV-1O), uporabljati pa se je začela s 1. 1. 2026.The option to treat several persons as a VAT group was transposed into Slovenian law by the Act amending the Value Added Tax Act (ZDDV-1O), and it has applied since 1 January 2026.
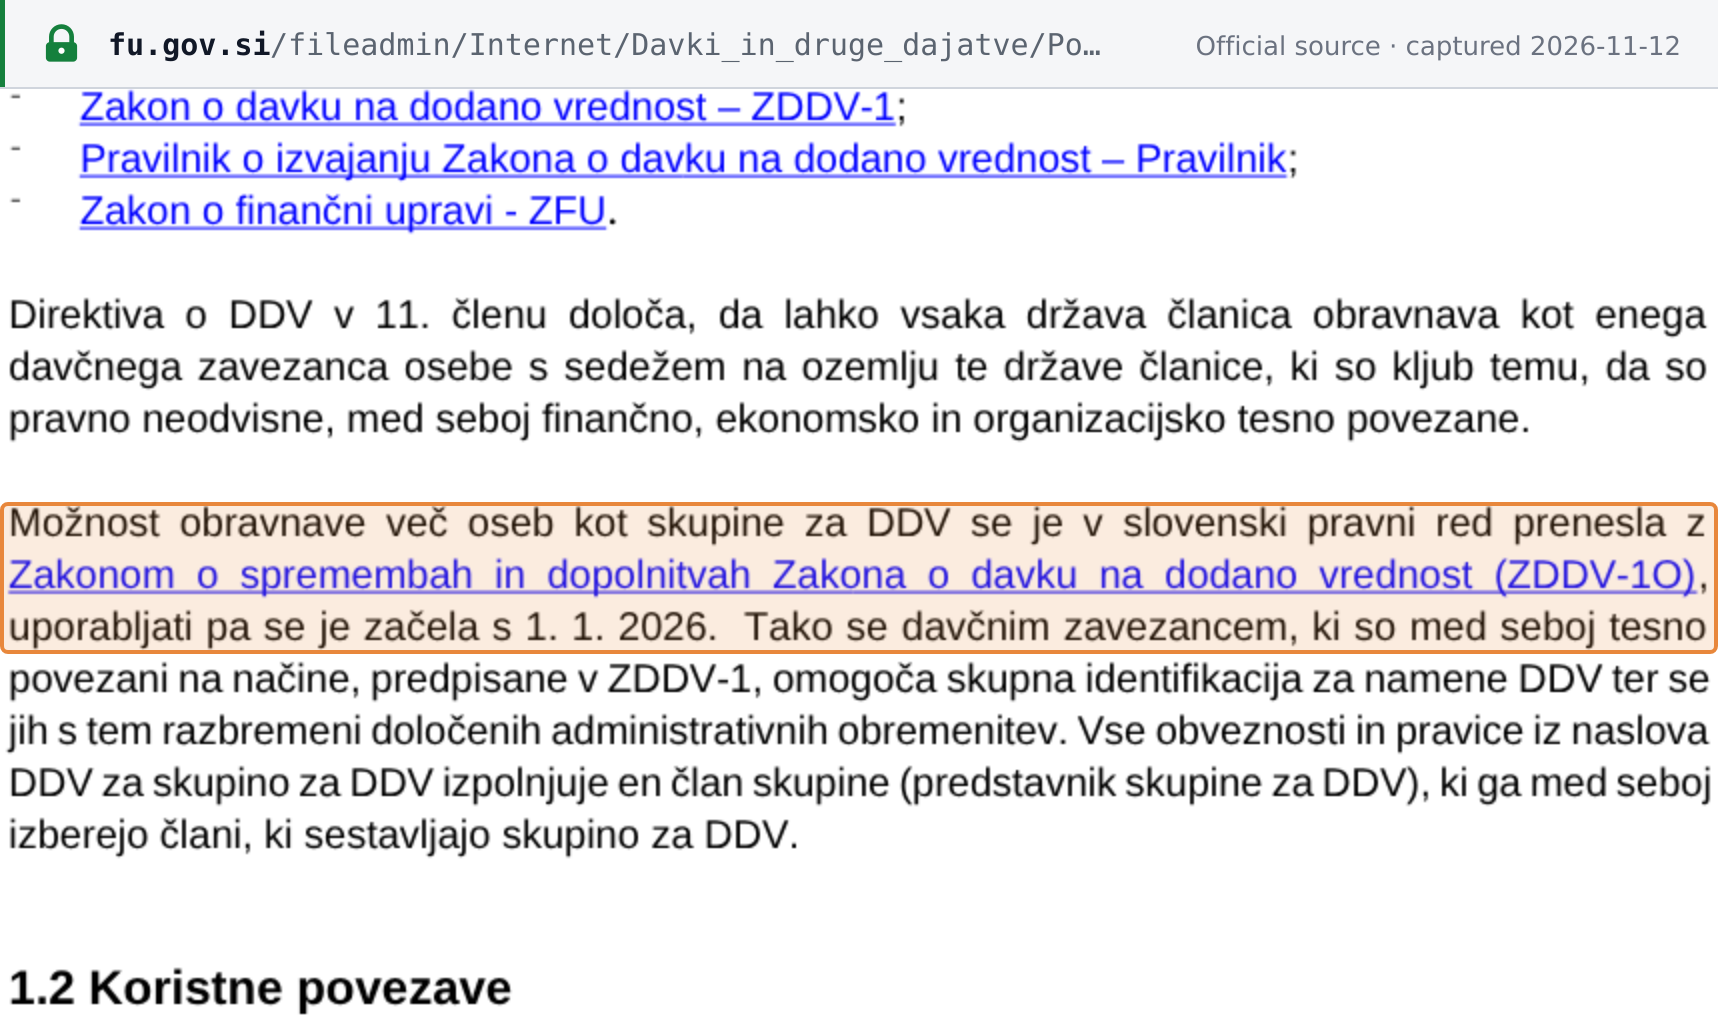 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · FURS, Skupina za DDV, podrobnejši opis, section 1.1 · www.fu.gov.si