South Africa gives recipients 60 days instead of 30 to pay VAT on imported services
This page records one dated change. For the rules in South Africa as they stand today, see the South Africa guide →
- Jurisdiction
- South Africa
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 24 December 2024
- Effective
- 24 December 2024
- Instrument
- ZA-ACT-43-of-2024
- Authority
- Parliament of the Republic of South Africa
- Verified
- Fetched from official source · high confidence
Persons in South Africa that receive imported services for non-taxable purposes, mainly non-vendors and vendors making exempt supplies, who self-account under s 7(1)(c).
No action required — in force since 24 December 2024. Recipients of imported services should confirm their payment processes use the 60-day period rather than the former 30-day period.
Tax Administration Laws Amendment Act 43 of 2024 (GG 51827, 24 December 2024) amended s 14(1) of the Value-Added Tax Act 89 of 1991 by s 9 of the Amendment Act, effective 24 December 2024, extending the period within which VAT on imported services must be accounted for and paid by the recipient from 30 to 60 days.
What changed in detail
Section 9 of the Tax Administration Laws Amendment Act 43 of 2024 (Government Gazette 51827, 24 December 2024) substitutes the opening words of section 14(1) of the Value-Added Tax Act 89 of 1991.
Where tax is payable under section 7(1)(c) on the supply of imported services, the recipient must now account for and pay it within 60 days of the date referred to in section 14(2), instead of 30 days. The rest of section 14(1), which sets the form of the declaration and payment, is unchanged.
The Act gives section 9 no commencement date of its own. Under section 34(2), amendments without one come into operation on the date of promulgation, 24 December 2024.
The long title of the Act describes the change as extending “the time period within which value-added tax should be accounted for, and is payable by the recipient of imported services”.
What it means
The 60-day period has applied since 24 December 2024. We found no later amendment to section 14(1) in Acts 3 to 5 of 2026.
This matters mostly to non-vendors and to vendors with exempt activity, such as financial services businesses and some public bodies, that buy services from abroad. Registered vendors using imported services wholly for taxable supplies owe no tax under section 7(1)(c) in the first place. The longer window allows time to match foreign invoices and payments before the declaration, but late payment after day 60 still attracts penalties and interest under the Tax Administration Act.
Proof
Where tax is payable in terms of section 7(1)(c) in respect of the supply of imported services the recipient shall within [30] 60 days of the date referred to in subsection (2)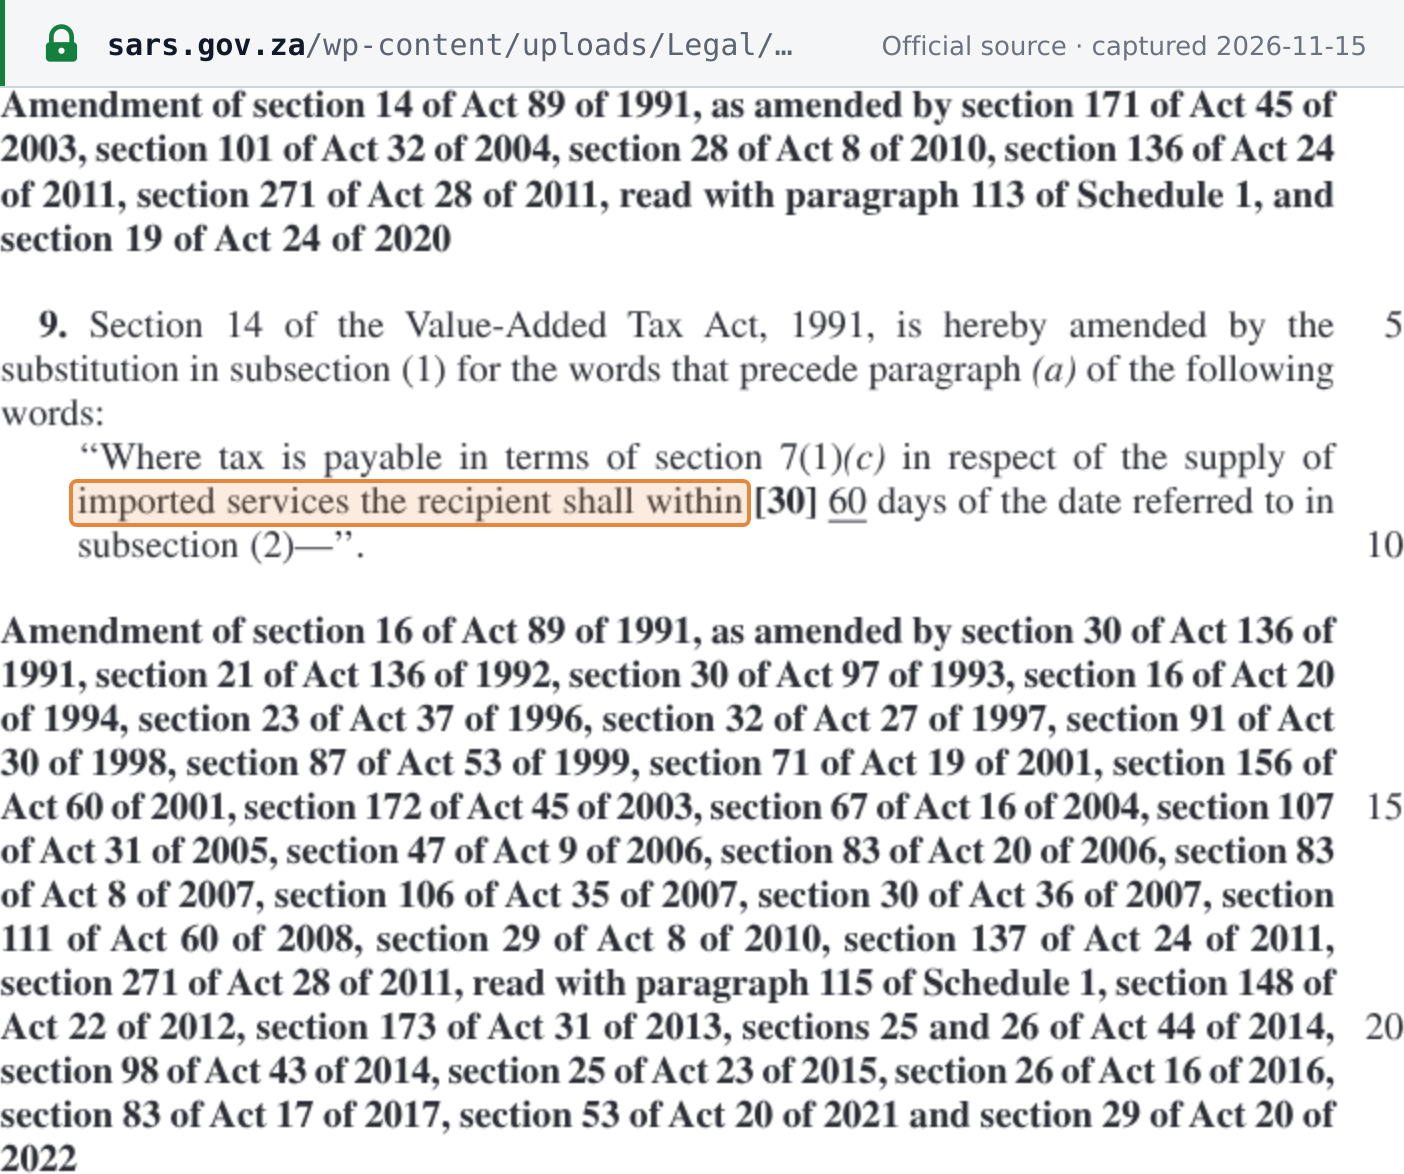 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Tax Administration Laws Amendment Act 43 of 2024, Government Gazette No. 51827, 24 December 2024 · www.sars.gov.za