South Africa excludes foreign suppliers' sales made solely to VAT vendors from the electronic services regime
This page records one dated change. For the rules in South Africa as they stand today, see the South Africa guide →
- Jurisdiction
- South Africa
- Tax
- VAT
- Change type
- Digital services
- Status
- In force
- Impact
- Action required
- Announced
- 14 March 2025
- Effective
- 1 April 2025
- Instrument
- ZA-GOVERNMENT-NOTICE-GN-5993
- Authority
- National Treasury (South Africa)
- Verified
- Fetched from official source · high confidence
Non-resident suppliers of electronic services into South Africa, in particular those whose customers are all VAT vendors registered under section 23.
Non-resident electronic services suppliers selling exclusively to South African VAT-registered vendors should reassess whether they still need to be registered from 1 April 2025; suppliers with any non-vendor customers remain within the regime.
Government Notice 5993 (Regulation Gazette 10177, Government Gazette 52293, 14 March 2025), made by the Minister of Finance, prescribes electronic services for the definition of 'electronic services' in section 1(1) of the VAT Act 89 of 1991. Regulation 2(d) excludes services supplied from an export country by a non-resident solely to vendors registered under section 23. Foreign suppliers that supply only to registered vendors therefore need not register for VAT on those supplies; suppliers to both vendors and non-vendors remain liable on all supplies. The Regulations took effect on 1 April 2025 and repeal all prior regulations (GN 429 of 2019).
What changed in detail
Government Notice 5993 (Regulation Gazette 10177, Government Gazette 52293, 14 March 2025), made by the Minister of Finance, prescribes which services are “electronic services” for the definition in section 1(1) of the Value-Added Tax Act 89 of 1991.
Regulation 2 defines electronic services as any services supplied by means of an electronic agent, electronic communication or the internet for any consideration, other than:
- (a) educational services supplied from an export country and regulated by an educational authority there;
- (b) telecommunications services;
- (c) certain services supplied within a group of companies by a non-resident company to a resident company; and
- (d) services supplied from an export country by a non-resident where the services are supplied solely to vendors registered in the Republic under section 23.
The Regulations came into effect on 1 April 2025. From that date they repeal all earlier regulations made for this purpose, including GN 429 of 2019.
What it means
The exclusion is in force. A foreign supplier whose South African customers are all registered VAT vendors no longer supplies “electronic services” for VAT purposes, so it does not need to register in South Africa for those supplies.
The word “solely” does the work. A supplier with even some non-vendor customers, such as consumers or unregistered businesses, stays inside the regime for all its supplies. Suppliers relying on the exclusion need reliable evidence of each customer’s VAT registration, and they need to watch for non-vendor sales that would bring them back into the regime.
Proof
services supplied from a place in an export country by a person that is not a resident of the Republic where such services are supplied solely to vendors registered in the Republic in terms of section 23 of the Act.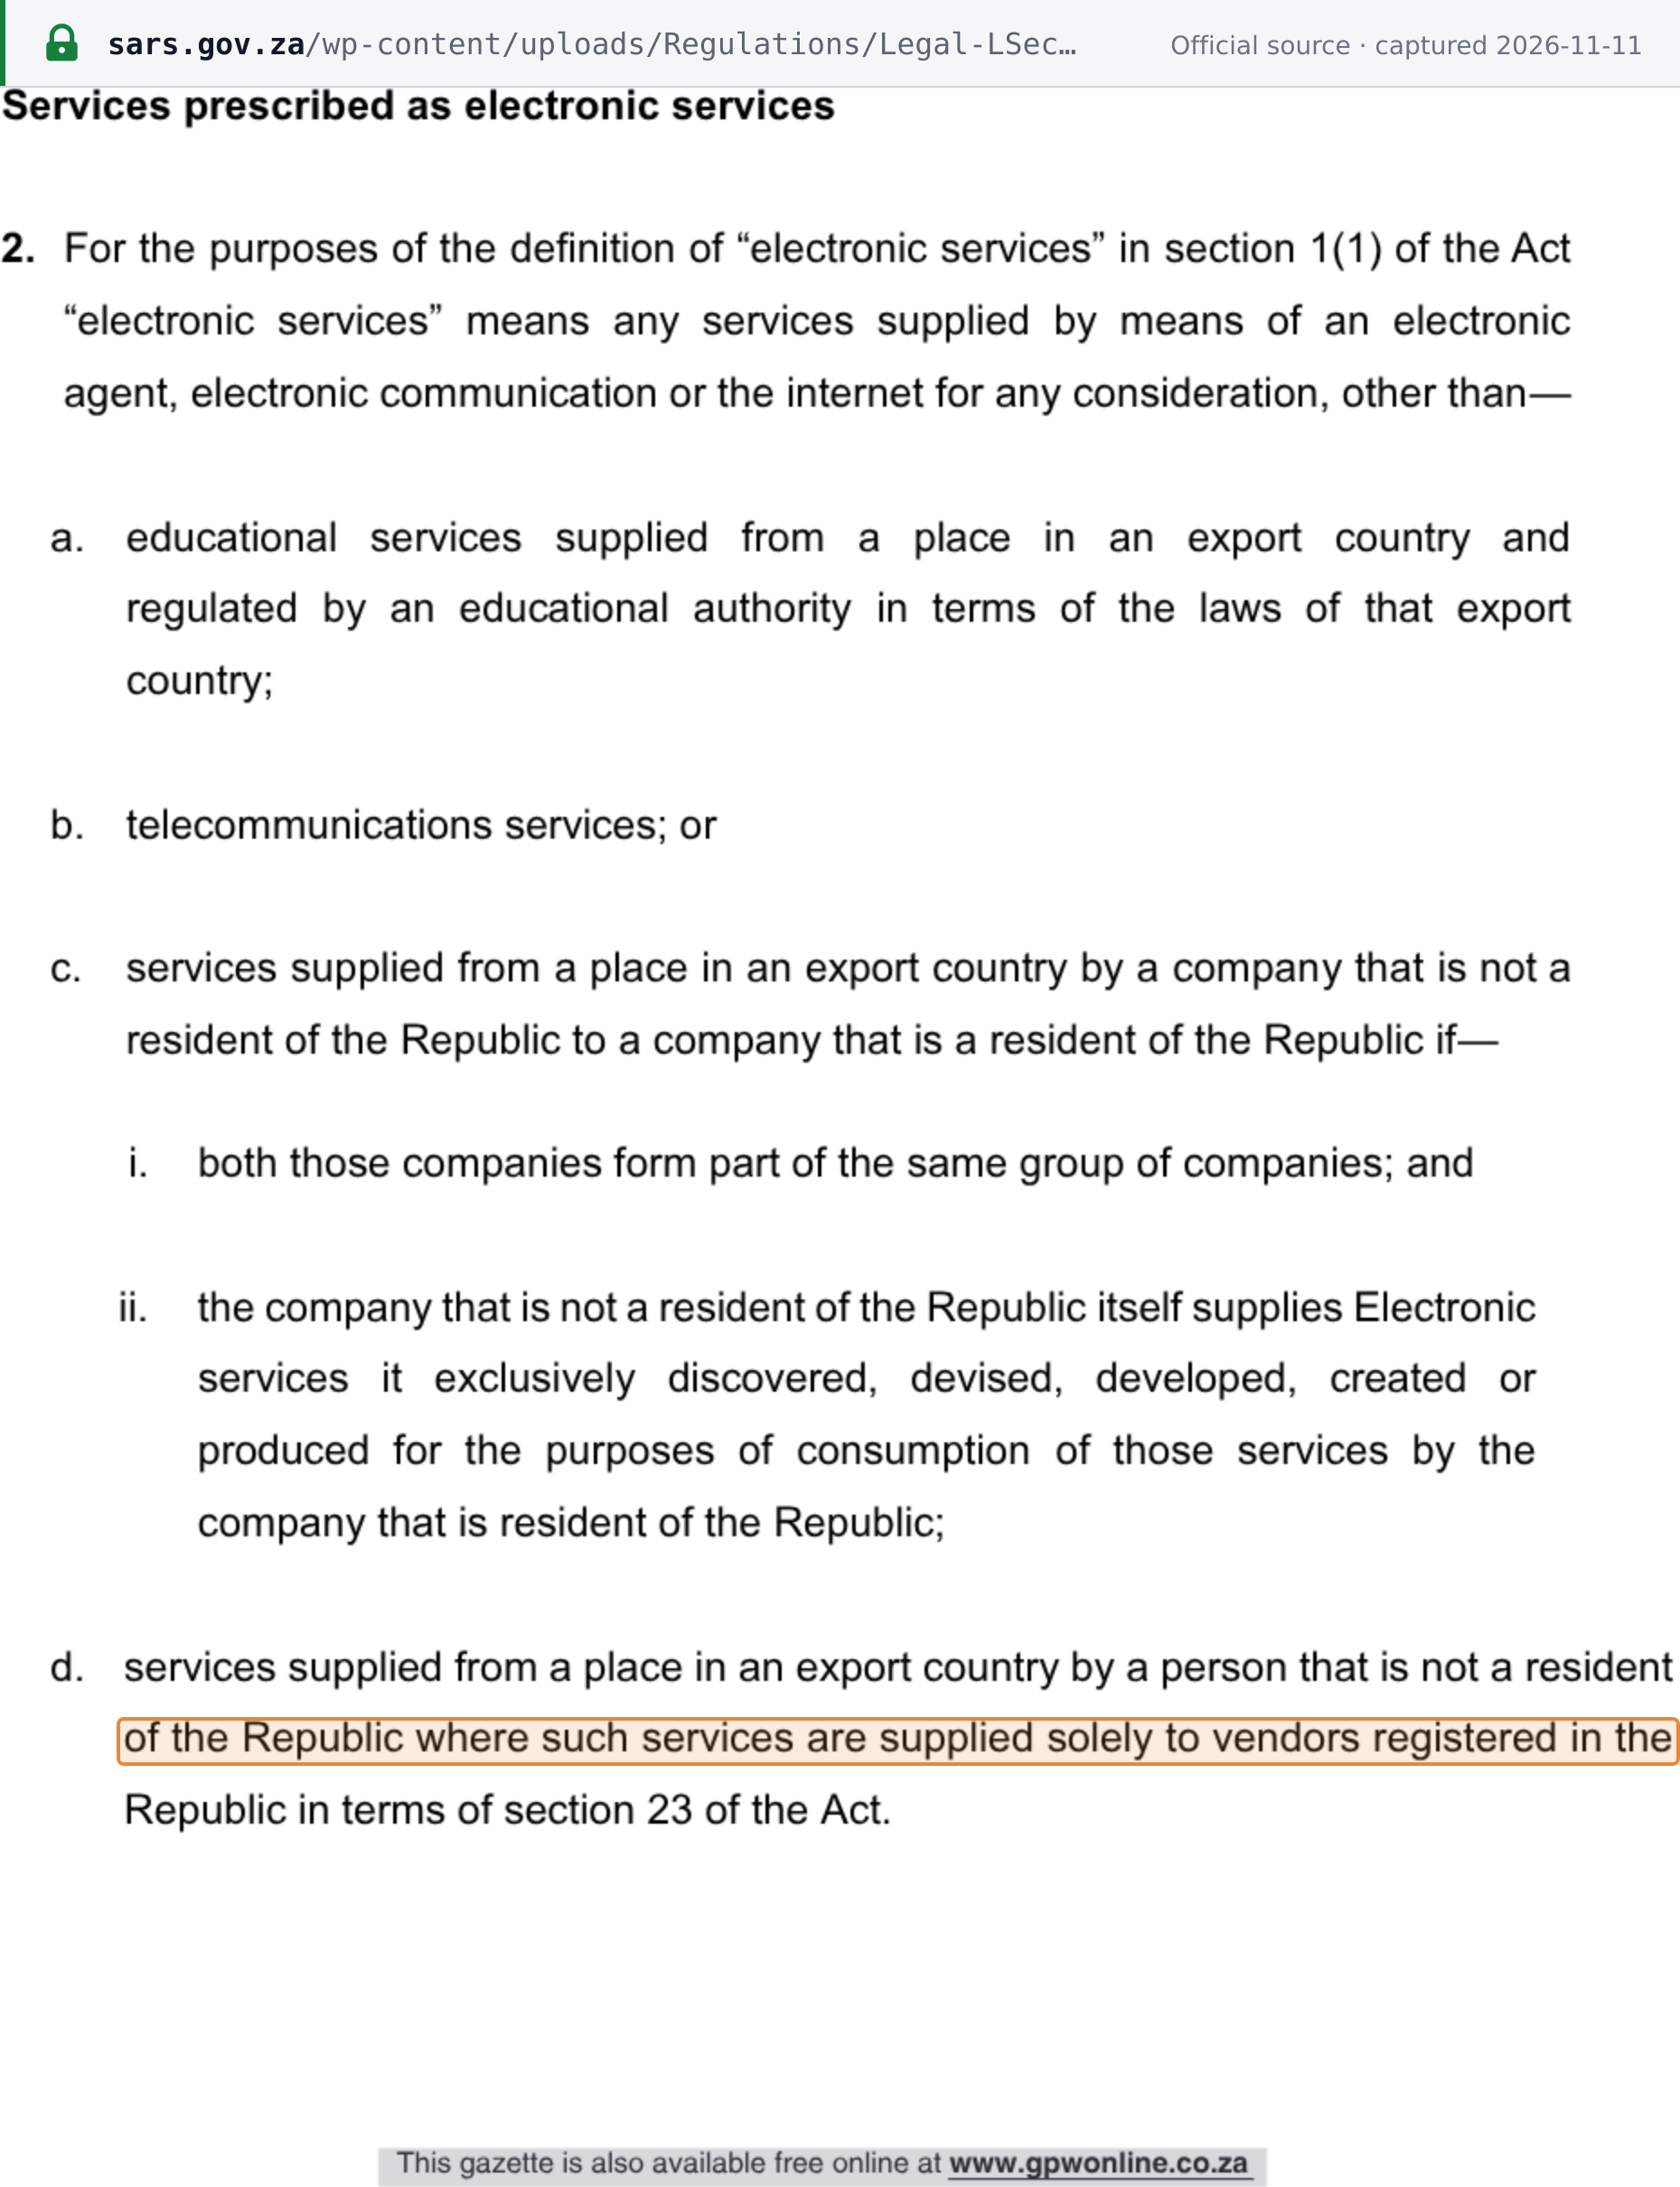 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Government Notice 5993, Regulation Gazette No. 10177, Government Gazette No. 52293, 14 March 2025 · www.sars.gov.za