Taiwan adds a carrier-code upload duty for e-invoices and a NT$1,500–15,000 fine, from 1 January 2025
This page records one dated change. For the rules in Taiwan as they stand today, see the Taiwan guide →
- Jurisdiction
- Taiwan
- Tax
- Business Tax (VAT)
- Change type
- E-invoicing
- Status
- In force
- Impact
- FYI
- Announced
- 7 August 2024
- Effective
- 1 January 2025
- Instrument
- TW-ACT-Hua-Tsung-1-Yi-No-11300068911
- Authority
- Ministry of Finance, R.O.C. (mof.gov.tw)
- Verified
- Fetched from official source · high confidence
Businesses in Taiwan that issue electronic uniform invoices, in particular retailers whose customers ask for e-invoices on a mobile barcode, membership or other approved carrier.
No action — monitoring only.
Amendment of the Value-Added and Non-Value-Added Business Tax Act promulgated 7 August 2024 (Presidential Decree Hua-Tsung-1-Yi No. 11300068911; amended Arts 6-1, 32-1 and 50, added Art 48-2), in force 1 January 2025 by Executive Yuan order. Art 32-1 (in the Act since 2016) now also requires businesses issuing electronic uniform invoices to upload buyers' carrier identification codes to the MOF E-Invoice Platform within the MOF-announced time limit. New Art 48-2 fines late, missing or incorrect uploads NT$1,500 to NT$15,000, with continuous punishment for each violation if not corrected. The upload deadlines themselves are set by MOF announcement, not by the Act.
What changed in detail
An amendment to Taiwan’s Value-Added and Non-Value-Added Business Tax Act was promulgated by Presidential Decree Hua-Tsung-1-Yi No. 11300068911 on 7 August 2024. It amended Articles 6-1, 32-1 and 50 and added a new Article 48-2. The Act left the start date to the Executive Yuan, which set it at 1 January 2025.
Article 32-1 has been in the Act since 2016. It requires a business that issues electronic uniform invoices to transmit them, with the required information, to the Ministry of Finance E-Invoice Platform within the time limit the Ministry prescribes. The 2024 amendment adds that, where a buyer asks for the invoice to be stored on an approved carrier, the business must upload the invoice with the carrier’s identification code. Carriers include national ID and Citizen Digital Certificate numbers, phone numbers, membership numbers and payment-instrument numbers.
New Article 48-2 penalises a failure to transmit the invoices, the required information or the buyer’s carrier code within the prescribed time limit, or a transmission of incorrect information. The business is ordered to correct the failure within a set period and may be fined NT$1,500 to NT$15,000. If it does not correct the failure in time, it can be fined again for each violation. The upload deadlines themselves are set by Ministry of Finance announcement, not by the Act.
What it means
The provisions remain in force in November 2026. The Act’s English text on the Ministry of Finance database shows only one later amendment, to Article 58 (in force 1 January 2026), which does not touch Articles 32-1 or 48-2.
Since 2025 a late, missing or wrong upload carries its own fine, and the duty covers the buyer’s carrier code as well as the invoice itself; without the code the invoice does not reach the buyer’s carrier. Point-of-sale systems that capture the carrier at checkout need to pass it through to the upload. The exact upload windows come from Ministry announcements; this amendment does not set them.
Proof
Addendum to Article 48-2 and Amendments to Articles 6-1, 32-1, and 50 were promulgated via Presidential Decree Hua-Tsung-1-Yi No.11300068911 on August 7, 2024. The effective date of the amendments to the Act shall be prescribed by the Executive Yuan. (The amendments came into force from January 1, 2025.)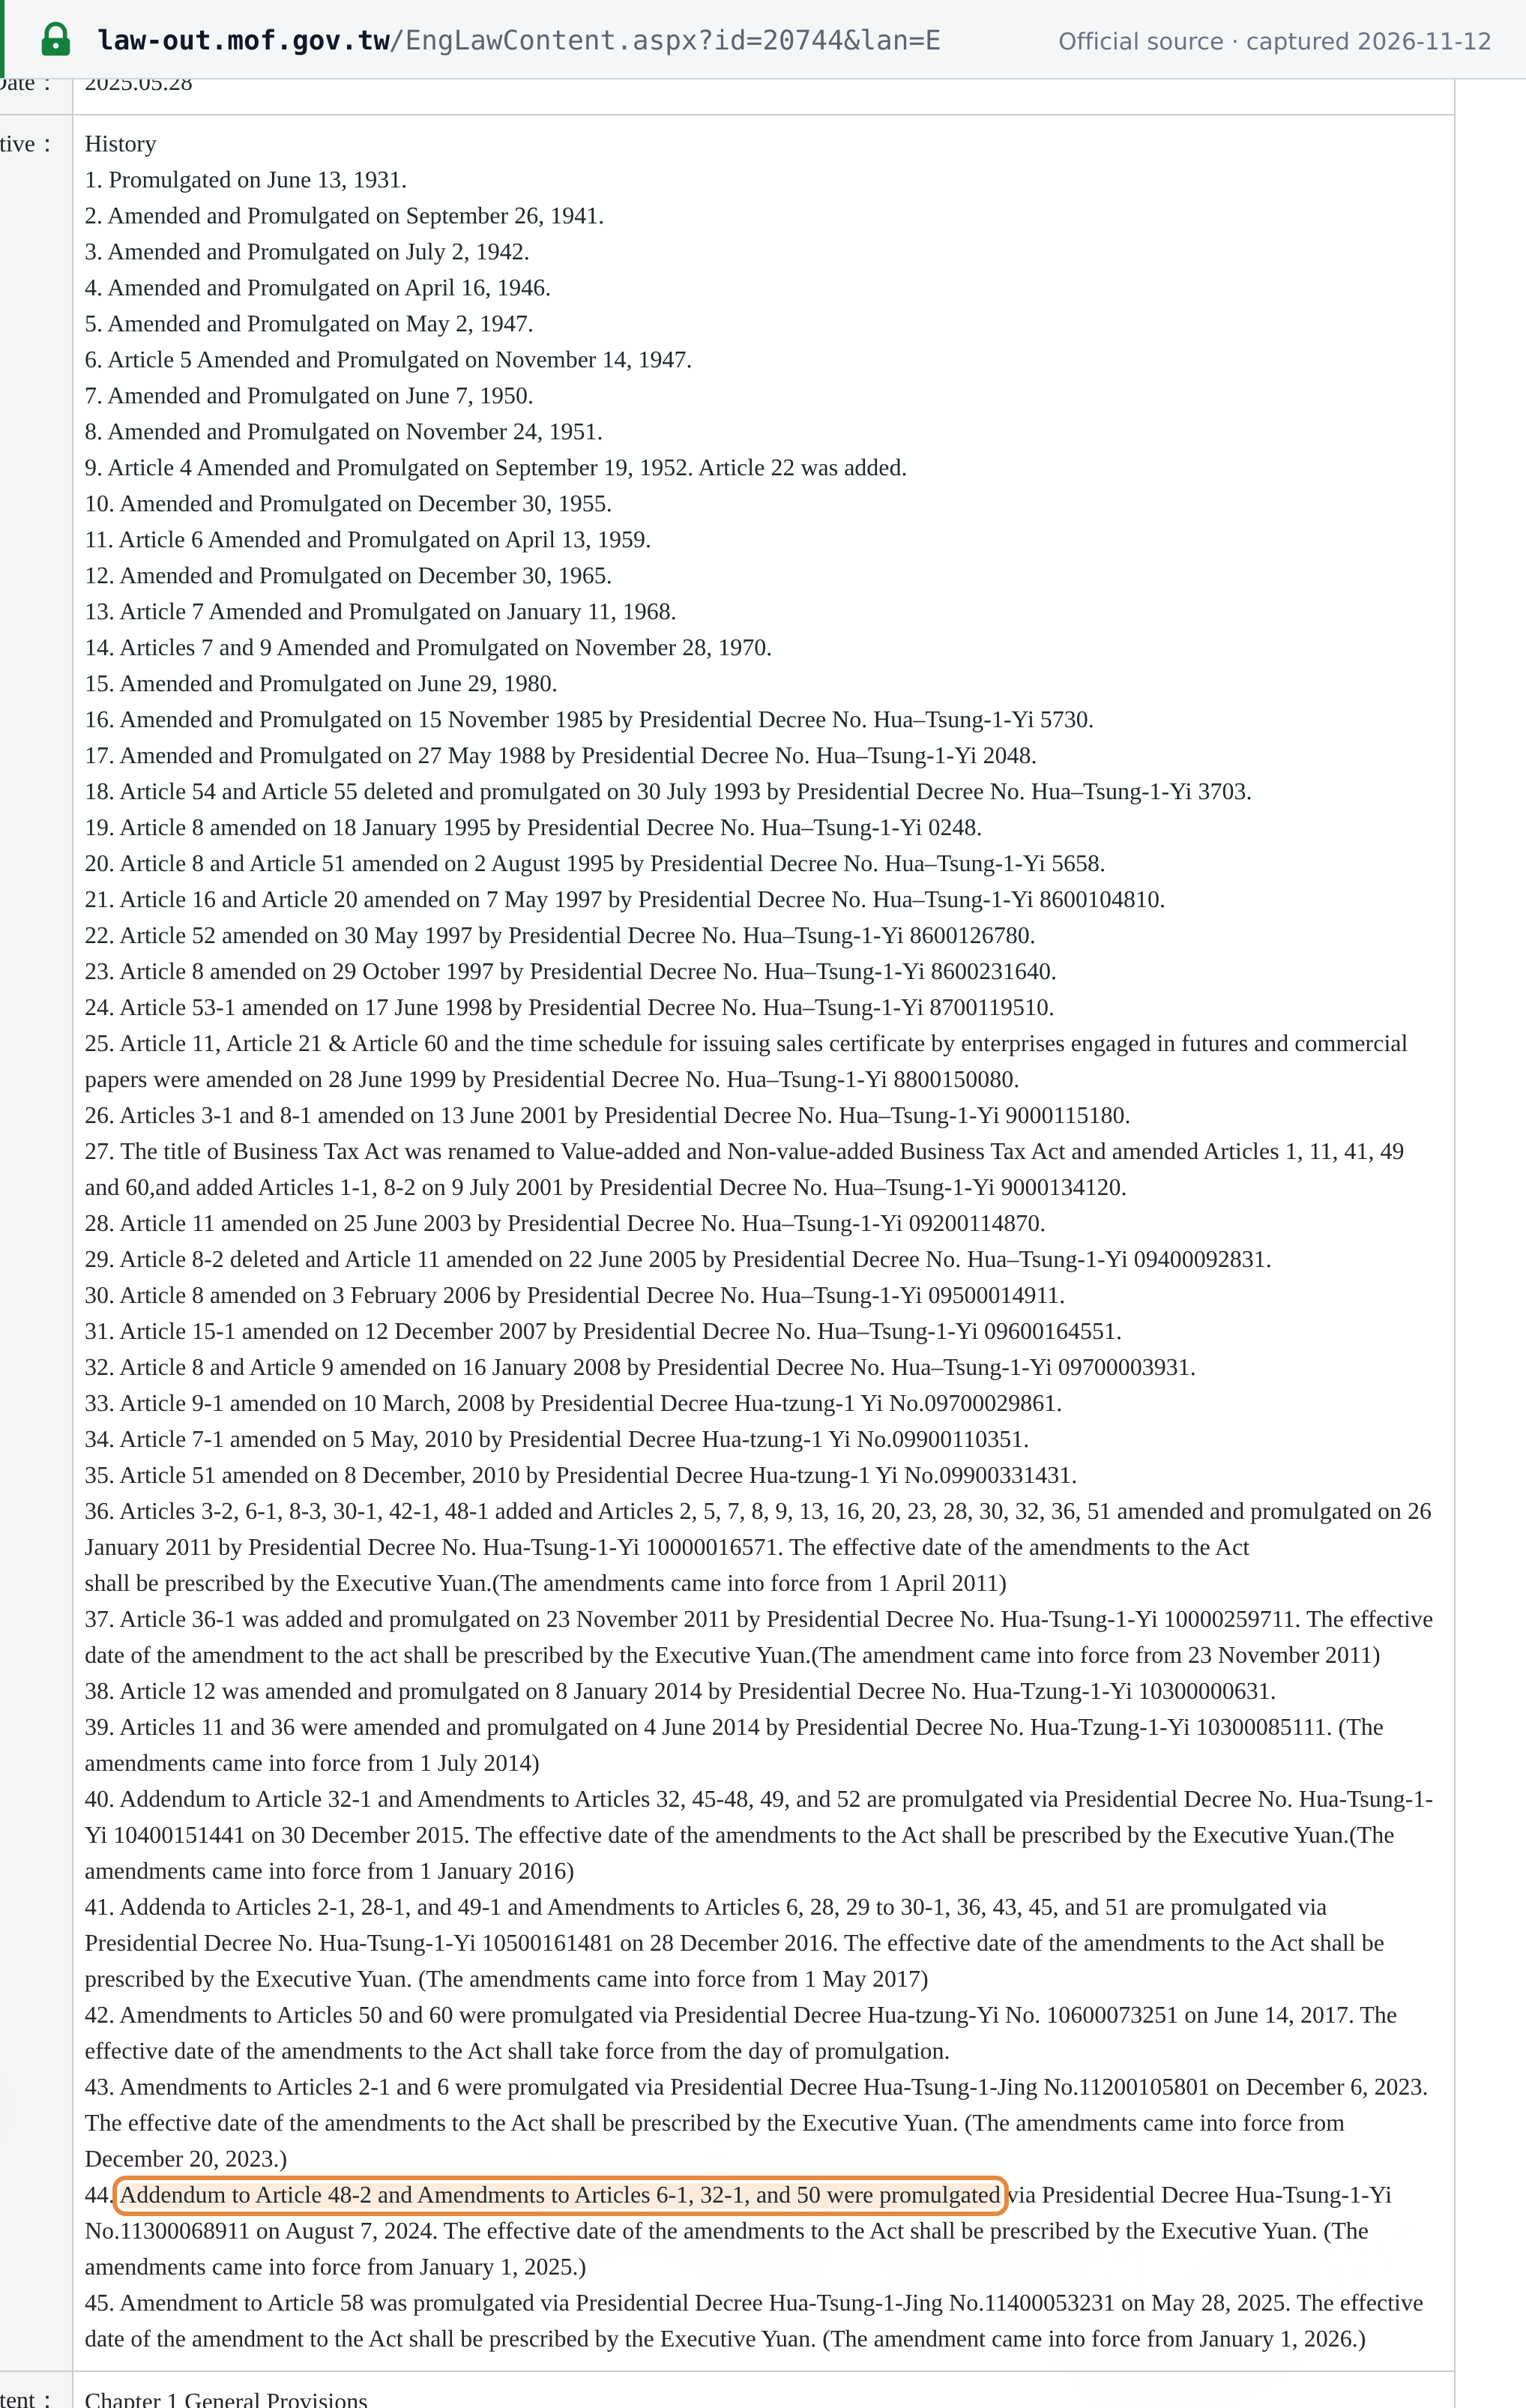 Source snapshot of the official page. Open full size ↗
In the event that a business entity issuing and transmitting electronic uniform invoices via the internet or by other electronic means fails to transmit the electronic uniform invoices and the required relevant information, and the identification codes of carriers of the purchasers to the E-Invoice Platform of the MOF within the prescribed time limit, under Paragraph 1, Article 32-1, or fails to transmit the correct information, the business entity, in addition to being notified to make corrections or to comply with the requirements within a specified time limit, may be fined no less than NT$1,500 and no more than NT$15,000.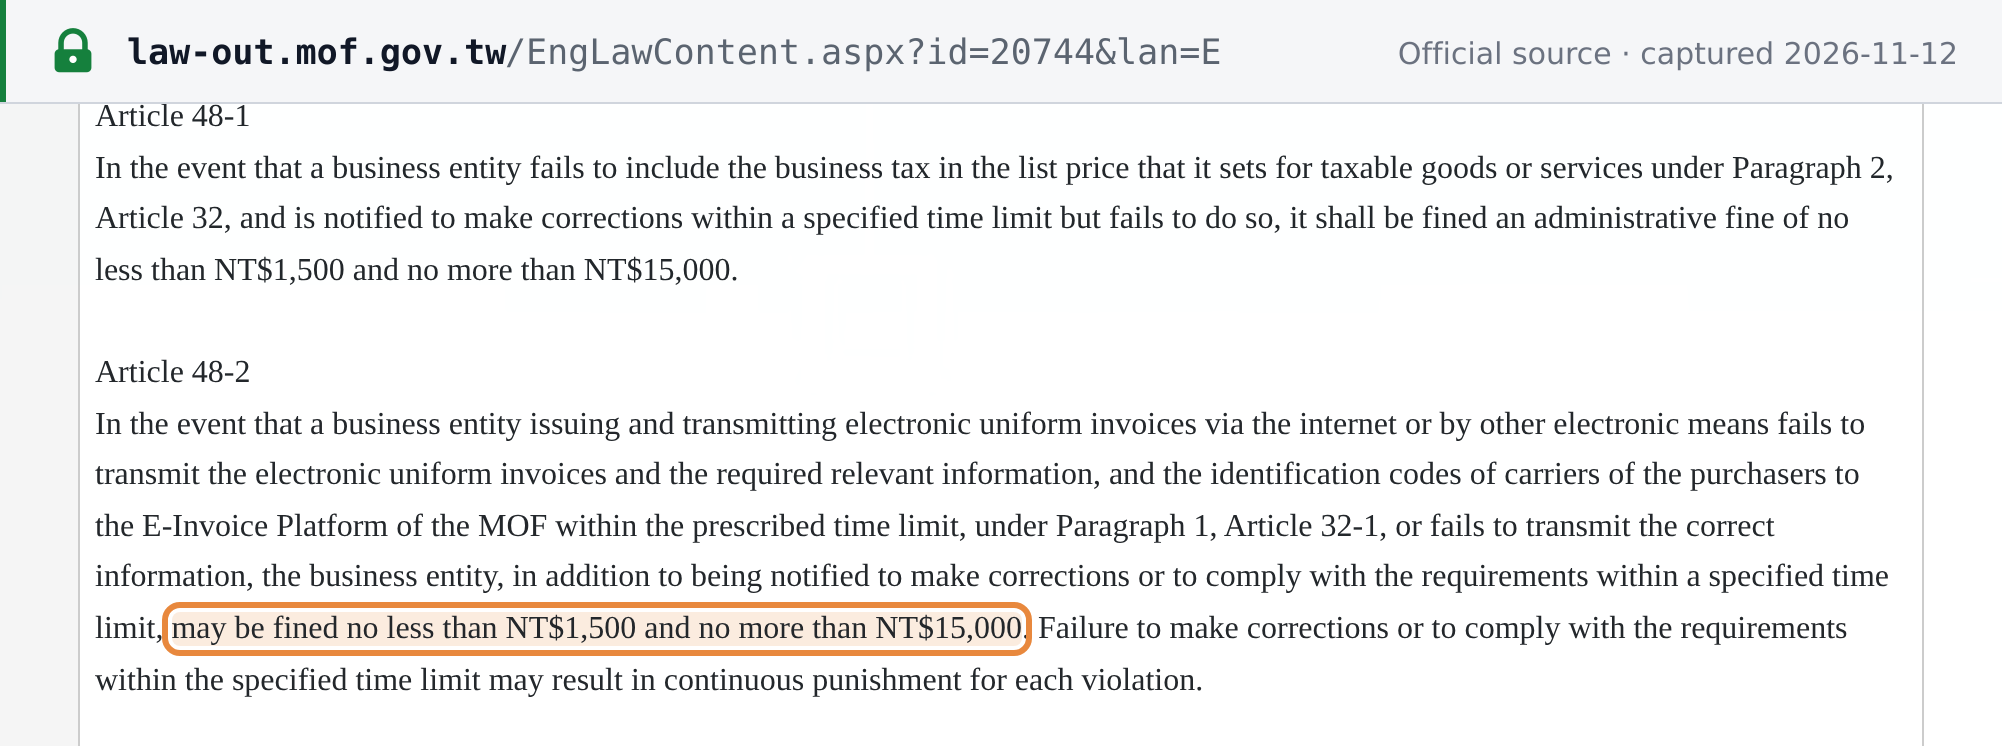 Source snapshot of the official page. Open full size ↗