Taiwan raises small-business tax thresholds to NT$100,000 and NT$50,000 a month from 1 January 2025
This page records one dated change. For the rules in Taiwan as they stand today, see the Taiwan guide →
- Jurisdiction
- Taiwan
- Tax
- Business Tax (VAT)
- Change type
- Threshold
- Status
- In force
- Impact
- FYI
- Announced
- 12 December 2024
- Effective
- 1 January 2025
- Authority
- Ministry of Finance, R.O.C. (mof.gov.tw)
- Verified
- Fetched from official source · high confidence
Small-scale businesses in Taiwan taxed under Article 26 of the Business Tax Act whose monthly sales sit near the NT$100,000 (trading, manufacturing and similar) or NT$50,000 (repair, lodging, services and similar) threshold.
No action — monitoring only.
Taiwan's Ministry of Finance raised the monthly business tax exemption thresholds for small-scale enterprises, effective 1 January 2025: from TWD 80,000 to TWD 100,000 and from TWD 40,000 to TWD 50,000 for the two lists of industries set by the order. The previous increase had been in 2007.
What changed in detail
On 12 December 2024 Taiwan’s Ministry of Finance issued order Tai-Tsai-Shui-Tzu No. 11304677940, amending the standing order on the business-tax threshold (起徵點) for small-scale businesses. The order is made under Article 26 of the Value-Added and Non-Value-Added Business Tax Act.
The order sets two monthly sales thresholds, each tied to a list of industries rather than a strict goods/services split:
- NT$100,000 a month (previously NT$80,000) for trading, manufacturing, handicrafts, news, publishing, agriculture and forestry, animal husbandry, fisheries, mining, contracting, printing, public utilities, entertainment, transport, photography and general food-and-drink businesses.
- NT$50,000 a month (previously NT$40,000) for decoration, advertising, repair, processing, lodging, barbering, bathing, labour contracting, warehousing, leasing, agency, commission, technical and design, and notary businesses.
A business operating in both groups is taxable when the sum of its sales in each group, as a percentage of that group’s threshold, reaches 100%. Point 5 of the order makes it effective from 1 January 2025. The previous thresholds had applied since 1 January 2007.
What it means
The order is still in force: the Ministry of Finance law database shows the 12 December 2024 version as the current text in November 2026, and the weekly feed holds no later change to these figures. A small business whose monthly sales stay below its group’s threshold is not taxed, and the thresholds, both 25% higher, took many micro-businesses out of collection from 2025.
The figures are not a goods-versus-services test, which is how they are often summarised. Lodging and repair fall in the NT$50,000 group, transport and food service in the NT$100,000 group. The same thresholds were later applied to domestic online content creators in the Ministry’s creative-works directions.
Proof
起徵點為每月銷售額新臺幣十萬元 … 起徵點為每月銷售額新臺幣五萬元 … 五、本令自中華民國一百十四年一月一日生效。The minimum taxable threshold is monthly sales of NT$100,000 … the minimum taxable threshold is monthly sales of NT$50,000 … 5. This order takes effect on 1 January 2025 (Republic of China year 114).
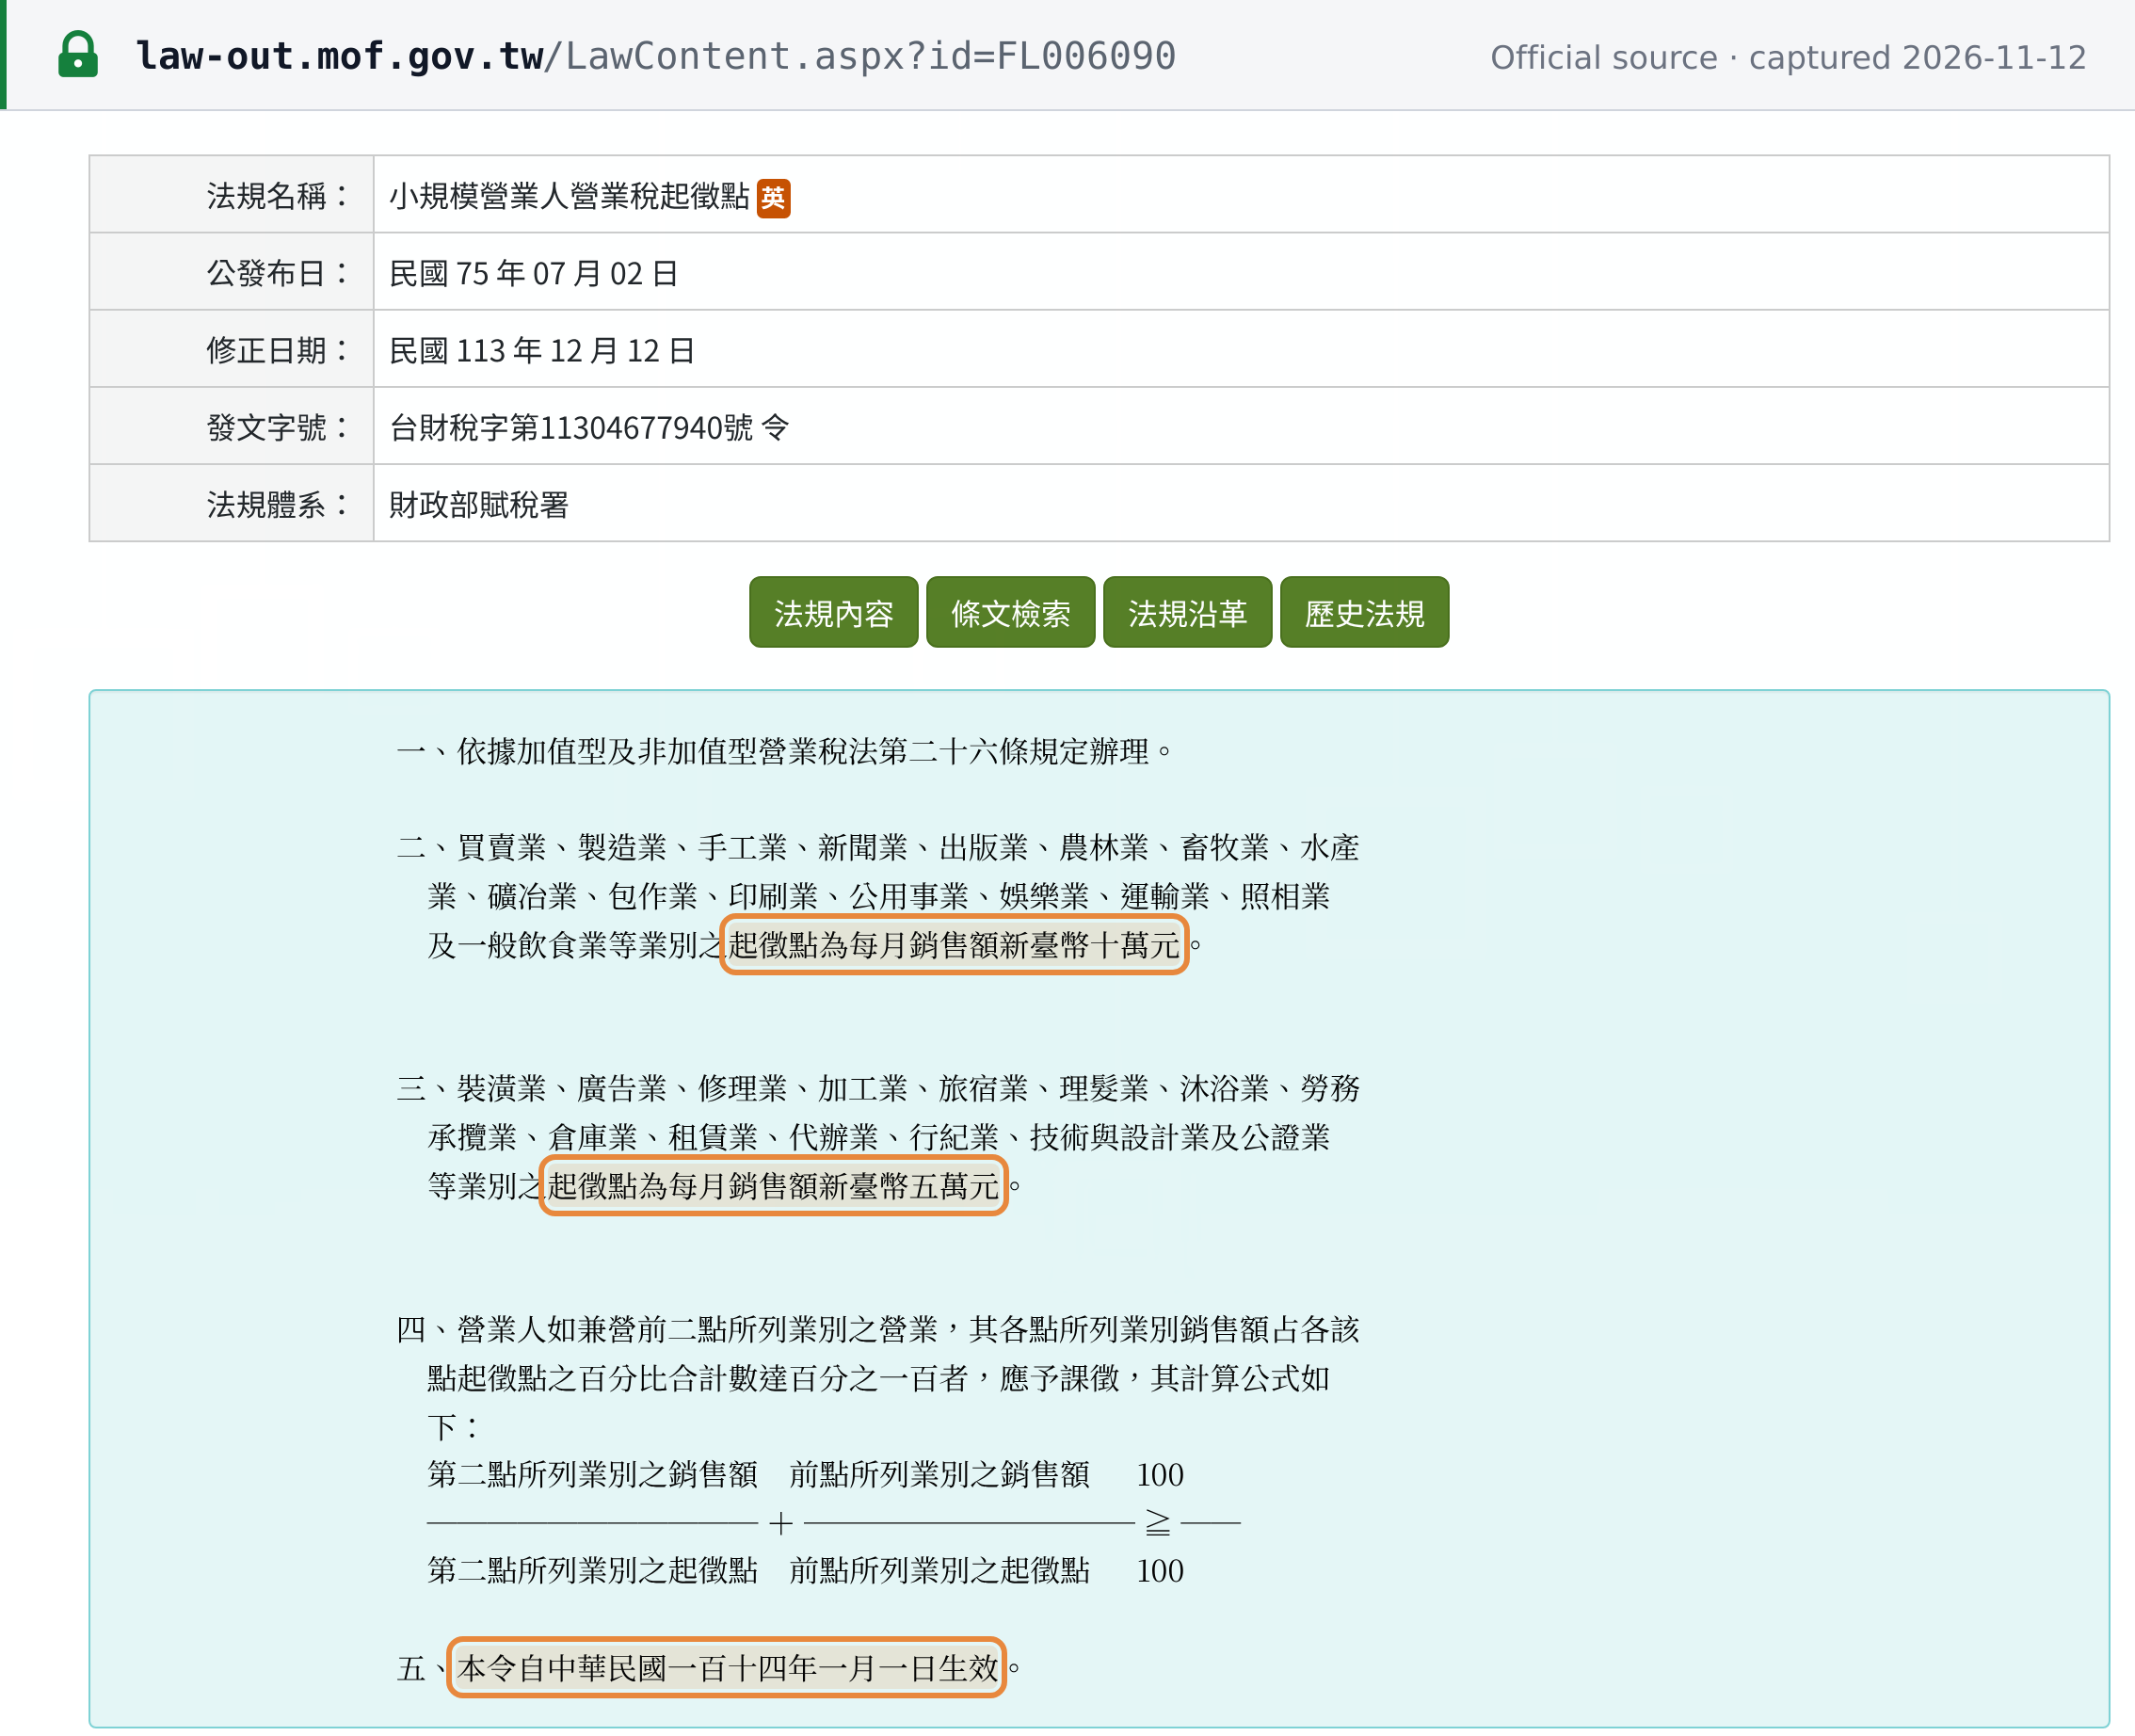 Source snapshot of the official page. Open full size ↗