Uganda treats free supplies from employers to employees as taxable for VAT from 1 July 2024
This page records one dated change. For the rules in Uganda as they stand today, see the Uganda guide →
- Jurisdiction
- Uganda
- Tax
- VAT
- Change type
- Update
- Status
- In force
- Impact
- FYI
- Announced
- 15 July 2024
- Effective
- 1 July 2024
- Instrument
- UG-ACT-Value-Added-Tax-Amendment-Act-2024
- Authority
- Parliament of Uganda
- Verified
- Fetched from official source · high confidence
VAT-registered employers in Uganda that provide goods or services to employees free of charge, such as meals, transport, accommodation or company products.
No action — monitoring only.
Uganda Value Added Tax (Amendment) Act, 2024 (assented 15 July 2024, effective 1 July 2024) added subsection (10) to section 18 of the VAT Act Cap. 349: the supply of goods or services by an employer who is a taxable person to an employee for no consideration is deemed a supply of goods or services for consideration as part of the employer's business activities, and is therefore a taxable supply subject to VAT.
What changed in detail
The Value Added Tax (Amendment) Act, 2024 was assented to by the President on 15 July 2024. Section 1 brings it into force on 1 July 2024, so it applies from a date two weeks before assent. Its long title describes this change as classifying the supply of goods or services by an employer to an employee at no consideration as a taxable supply.
Section 4 of the Act inserts a new subsection (10) into section 18 of the Value Added Tax Act, Cap. 349, immediately after subsection (9). Under it, a supply of goods or services by an employer who is a taxable person to an employee for no consideration is regarded as a supply for consideration made as part of the employer’s business activities.
The rule applies only to employers who are taxable persons, that is, registered for VAT. It does not say how the value of such a deemed supply is to be measured; that is left to the valuation rules in the principal Act.
What it means
Before July 2024 a free benefit given to staff could fall outside VAT because no consideration was paid. Since then, a VAT-registered employer providing free goods or services to employees must account for output VAT on them as if they had been sold.
The provision is in the 2024 Act as published by Parliament; the weekly feed records no later change to it. Uganda amends its VAT Act most years, so check the current consolidated text before relying on the subsection number or wording.
Proof
“(10) The supply of goods or services by an employer who is a taxable person, to an employee for no consideration, shall be regarded as the supply of goods or services for consideration as part of the employer’s business activities.”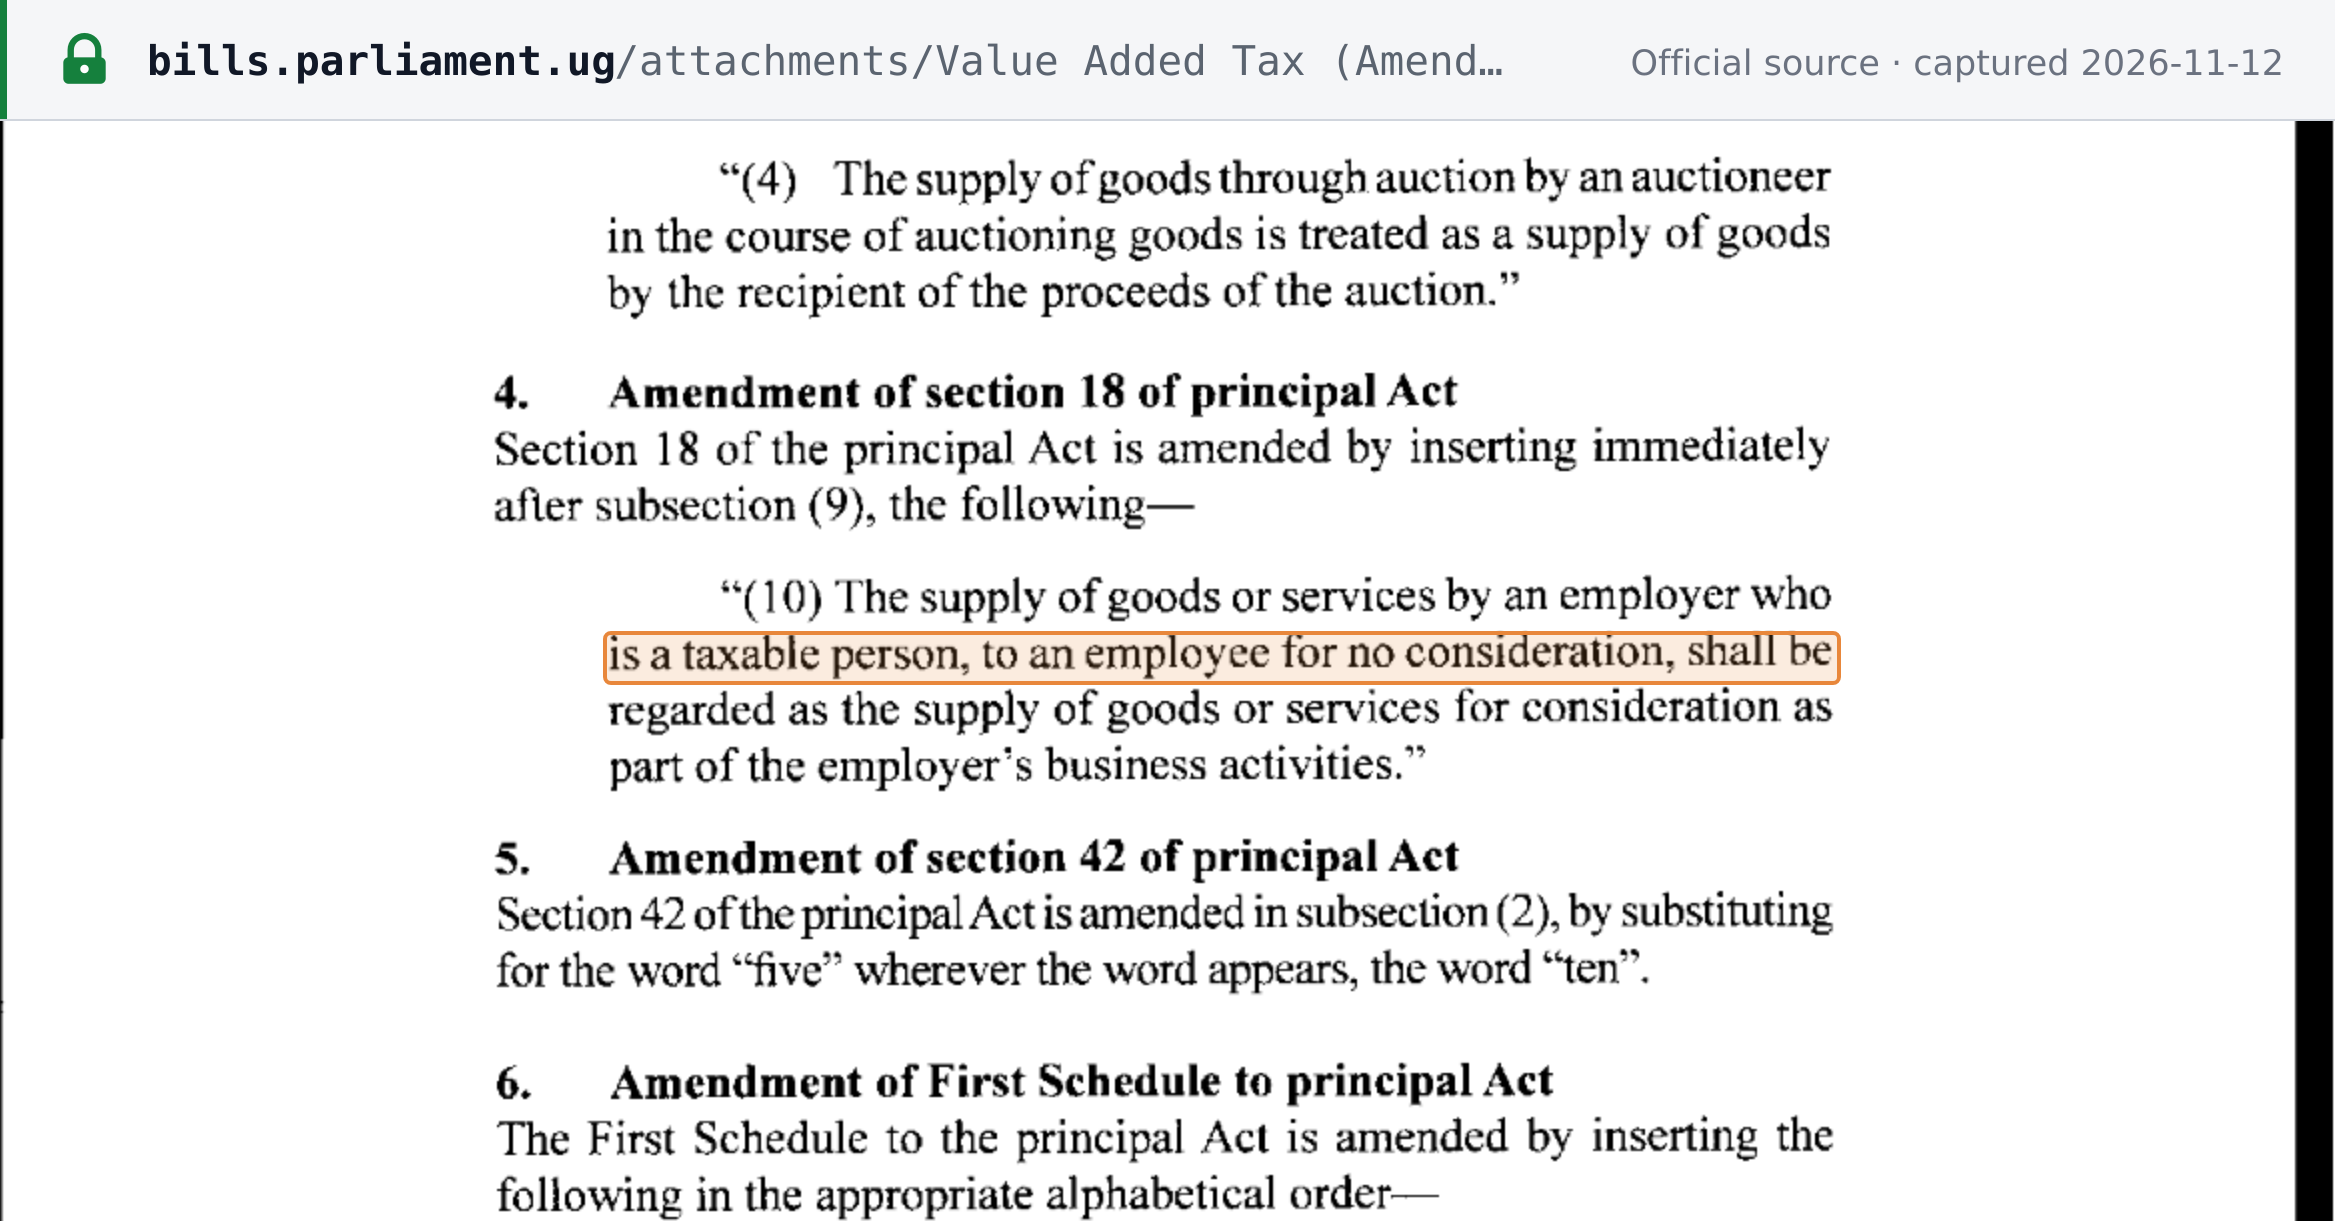 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · The Value Added Tax (Amendment) Act, 2024 (Uganda), assented 15 July 2024; scanned authenticated copy published by the Parliament of Uganda · bills.parliament.ug