UAE switches VAT and excise late-payment penalties to 14% a year and cuts several fixed fines from 14 April 2026
This page records one dated change. For the rules in United Arab Emirates as they stand today, see the United Arab Emirates guide →
- Jurisdiction
- United Arab Emirates
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- Plan ahead
- Announced
- 9 October 2025
- Effective
- 14 April 2026
- Instrument
- AE-CABINET-DECISION-129-2025
- Authority
- UAE Ministry of Finance
- Verified
- Fetched from official source · high confidence
Persons registered for UAE VAT or Excise Tax, their legal representatives, and anyone paying tax late or correcting a return by voluntary disclosure.
Since 14 April 2026, late VAT and excise payments accrue 14% per annum, charged monthly, and voluntary disclosures 1% per month. Update penalty provisioning and file voluntary disclosures promptly.
Cabinet Decision No. 129 of 2025, issued 9 October 2025 and effective 14 April 2026, amends the penalty tables of Cabinet Decision No. 40 of 2017, which apply to VAT and Excise Tax. Late payment of payable tax, and failure to calculate tax on behalf of another person, now attract a monthly penalty of 14% per annum on the unpaid amount; a voluntary disclosure attracts 1% of the tax difference per month; the penalty for not providing records in Arabic falls from AED 20,000 to AED 5,000; for not notifying changes to the tax record, to AED 1,000 (AED 5,000 if repeated within 24 months); and for a legal representative's late notice of appointment, from AED 10,000 to AED 1,000.
What changed in detail
Cabinet Decision No. 129 of 2025, issued on 9 October 2025 and effective 14 April 2026, amends the penalty tables in Cabinet Decision No. 40 of 2017 on administrative penalties for violations of the UAE tax laws. Those tables apply to both VAT and Excise Tax. The FTA announced the entry into force on 15 April 2026.
The consolidated tables now provide:
- Late payment of payable tax (Table 1, row 9): a monthly penalty of 14% per annum on the unsettled amount, for each month or part of a month, from the day after the due date. For a voluntary disclosure or a tax assessment, payment falls due 20 business days after submission or receipt.
- Failure to calculate tax on behalf of another person (row 14): the same 14% per annum, charged monthly.
- Voluntary disclosure of errors in a return, assessment or refund application (row 11): 1% of the tax difference per month or part of a month.
According to the FTA’s announcement:
- failure to provide records and documents in Arabic on request falls from AED 20,000 to AED 5,000;
- failure to notify changes to the tax record falls from AED 5,000, or AED 10,000 if repeated, to AED 1,000, or AED 5,000 if repeated within 24 months;
- a legal representative’s late notice of appointment falls from AED 10,000 to AED 1,000, payable from the representative’s own funds.
What it means
The Decision is in force. The FTA’s November 2025 consolidation of Cabinet Decision No. 40 of 2017 is the current published text, and no later amendment has been found.
The late-payment penalty now behaves like an interest charge instead of a step penalty, so the cost grows with the delay and the amount due. Voluntary disclosure is cheap at 1% a month, which rewards early correction: a business that finds an error should disclose before the FTA notifies an audit, because row 12 imposes a fixed 15% penalty plus a monthly charge on errors not disclosed by then. Penalty provisioning models built on the old figures need updating for periods from 14 April 2026.
Proof
The Authority explained that, under the amendments, the administrative penalty for the failure to submit data, records and tax-related documents in Arabic to the Authority when requested has been reduced from AED 20,000 to AED 5,000.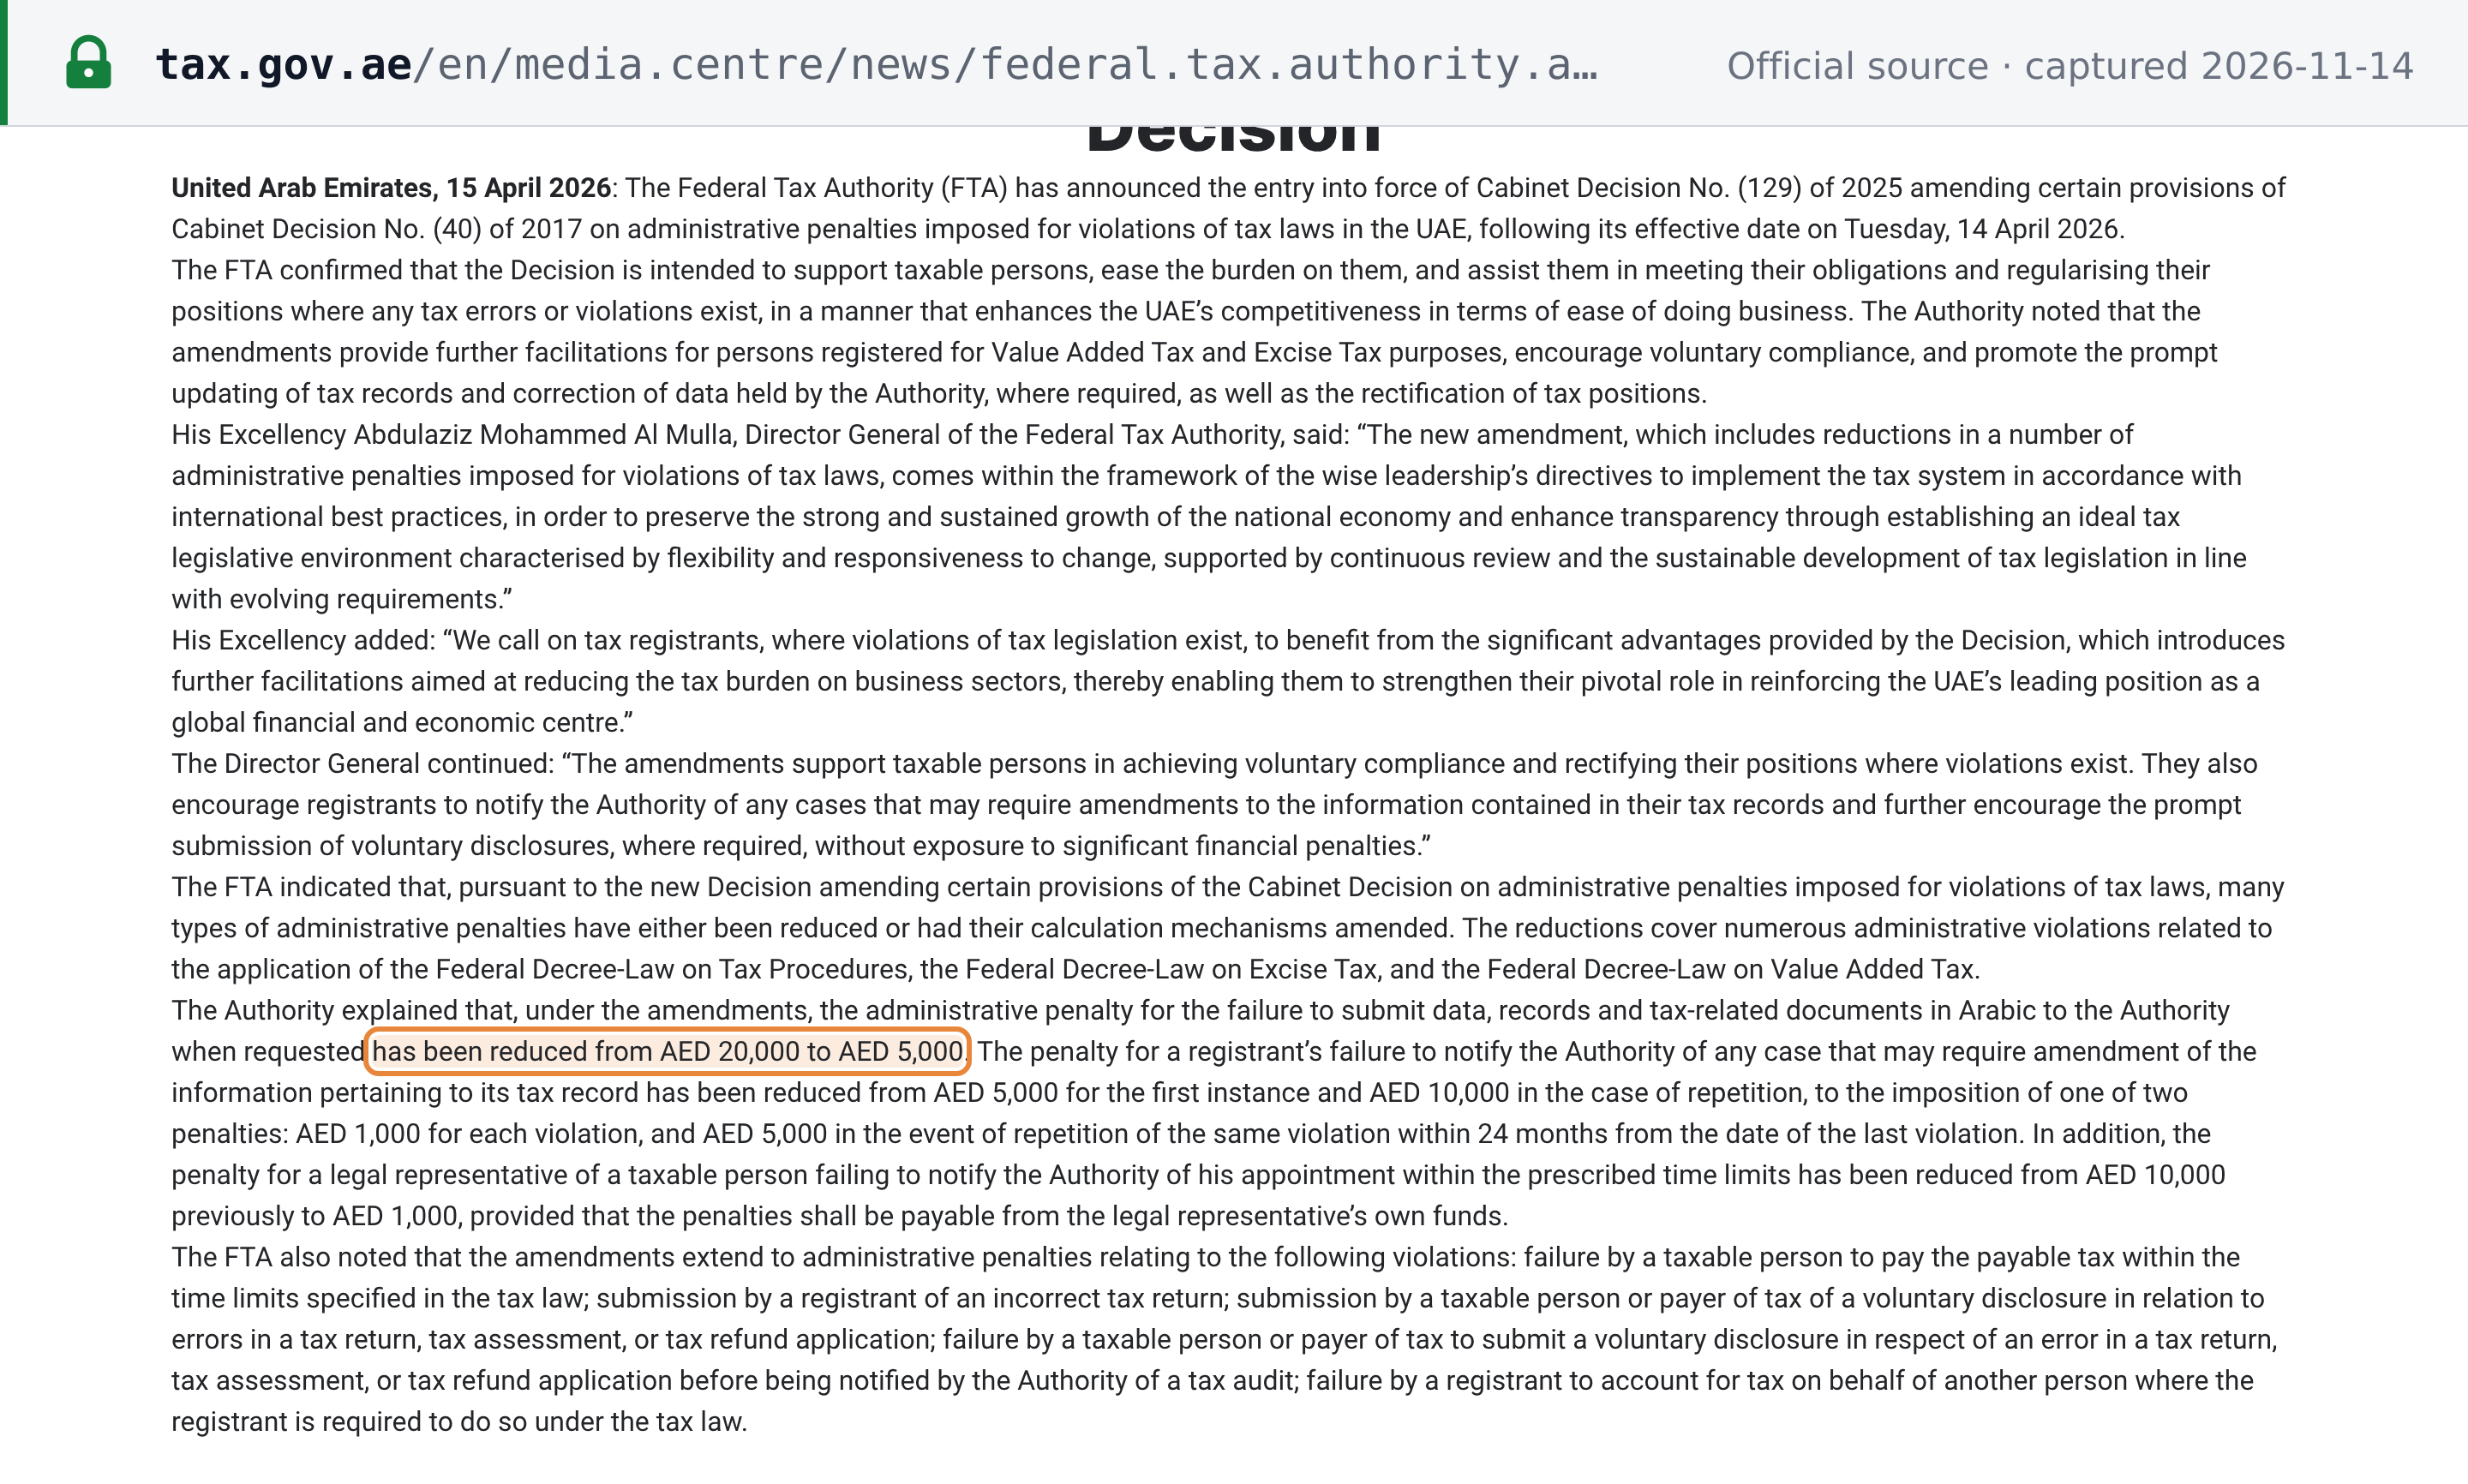 Source snapshot of the official page. Open full size ↗
A monthly penalty of (14%) per annum, for each month or part thereof, imposed on the unsettled Payable Tax amount from the day following the due date of payment and on the same date monthly thereafter.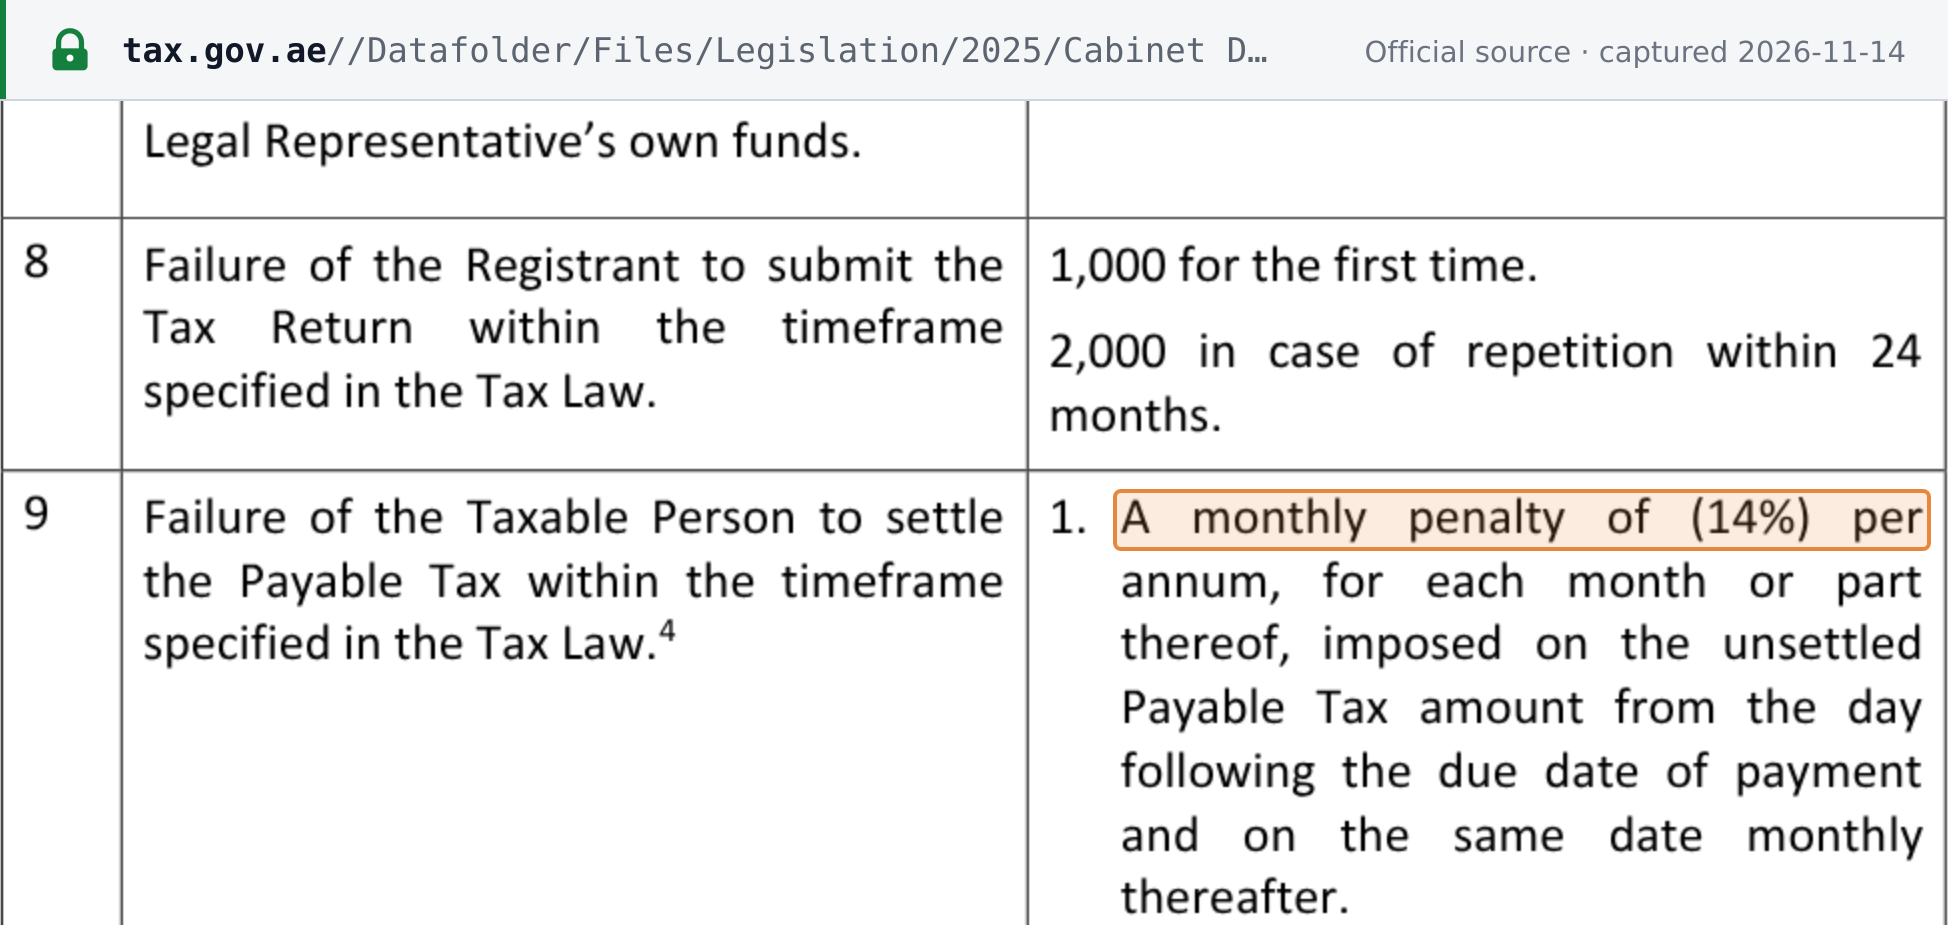 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Cabinet Decision No. 40 of 2017 and its amendments, consolidated to Cabinet Decision No. 129 of 2025 – Issued 9 Oct 2025 – (Effective from 14 April 2026); Table 1 row 9; English text marked "This is not an official Translation" · tax.gov.ae