UK ends the VAT exemption for private school fees from 1 January 2025
This page records one dated change. For the rules in United Kingdom as they stand today, see the United Kingdom guide →
- Jurisdiction
- United Kingdom
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 20 March 2025
- Effective
- 1 January 2025
- Instrument
- GB-ACT-2025-c-8
- Authority
- The National Archives (legislation.gov.uk) / HM Treasury
- Verified
- Fetched from official source · high confidence
Private schools in the UK charging fees for full-time education, vocational training or closely related boarding, and the parents who pay them.
No action — monitoring only. Private schools have been charging 20% VAT on fees since 1 January 2025.
Finance Act 2025 (c. 8), Royal Assent 20 March 2025, section 47 inserts a new Part 3 (Exceptions) into Schedule 9 of the Value Added Tax Act 1994. It removes the VAT exemption for education provided by a private school (except teaching English as a foreign language, nursery-class education and higher-education courses), vocational training provided by a private school, and closely related board and lodging, so these supplies are standard-rated at 20%. Under section 49 the change is treated as in force from 30 October 2024 and has effect for education, training and board and lodging provided on or after 1 January 2025. Section 48 catches fees paid in advance: a payment received on or after 29 July 2024 and before 30 October 2024 for a term is treated as a supply made on the later of 1 January 2025 and the first day of that term (approved non-maintained special schools are excluded).
What changed in detail
Section 47 of the Finance Act 2025 (c. 8), which received Royal Assent on 20 March 2025, inserts a new Part 3 (Exceptions) into Schedule 9 of the Value Added Tax Act 1994. Supplies listed in Part 3 are taken out of the education exemption and so are standard-rated at 20%:
- education provided by a private school, except teaching English as a foreign language, education in a nursery class and higher-education courses;
- vocational training provided by a private school;
- board and lodging closely related to either of those.
Section 49 treats sections 47 and 48 as in force from 30 October 2024. They have effect for education, training and board and lodging provided on or after 1 January 2025.
Section 48 covers fees paid in advance. Where a payment for education services in a school term is received on or after 29 July 2024 and before 30 October 2024, those services are treated as supplied on the later of 1 January 2025 and the first day of that term. Schools approved as non-maintained special schools under section 342 of the Education Act 1996 are excluded from this rule.
What it means
This change is still in force. legislation.gov.uk shows Schedule 9, Part 3, unamended, with no outstanding effects.
The Act received Royal Assent after the rule had already started to apply. Schools charged VAT from 1 January 2025 on the basis of a Bill, which section 49 then made retrospective to 30 October 2024. The section 48 date of 29 July 2024 is when the policy was announced. That date stops fees for 2025 terms from escaping VAT by being prepaid early.
Proof
The provision of education by a private school, other than— (a)the provision of the teaching of English as a foreign language, (b)the provision of education in a nursery class, or (c)the provision of a higher education course.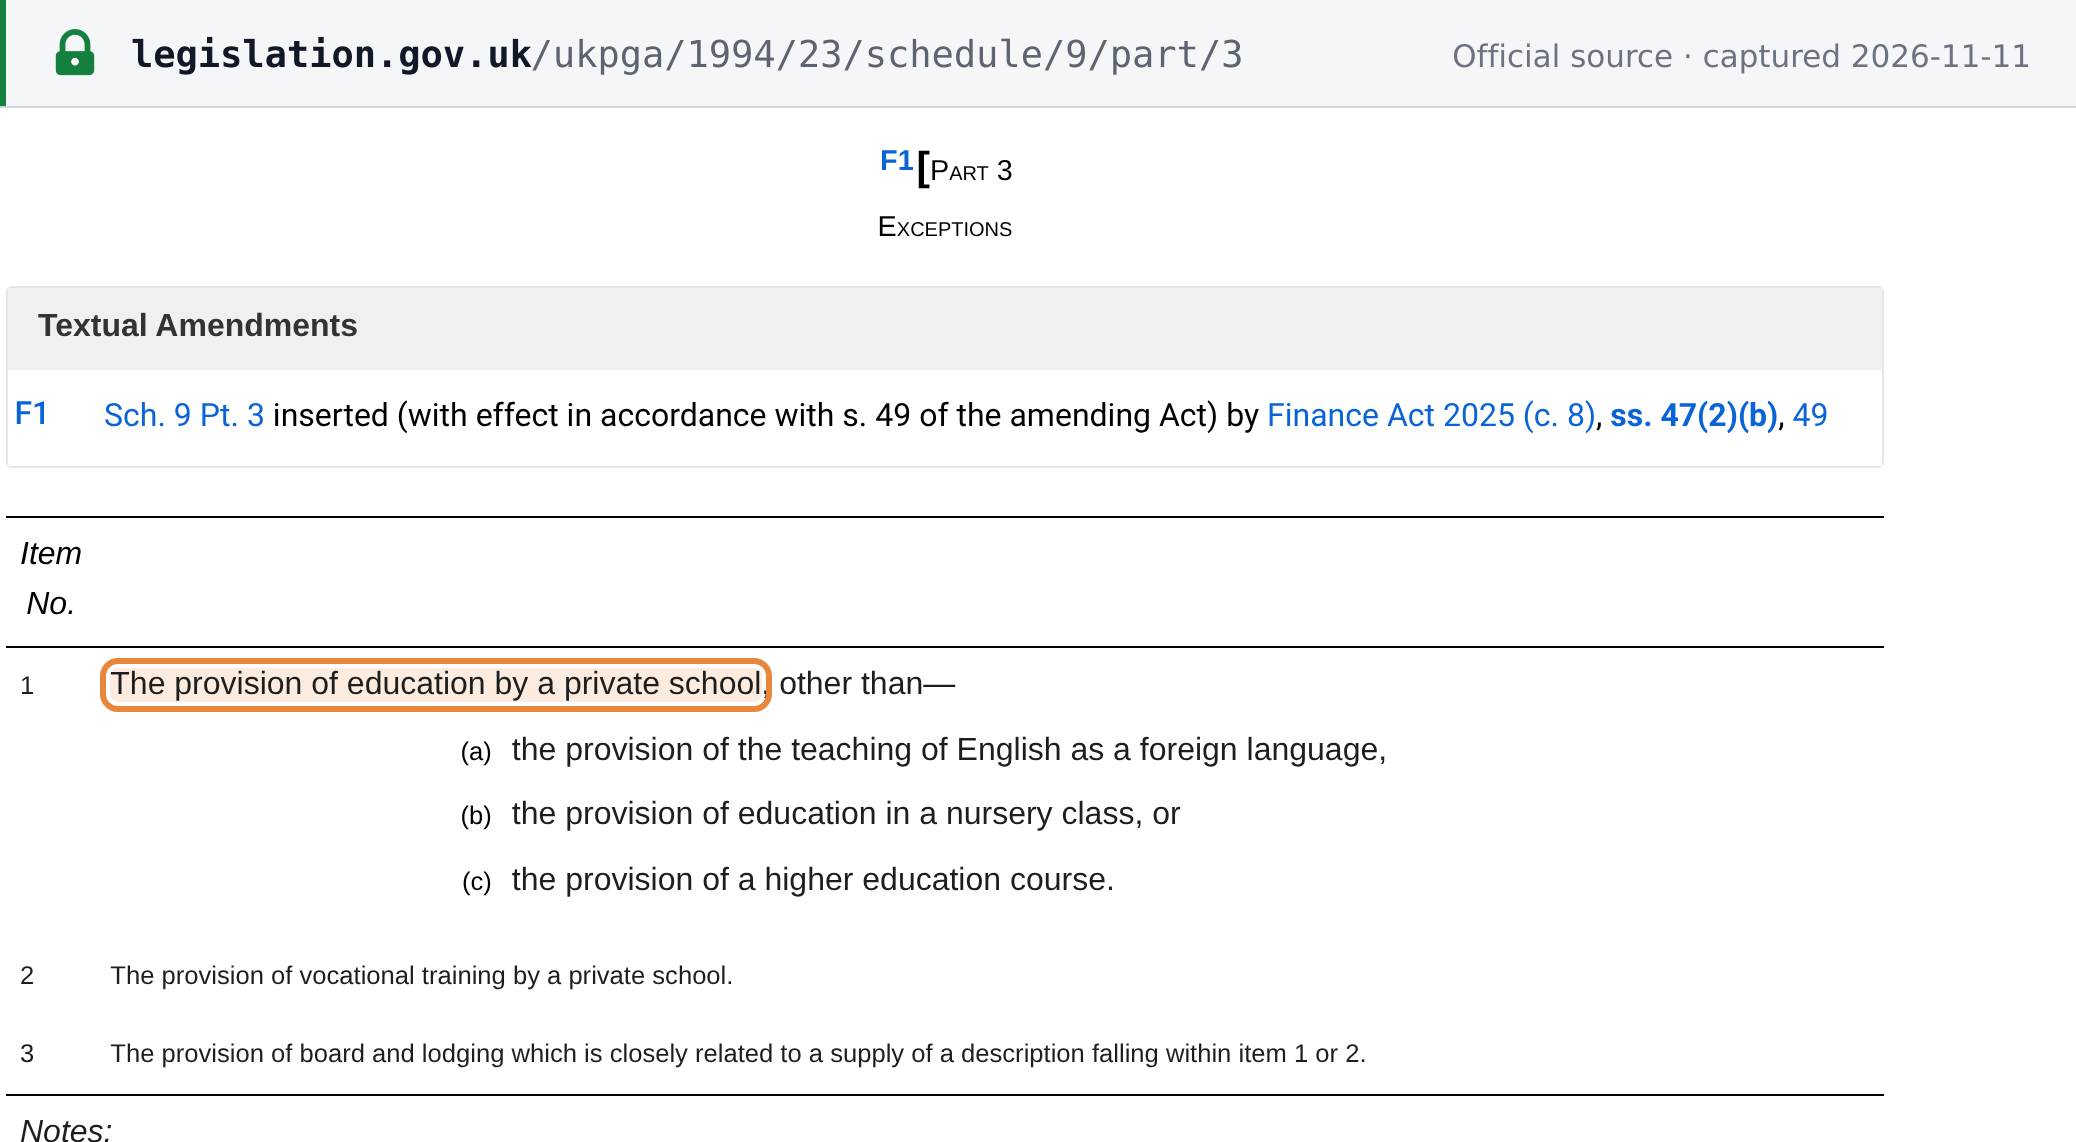 Source snapshot of the official page. Open full size ↗