UK raises the VAT registration threshold to £90,000 and deregistration to £88,000
This page records one dated change. For the rules in United Kingdom as they stand today, see the United Kingdom guide →
- Jurisdiction
- United Kingdom
- Tax
- VAT
- Change type
- Threshold
- Status
- In force
- Impact
- FYI
- Announced
- 5 March 2024
- Effective
- 1 April 2024
- Instrument
- GB-STATUTORY-INSTRUMENT-SI-2024-307
- Authority
- The National Archives (legislation.gov.uk) / HM Treasury
- Verified
- Fetched from official source · high confidence
UK-established businesses with taxable turnover near £90,000, and businesses in Northern Ireland acquiring goods from EU member states.
No action — monitoring only. The £90,000 registration threshold and £88,000 deregistration threshold have been in force since 1 April 2024.
The Value Added Tax (Increase of Registration Limits) Order 2024 (SI 2024 No. 307), made 5 March 2024 and in force 1 April 2024, raises the UK VAT registration threshold from £85,000 to £90,000 and the deregistration threshold from £83,000 to £88,000 for taxable supplies. The same order raises the Northern Ireland acquisition thresholds from £85,000 to £90,000.
What changed in detail
The Value Added Tax (Increase of Registration Limits) Order 2024 (SI 2024/307) was made on 5 March 2024 and came into force on 1 April 2024. Article 2 amends the Value Added Tax Act 1994:
- Schedule 1, paragraph 1(1) and (2): the registration threshold rises from £85,000 to £90,000. This covers both the backward-looking test (taxable supplies in the past 12 months) and the test on taking over a business as a going concern.
- Schedule 1, paragraphs 1(3) and 4: the deregistration threshold rises from £83,000 to £88,000.
- Schedule 9ZA, paragraphs 38 and 39: the Northern Ireland threshold for acquisitions of goods from EU member states rises from £85,000 to £90,000.
The registration threshold had been £85,000 since 1 April 2017. The forward-looking 30-day test, which applies when turnover in the next 30 days alone is expected to exceed the threshold, uses the same figure.
What it means
This change is still in force. legislation.gov.uk shows £90,000 in Schedule 1, paragraph 1, of the Value Added Tax Act 1994, and lists no outstanding effects on that paragraph. No later order has changed either the registration or the deregistration figure.
The rise ended a seven-year freeze. A business with turnover between £85,000 and £90,000 that had registered only because of the old limit could apply to deregister once its expected turnover fell below £88,000. Registration is still compulsory for anyone whose rolling 12-month taxable turnover goes over £90,000.
Proof
(a)in paragraph 1(1)(a), (1)(b), (2)(a) and (2)(b), for “£85,000” substitute “£90,000”;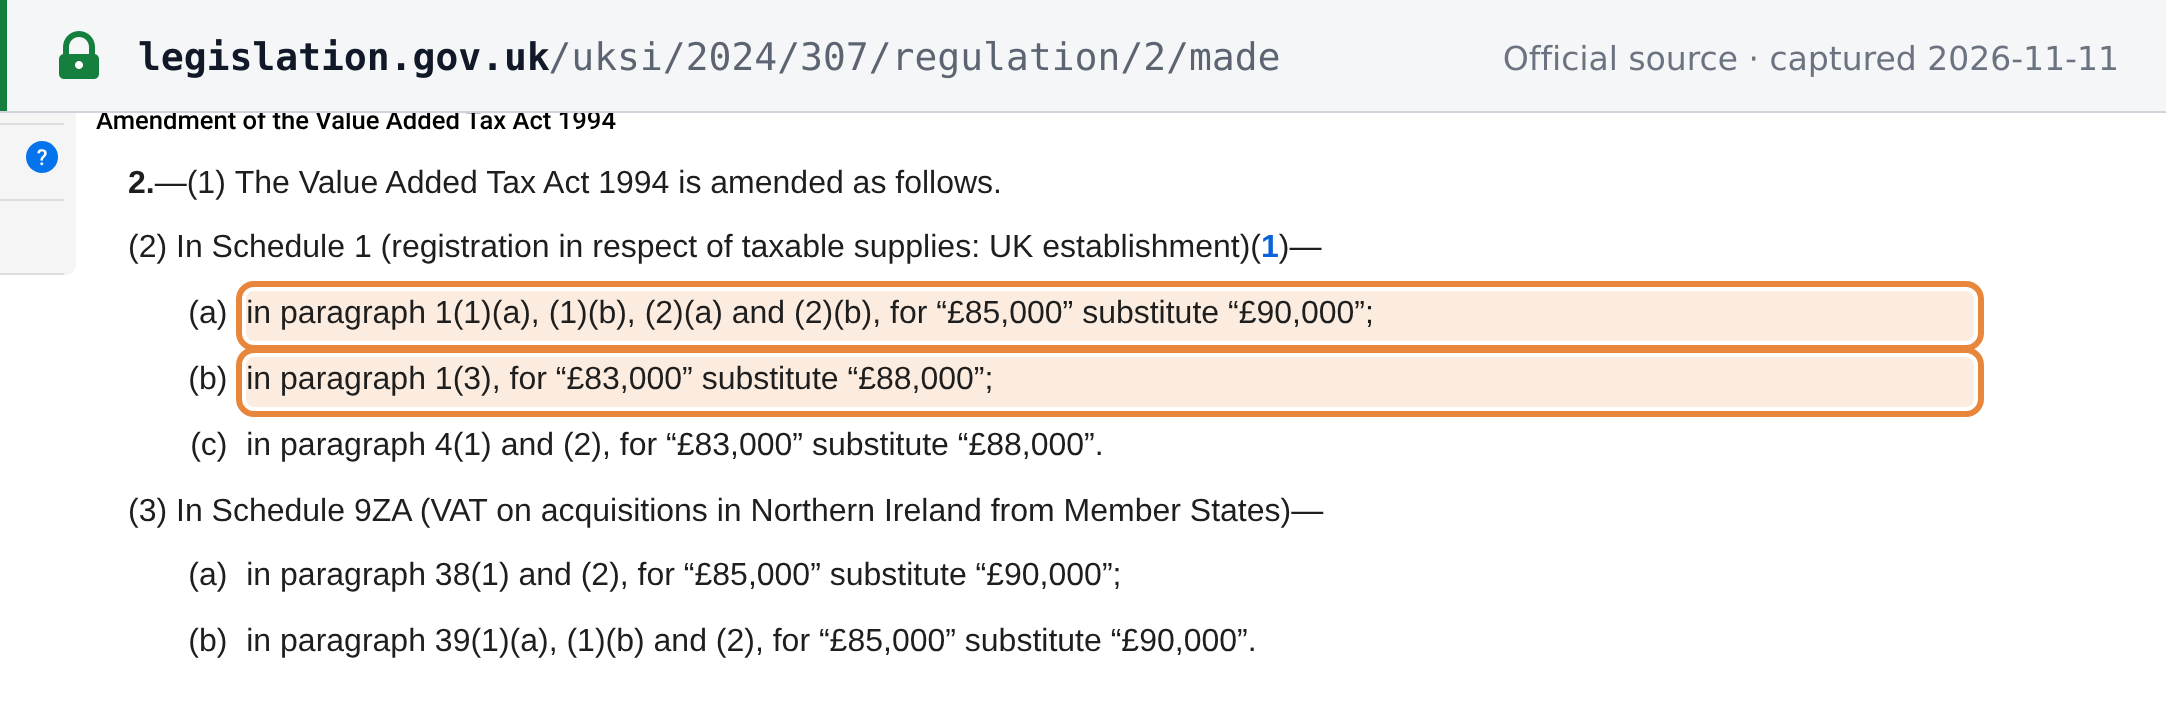 Source snapshot of the official page. Open full size ↗