Wyoming drops the 200-transaction test from its remote-seller nexus rule
- Jurisdiction
- United States — Wyoming
- Tax
- sales-tax
- Change type
- Threshold
- Status
- In force
- Impact
- FYI
- Announced
- 8 March 2024
- Effective
- 1 July 2024
- Instrument
- US-ACT-HB-197
- Authority
- Wyoming Legislature
- Verified
- Fetched from official source · high confidence
Remote sellers with no physical presence in Wyoming, in particular low-value, high-volume sellers that were registered only because of 200 or more transactions.
No action — monitoring only.
Wyoming House Bill 197 (2024 Budget Session; Enrolled Act No. 38, 2024 Session Laws ch. 67), signed by Governor Gordon on March 8, 2024, repealed W.S. 39-15-501(a)(ii), the 200-separate-transaction prong of Wyoming's remote-seller economic nexus test, effective July 1, 2024. The only remaining trigger is gross revenue above USD 100,000 from sales of tangible personal property, admissions or services delivered into Wyoming in the current or immediately preceding calendar year.
What changed in detail
Wyoming House Bill 197 (2024 Budget Session) became Enrolled Act No. 38 (2024 Session Laws ch. 67) when Governor Gordon signed it on 8 March 2024. It repealed W.S. 39-15-501(a)(ii), the second prong of Wyoming’s economic nexus test for remote sellers. That prong had required a seller to collect and remit Wyoming sales tax if it made 200 or more separate transactions into the state. Section 2 of the Act repeals the provision outright, and Section 3 makes the Act effective on 1 July 2024.
Only the revenue prong remains. A remote seller must register and collect if its gross revenue from sales of tangible personal property, admissions or services delivered into Wyoming exceeds USD 100,000 in the current or immediately preceding calendar year. The enrolled text also deletes the “or” that joined the two prongs.
Section 2 also repeals two other provisions: W.S. 39-15-105(a)(viii)(O)(I) and (II), and 39-15-105(b). Those repeals are not part of the nexus change.
What it means
The change is in force and has not been reversed. It is part of a wider retreat from transaction-count tests. Indiana dropped its 200-transaction test five days later, and Utah and Illinois followed.
A seller that registered only because of the transaction count and stays below USD 100,000 no longer meets the test. Because the test looks back to the prior calendar year as well, it should check both years before closing its Wyoming account.
Proof
W.S. 39-15-105(a)(viii)(O)(I), (II) and (b) and 39-15-501(a)(ii) are repealed.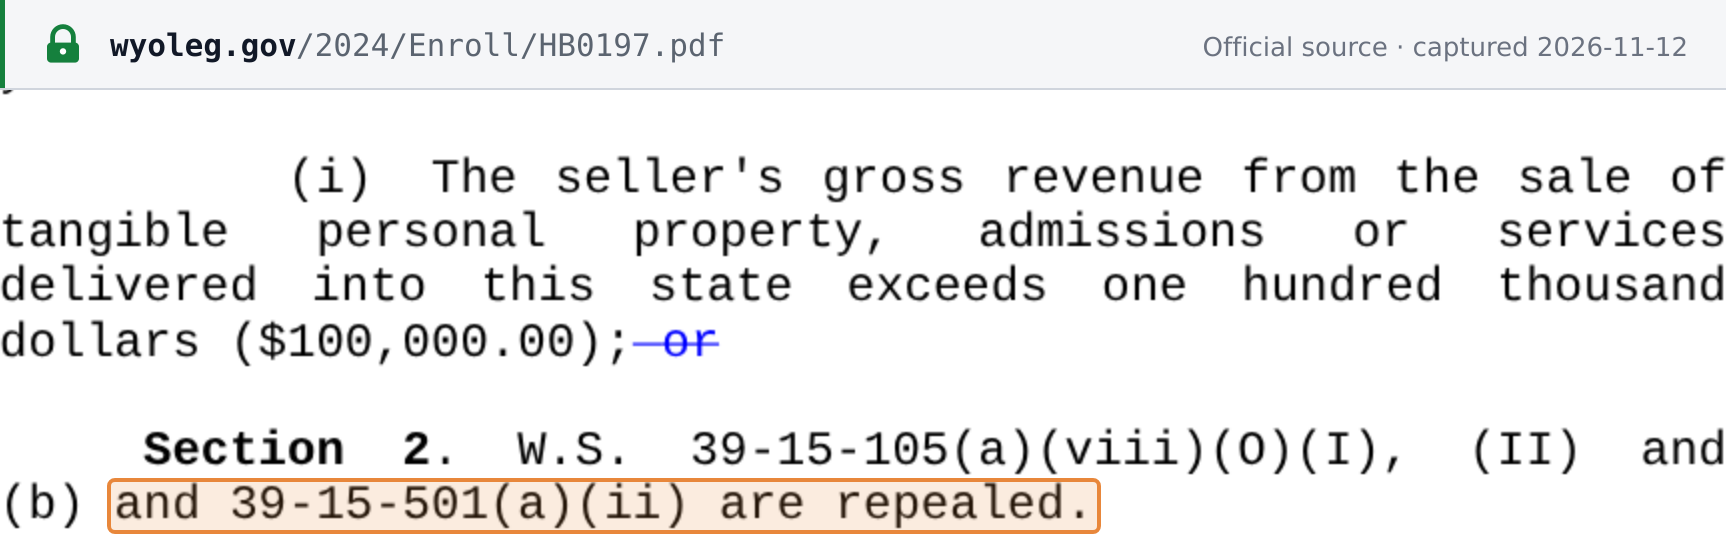 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Wyoming Enrolled Act No. 38 (Original House Bill No. HB0197), 2024 Budget Session · wyoleg.gov