Austria bars the margin scheme for works of art bought or imported at a reduced VAT rate from 2025
This page records one dated change. For the rules in Austria as they stand today, see the Austria guide →
- Jurisdiction
- Austria
- Tax
- VAT
- Change type
- Update
- Status
- In force
- Impact
- FYI
- Announced
- 19 July 2024
- Effective
- 1 January 2025
- Authority
- Rechtsinformationssystem des Bundes (RIS)
- Verified
- Fetched from official source · high confidence
Art dealers and other resellers in Austria who elect to apply the margin scheme to works of art they import or buy from artists or non-resellers (the election for imported collectors' items and antiques has been removed).
Art dealers who opt into the margin scheme for works of art should check each acquisition: where the 13% reduced rate applied (for example on an import or on a purchase from the artist), the margin scheme cannot be used for that item and the full sale price is taxed. Imported collectors' items and antiques can no longer be put into the margin scheme by election.
The Abgabenänderungsgesetz 2024 (BGBl. I Nr. 113/2024, published 19 July 2024), implementing Directive (EU) 2022/542, replaced § 24 Abs. 2 UStG 1994 with effect from 1 January 2025. A reseller can opt to apply the margin scheme to works of art only if no reduced VAT rate was applied to the supply to it or to its import, and the works were either imported by it, supplied by the creator or the creator's successor, or not supplied by a reseller; the no-reduced-rate condition applies to all three routes. The option no longer covers collectors' items and antiques that the reseller imports, and § 24 Abs. 4 Z 3 was amended to match.
What changed in detail
Article 6 of the Abgabenänderungsgesetz 2024, published on 19 July 2024 as BGBl. I Nr. 113/2024, amended § 24 of the Umsatzsteuergesetz 1994, the margin scheme (Differenzbesteuerung) for second-hand goods, works of art, collectors’ items and antiques. It implements Directive (EU) 2022/542 and applies to supplies after 31 December 2024 (§ 28 Abs. 64).
The ordinary margin scheme for goods a reseller buys from someone who could not charge VAT is unchanged. The change is to the optional extension in § 24 Abs. 2:
- Before 2025, a reseller could elect the margin scheme for works of art, collectors’ items or antiques it imported itself and for works of art bought from the artist (or the artist’s successor), whatever rate had applied to the acquisition (imports and creator supplies of art are taxed at the reduced 13% rate). For works of art bought from a non-reseller the election was open only where the reduced 13% rate applied to that supply.
- From 2025, the election covers works of art only, and only where no reduced rate was applied to the supply to the reseller or to its import. That condition comes first and governs all three routes (own import, from the creator, from a non-reseller), so for purchases from non-resellers the reduced rate has turned from a requirement into a bar.
Collectors’ items and antiques were removed from § 24 Abs. 4 Z 3 to match, and a cross-reference to Anlage 2 was deleted from § 24 Abs. 1.
What it means
The restriction is still in force; § 24 has not been amended since.
In practice, an Austrian dealer who imports art or buys from the artist at the 13% reduced rate can no longer use the margin scheme for that piece and must charge VAT on the full selling price, with input VAT on the acquisition deductible instead. Imported collectors’ items and antiques can no longer be brought into the margin scheme by election at all. The EU-wide change targeted this combination of a low acquisition rate and a margin-only charge. The same law also changed the place of supply of virtual events.
Proof
Der Wiederverkäufer (Abs. 1 Z 1) kann erklären, dass er die Differenzbesteuerung auch bei der Lieferung von Kunstgegenständen anwendet, sofern bei der Lieferung an ihn oder bei der Einfuhr durch ihn kein ermäßigter Steuersatz angewandt wurde und die Gegenstände entwederThe reseller (para. 1 no. 1) may declare that it also applies the margin scheme to supplies of works of art, provided no reduced rate was applied to the supply to it or to its import and the goods were either
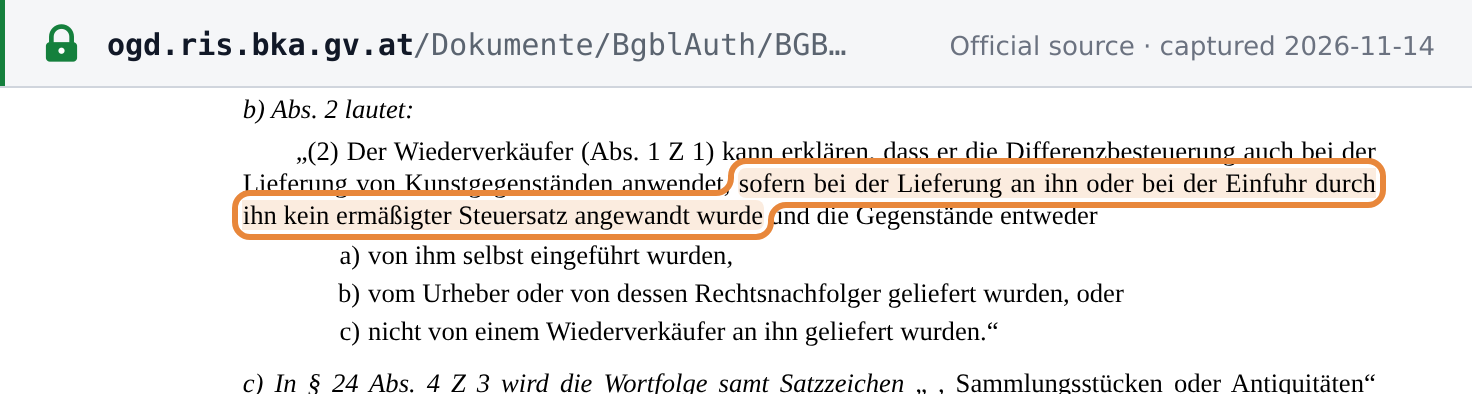 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · BGBl. I Nr. 113/2024 (Abgabenänderungsgesetz 2024), ausgegeben am 19. Juli 2024, Artikel 6 Z 7 (§ 24 Abs. 1, 2 und 4 UStG 1994) · ogd.ris.bka.gv.at