Belgium extends 6% VAT on demolition and rebuilding to homes let long-term to private tenants from 1 June 2024
This page records one dated change. For the rules in Belgium as they stand today, see the Belgium guide →
- Jurisdiction
- Belgium
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 29 May 2024
- Effective
- 1 June 2024
- Instrument
- BE-ACT-2024004641
- Authority
- SPF Finances (FPS Finance), Belgium
- Verified
- Fetched from official source · high confidence
Owners demolishing and rebuilding a dwelling of up to 200 m² to let it for at least 15 years to a natural person who lives there, and the contractors working on those projects.
No action: this version was replaced on 29 July 2025. The private long-term rental case (200 m², 15-year letting to a resident individual, prior electronic declaration) continues under the current rubric.
The Law of 12 May 2024 on miscellaneous tax provisions (Moniteur belge 29 May 2024, Numac 2024004641; erratum 8 July 2024), art. 114, replaces rubric XXXVII of Table A of Royal Decree No. 20 from 1 June 2024. On top of the two existing cases (a private owner's sole own home, and a dwelling let for 15 years through a social rental agency or social-housing body), a new §4 applies the 6% rate to demolition and joint reconstruction of a dwelling on the same cadastral parcel that the owner lets, for at least 15 years, to a natural person who makes it their domicile. The habitable area may not exceed 200 m², and the owner must send an electronic declaration before VAT becomes chargeable. The transitional deadline of 31 December 2024 for developer sales and for the pre-2024 urban-zone rubric was kept. The rubric was replaced again from 29 July 2025, keeping this rental case.
What changed in detail
Article 114 of the Law of 12 May 2024 on miscellaneous tax provisions (Moniteur belge 29 May 2024, Numac 2024004641; erratum 8 July 2024) replaces rubric XXXVII of Table A of Royal Decree No. 20. Under article 115 it applies from 1 June 2024.
The rubric already gave a 6% rate for demolishing a building and jointly rebuilding a dwelling on the same cadastral parcel in two cases: a private owner’s sole own home, and a dwelling let for at least 15 years through a social rental agency or social-housing body.
A new §4 adds a third case: a rebuilt dwelling that the owner lets for at least 15 years to a natural person who makes it their domicile. The conditions are:
- total habitable area of no more than 200 m²;
- an electronic declaration sent to the administration before the VAT becomes chargeable.
The transitional deadline of 31 December 2024 was kept for two groups: developer sales of rebuilt dwellings with a permit applied for before 1 July 2023, and projects under the pre-2024 urban-zone rubric.
What it means
This version of the rubric is no longer in force. The Law of 10 December 2024 moved its two transitional deadlines to 30 June 2025. The loi-programme of 18 July 2025 then replaced the rubric again from 29 July 2025.
The private-rental case survived that rewrite with the same 200 m² cap and 15-year letting condition. So the substance of this change still applies, but under the current text. Read it for projects where VAT became chargeable between 1 June 2024 and 28 July 2025. It sits between the January 2024 rewrite and the 2025 one.
Proof
Le taux réduit de 6 p.c. s’applique aux travaux immobiliers et autres opérations énumérées à la rubrique XXXI, § 3, 3° à 6°, ayant pour objet la démolition d’un bâtiment et la reconstruction conjointe d’un bâtiment d’habitation destiné à une location de longue durée et situé sur la même parcelle cadastrale que ce bâtiment.The reduced rate of 6 per cent applies to building work and other operations listed in heading XXXI, §3, 3° to 6°, consisting of the demolition of a building and the joint reconstruction of a residential building intended for long-term letting and located on the same cadastral parcel as that building.
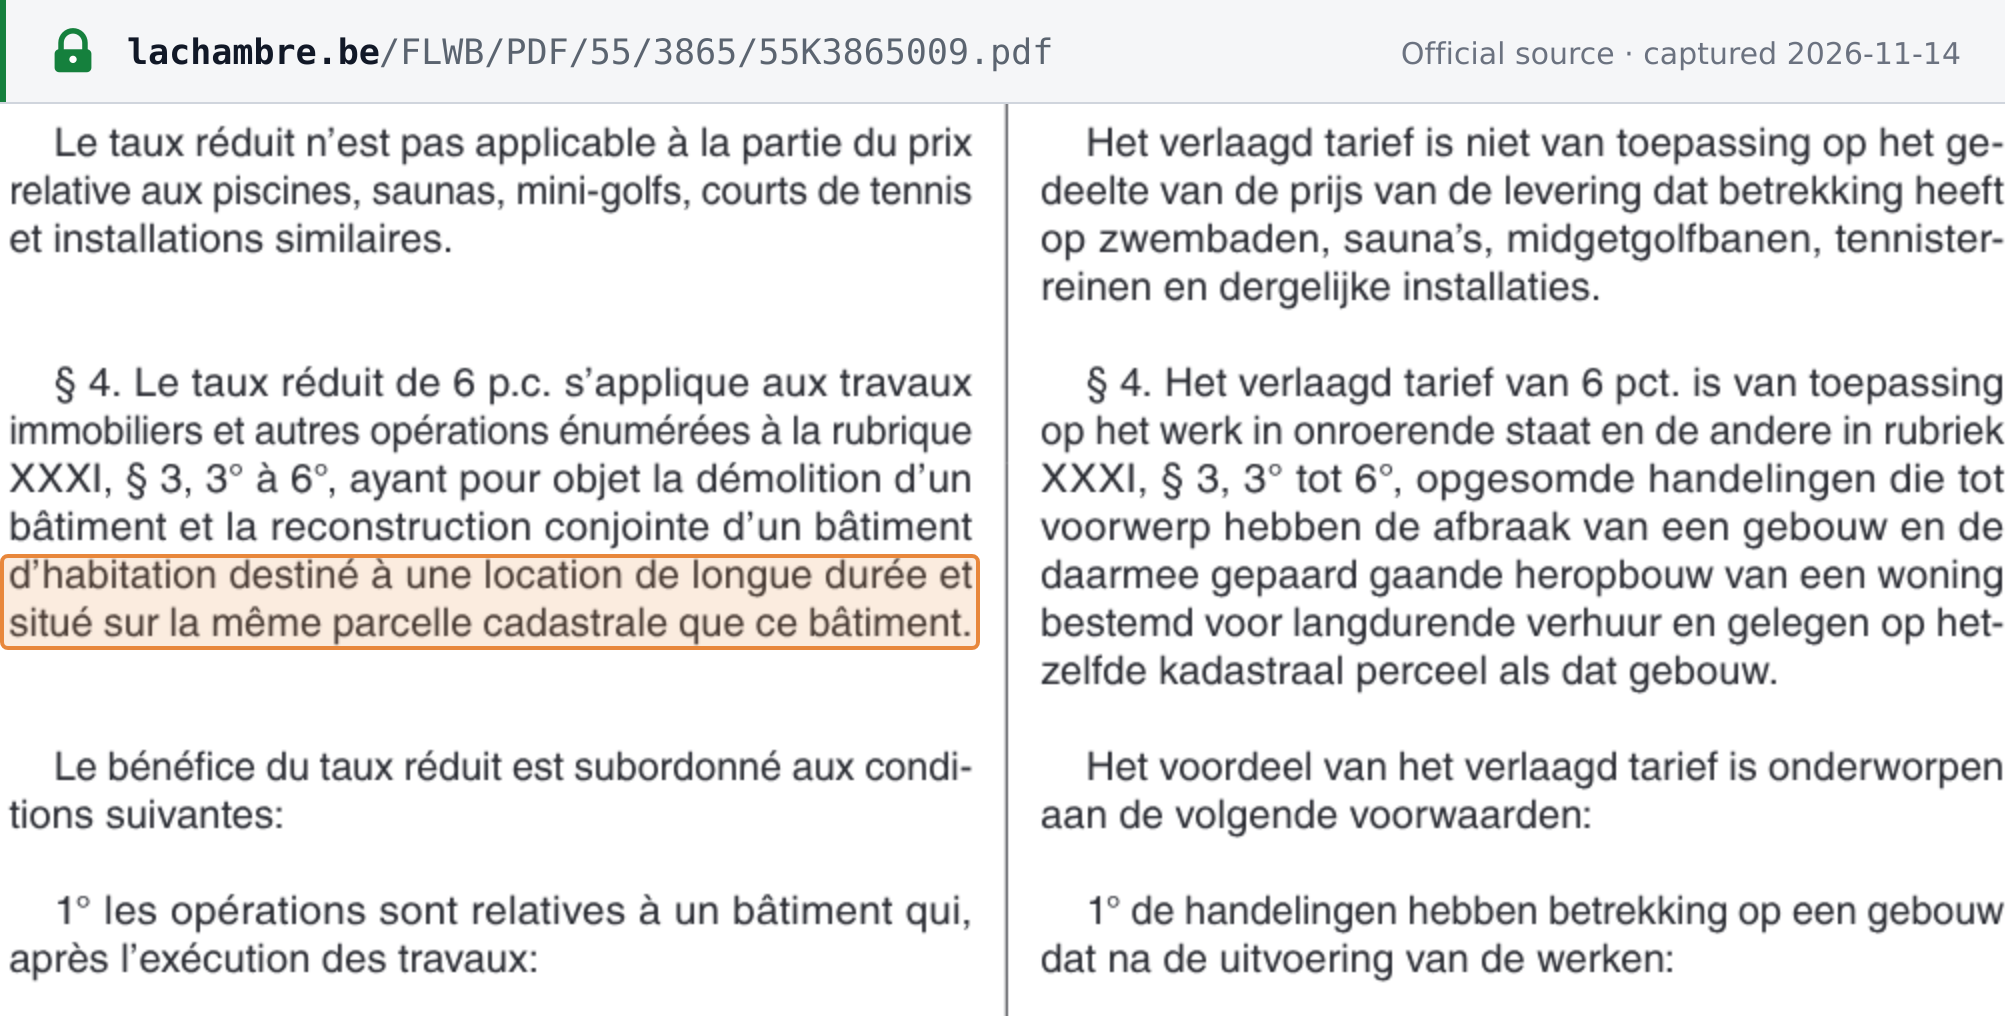 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Chambre des représentants, DOC 55 3865/009 (texte adopté en deuxième lecture; adopté tel quel en séance plénière, DOC 55 3865/011) · www.lachambre.be
Le taux réduit de six p.c. s'applique aux travaux immobiliers et autres opérations énumérées à la rubrique XXXI, § 3, 3° à six°, ayant pour objet la démolition d'un bâtiment et la reconstruction conjointe d'un bâtiment d'habitation destiné à une location de longue durée et situé sur la même parcelle cadastrale que ce bâtiment.The reduced rate of six per cent applies to building work and other operations listed in heading XXXI, §3, 3° to 6°, consisting of the demolition of a building and the joint reconstruction of a residential building intended for long-term letting and located on the same cadastral parcel as that building.
Archived from the official distribution · Fisconetplus 16e01673-d543-44be-86fe-b51a8a41abdf: TVA, AR n° 20, Annexe, Tableau A, Rubrique XXXVII (texte actuel et historique) · www.minfin.fgov.be