Belgium opens its small-business VAT franchise to businesses established elsewhere in the EU from 1 January 2025
This page records one dated change. For the rules in Belgium as they stand today, see the Belgium guide →
- Jurisdiction
- Belgium
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- Plan ahead
- Announced
- 9 April 2024
- Effective
- 1 January 2025
- Instrument
- BE-ACT-2024002757
- Authority
- SPF Finances (FPS Finance), Belgium
- Verified
- Fetched from official source · high confidence
Small businesses with Belgian turnover up to EUR 25,000, and businesses established in another EU Member State with EU turnover up to EUR 100,000 that supply in Belgium; VAT groups and certain sectors are excluded.
Small businesses with Belgian turnover up to EUR 25,000 can opt into the franchise by notifying SPF Finances. Businesses established elsewhere in the EU can use it in Belgium only through the SME notification in their home Member State (EU turnover up to EUR 100,000). Check the higher ceiling that applies from 1 January 2027.
The Law of 21 March 2024 (Moniteur belge 9 April 2024, Numac 2024002757) replaces art. 56bis and inserts arts. 56ter to 56undecies into the VAT Code from 1 January 2025, implementing the EU SME scheme of Directive (EU) 2020/285. Taxable persons established in Belgium with annual turnover in Belgium of no more than EUR 25,000 may use the VAT franchise after notifying the administration. Taxable persons established in another Member State may also use the Belgian franchise if their annual EU turnover does not exceed EUR 100,000 and their Belgian turnover does not exceed EUR 25,000; they must give prior notice to their Member State of establishment and use an identification number with the suffix 'EX'. VAT groups are excluded. So are taxable persons who habitually carry out construction work, make supplies requiring a cash-register receipt, or supply scrap and waste. The implementing order is Royal Decree No. 19 of 15 December 2024 (Moniteur belge 24 December 2024, Numac 2024011567).
What changed in detail
The Law of 21 March 2024 (Moniteur belge 9 April 2024, Numac 2024002757) replaces article 56bis and inserts articles 56ter to 56undecies into the Belgian VAT Code from 1 January 2025. It implements the EU SME scheme of Directive (EU) 2020/285.
Two groups can use the Belgian VAT franchise:
- businesses established in Belgium with annual turnover in Belgium of no more than EUR 25,000, after notifying the administration;
- businesses established in another Member State, if their annual turnover in the EU does not exceed EUR 100,000 and their Belgian turnover does not exceed EUR 25,000. They give prior notice to their own Member State of establishment and use an identification number carrying the suffix “EX”.
The EUR 25,000 domestic ceiling is not new; the cross-border route is. VAT groups cannot use the franchise. Nor can taxable persons who habitually carry out construction work, make supplies that require a cash-register receipt, or supply scrap and waste.
The implementing rules are in Royal Decree No. 19 of 15 December 2024 (Moniteur belge 24 December 2024, Numac 2024011567).
What it means
The regime is in force but has been amended twice. The Law of 10 February 2026 cut the ceiling pro rata for businesses that start during the year and requires notice before the franchise is used. The Law of 23 September 2026 raises the Belgian ceiling in steps, from EUR 26,000 in 2027 to EUR 30,000 from 2031.
The EU-wide EUR 100,000 ceiling for the cross-border route has not changed. A business in another Member State still enters the Belgian franchise only through its home administration’s SME notification, never by applying in Belgium directly.
Proof
Les assujettis établis en Belgique dont le chiffre d’affaires annuel réalisé en Belgique ne dépasse pas 25.000 euros, peuvent bénéficier du régime de la franchise de taxe pour les livraisons de biens et les prestations de services qu’ils effectuent en Belgique.Taxable persons established in Belgium whose annual turnover in Belgium does not exceed EUR 25,000 may use the VAT franchise scheme for the supplies of goods and services they make in Belgium.
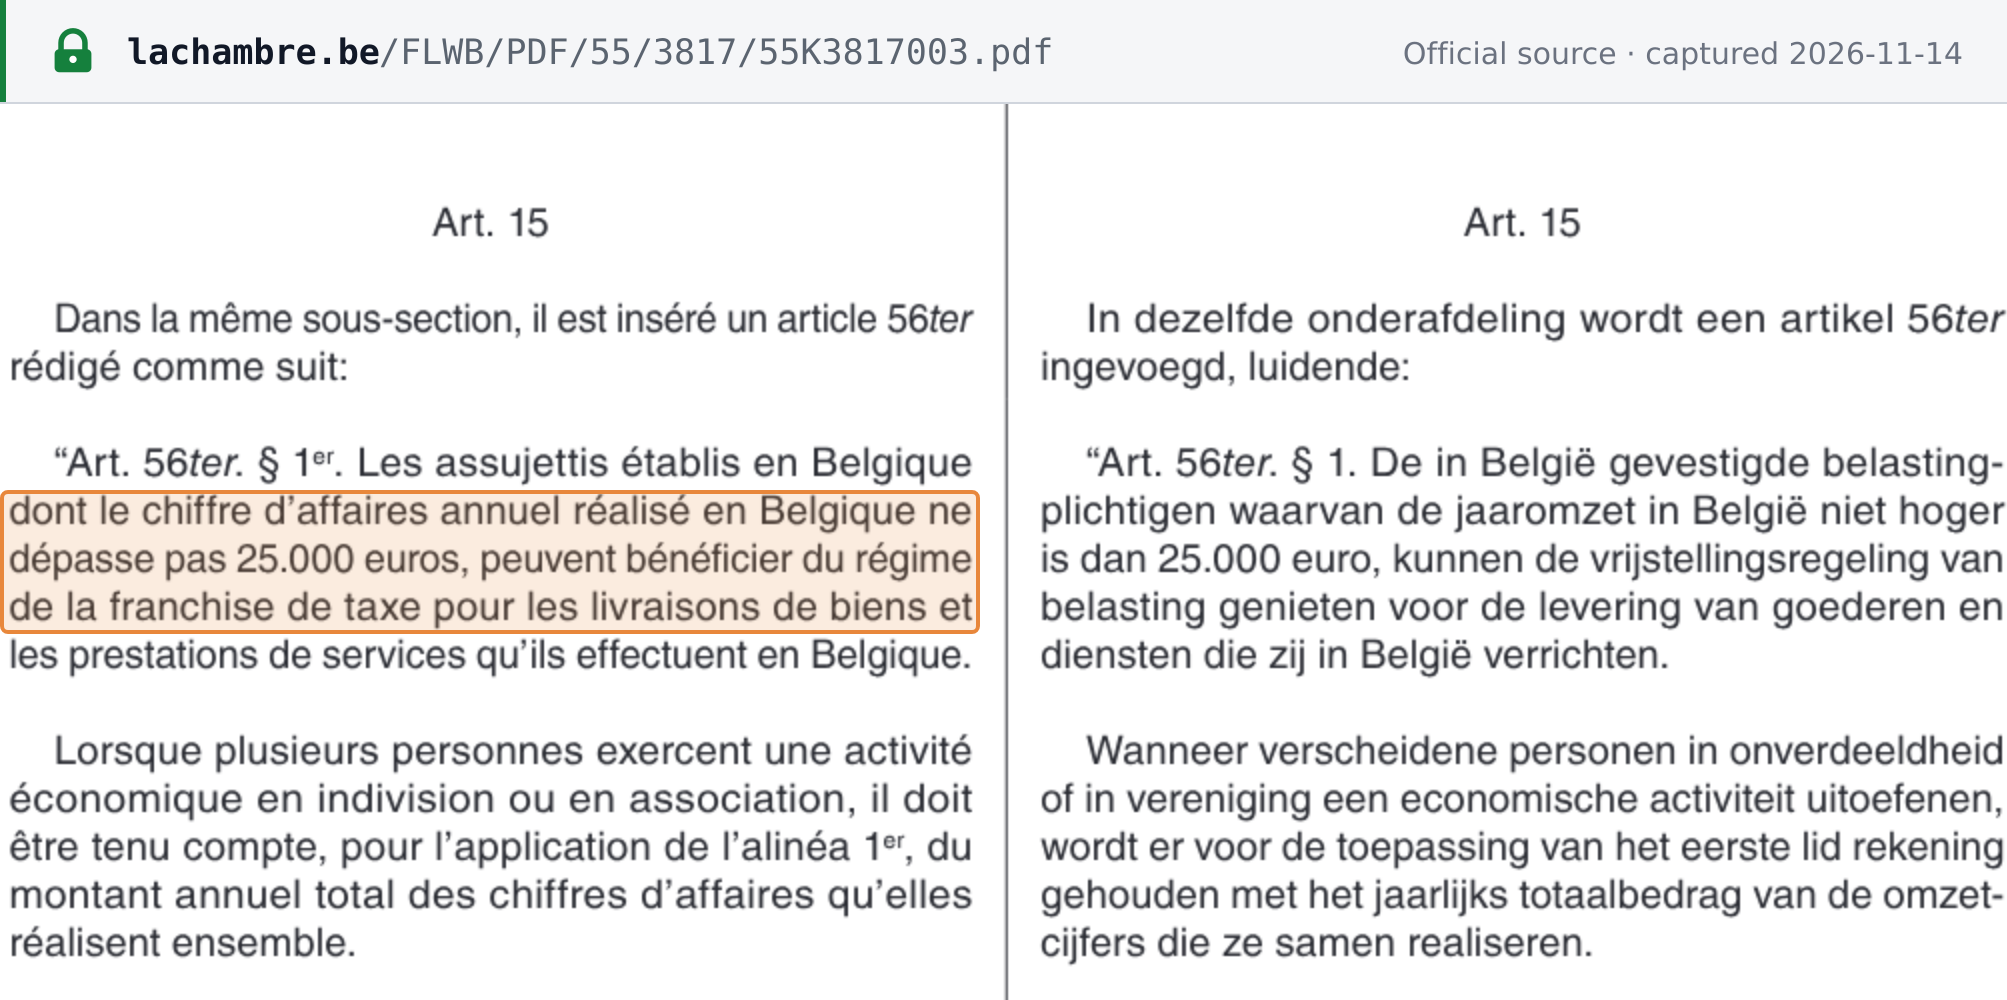 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Chambre des représentants, DOC 55 3817/003 (texte adopté par la commission; adopté tel quel en séance plénière, DOC 55 3817/004) · www.lachambre.be
Les assujettis établis en Belgique dont le chiffre d'affaires annuel réalisé en Belgique ne dépasse pas 25.000 euros, peuvent bénéficier du régime de la franchise de taxe pour les livraisons de biens et les prestations de services qu'ils effectuent en Belgique.Taxable persons established in Belgium whose annual turnover in Belgium does not exceed EUR 25,000 may use the VAT franchise scheme for the supplies of goods and services they make in Belgium.
Archived from the official distribution · Fisconetplus 2df474a0-20a4-48cc-911b-298afbc32486: Article 56ter, Code de la TVA (texte actuel et historique) · www.minfin.fgov.be