Brazil fixes the PIS/Cofins coefficient for non-fuel ethanol at 0.7552 (Decreto 12.525/2025)
This page records one dated change. For the rules in Brazil as they stand today, see the Brazil guide →
- Jurisdiction
- Brazil
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 25 June 2025
- Effective
- 25 June 2025
- Authority
- Imprensa Nacional — Diário Oficial da União
- Verified
- Fetched from official source · high confidence
Producers, importers and distributors selling non-fuel ethanol (etanol sem fins carburantes) under art. 5 of Lei 9.718/1998.
No action — monitoring only. Sellers of non-fuel ethanol apply 1.29% PIS and 5.91% Cofins (coefficient 0.7552) from 1 January 2026; PIS/Cofins are replaced by CBS from 2027.
Decreto nº 12.525, de 24 de junho de 2025, sets the PIS/Pasep and Cofins reduction coefficient for non-fuel ethanol (etanol sem fins carburantes) under art. 5º, §8º of Lei nº 9.718/1998. For 2025: coefficient is zero for companies not opted into the special regime (standard rates apply: 5.25% PIS + 24.15% Cofins); 0.7552 for opted-in companies (effective rates: approximately 1.29% PIS + 5.91% Cofins). From 1 January 2026: coefficient is fixed at 0.7552 for all companies regardless of option status (Art. 2, Parágrafo único). Effective from date of publication (Art. 5).
What changed in detail
Decreto nº 12.525, de 24 de junho de 2025, published in the Diário Oficial da União on 25 June 2025, sets the reduction coefficient for PIS/Pasep and Cofins on sales of non-fuel ethanol (etanol sem fins carburantes) under art. 5, §8 of Lei nº 9.718/1998.
For 2025 the coefficient depended on whether the company had opted into the special calculation and payment regime of art. 5, §4 (Art. 2):
| Company | Coefficient | PIS/Pasep | Cofins |
|---|---|---|---|
| Not opted in for 2025 | zero | 5.25% | 24.15% |
| Opted in for 2025 | 0.7552 | 1.29% | 5.91% |
From 1 January 2026 the coefficient is 0.7552 for every company, whether or not it opted into the special regime (Art. 2, sole paragraph). The resulting rates are 1.29% PIS/Pasep and 5.91% Cofins (Art. 3, II).
Art. 4 revokes Decretos 6.573/2008 and 8.164/2013 and art. 2 of Decretos 9.101/2017 and 9.112/2017. The decree entered into force on publication (Art. 5).
What it means
Since 1 January 2026 all sellers of non-fuel ethanol have one set of rates, 1.29% and 5.91%, and the option for the special regime no longer changes the outcome. In 2025, a seller outside the regime paid the full 5.25% and 24.15%, which made the option worth taking.
Lei Complementar 224/2025 cut many PIS/Cofins benefits by 10% from 1 April 2026. Its explicit list of regimes does not name this coefficient, so check the Receita Federal’s guidance under that law before assuming the reduced rates are untouched. The position lasts only until 31 December 2026: from 2027 PIS and Cofins give way to the CBS under Lei Complementar 214/2025. The temporary 2026 cuts on diesel, biodiesel and aviation kerosene are a separate measure, covered in the fuel PIS/Cofins decrees.
Proof
Parágrafo único. A partir de 1º de janeiro de 2026, o coeficiente de redução das alíquotas da Contribuição para o PIS/Pasep e da Cofins de que trata o caput fica fixado em 0,7552 (sete mil, quinhentos e cinquenta e dois décimos de milésimo)Sole paragraph. From 1 January 2026, the PIS/Pasep and Cofins rate-reduction coefficient referred to in the caput is fixed at 0.7552 (seven thousand five hundred and fifty-two ten-thousandths)
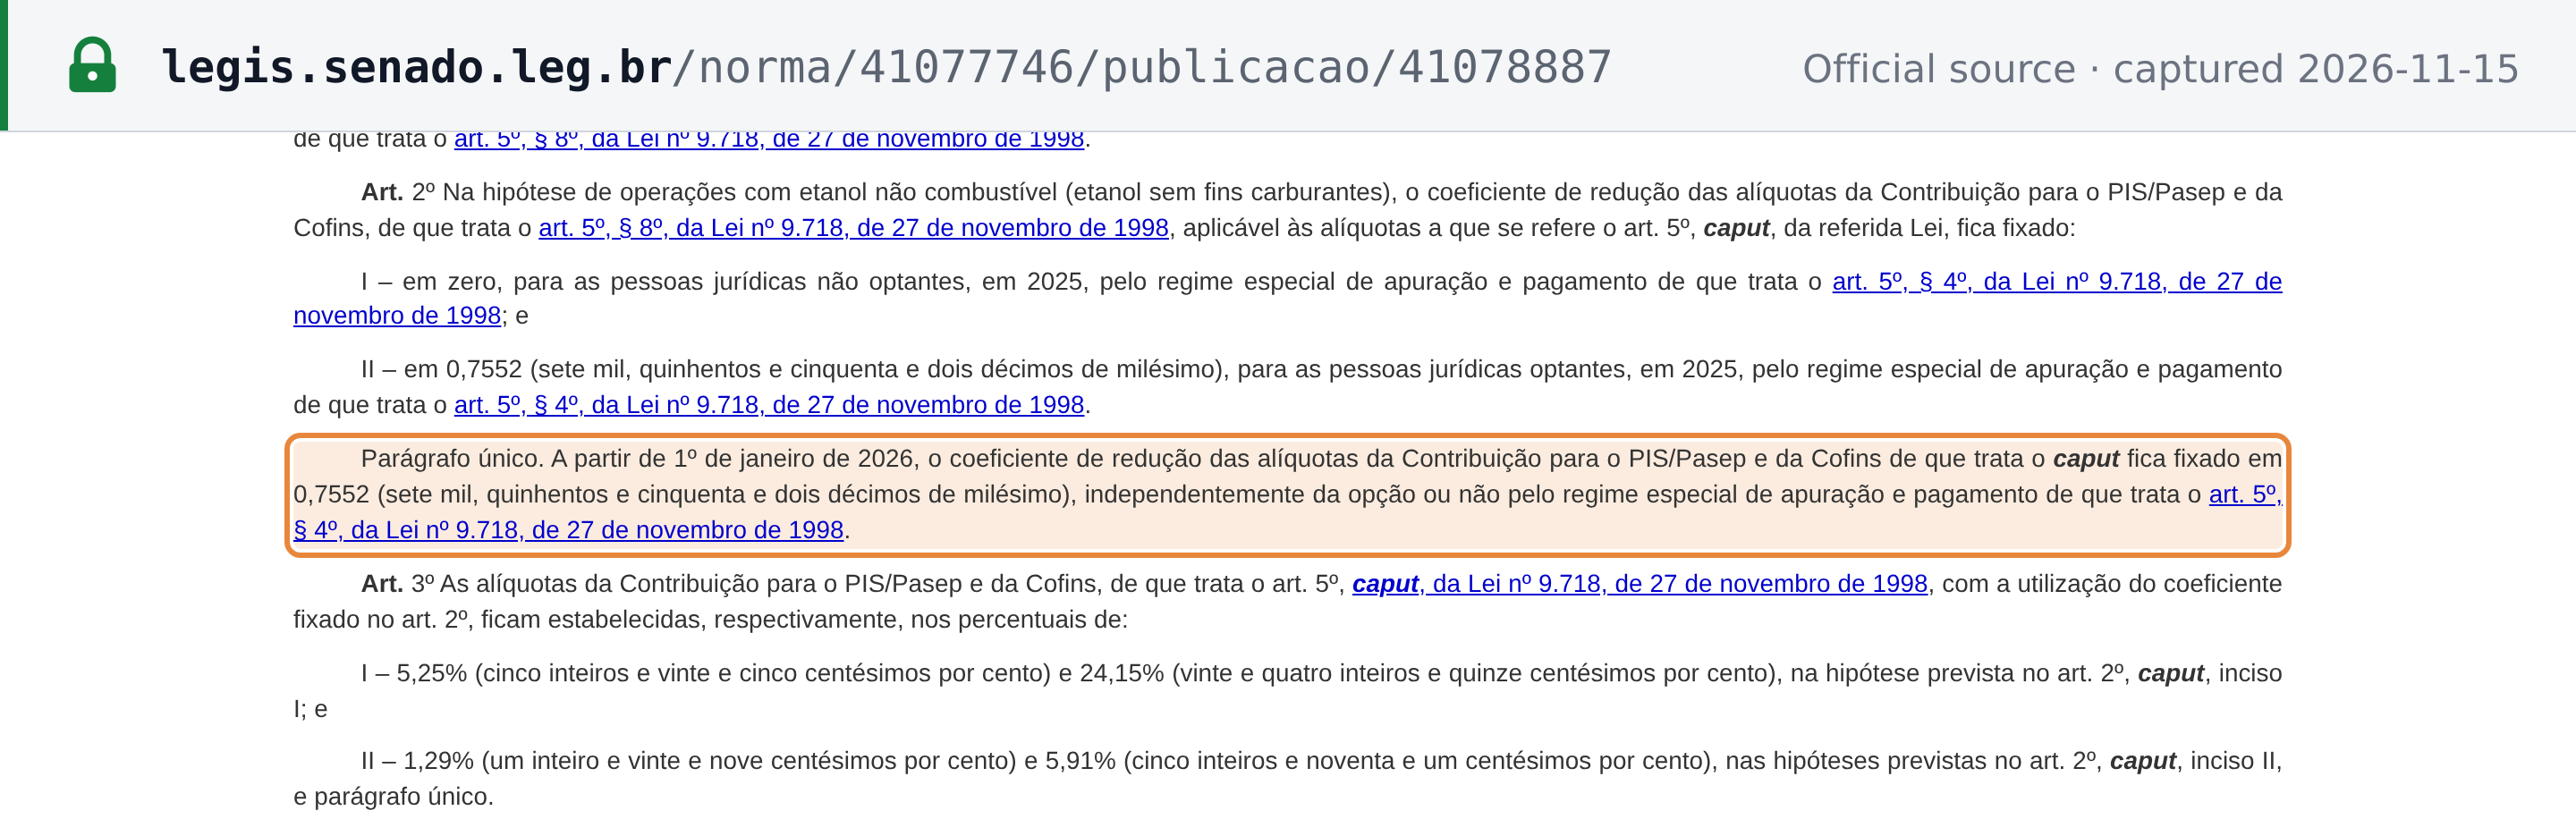 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Decreto nº 12.525, de 24 de junho de 2025 — Diário Oficial da União de 25/06/2025 (p. 8, col. 2), text as published on Senado Federal Legislação · legis.senado.leg.br