Brazil sets REIQ chemical-industry PIS/Cofins rates of 0.62% and 2.83% for March–December 2026
This page records one dated change. For the rules in Brazil as they stand today, see the Brazil guide →
- Jurisdiction
- Brazil
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- Plan ahead
- Announced
- 20 March 2026
- Effective
- 20 March 2026
- Authority
- Imprensa Nacional — Diário Oficial da União
- Verified
- Fetched from official source · high confidence
Petrochemical centres and chemical industries buying or importing the basic petrochemical inputs covered by the REIQ (Lei 11.196/2005 art. 56; Lei 10.865/2004 art. 8 §15).
REIQ chemical and petrochemical companies apply 0.62% PIS and 2.83% Cofins to taxable events from March to December 2026. Watch for an Executive notice that the 2026 cost cap has been reached, which ends the benefit from the following month. The rates set by LC 228 stop after December 2026.
Lei Complementar nº 228, de 19 de março de 2026 (DOU 20 March 2026), sets the PIS/Pasep and Cofins rates for chemical and petrochemical companies under the REIQ (Lei 11.196/2005 art. 56) and the matching PIS/Pasep-Importação and Cofins-Importação rates (Lei 10.865/2004 art. 8 §15). The rates are 1.52% and 7% for taxable events from January 2025 to February 2026, and 0.62% and 2.83% from March to December 2026. Art. 3 caps the 2026 cost of the REIQ benefits at R$2 billion (arts. 56, 57 and 57-A and §§15 and 23) and R$1.1 billion (art. 57-D). The benefits end in the month after the Executive shows that a cap has been reached. The law took effect on publication (Art. 5).
What changed in detail
Lei Complementar nº 228, de 19 de março de 2026, published in the Diário Oficial da União on 20 March 2026 (p. 4), sets the PIS/Pasep and Cofins rates of the Regime Especial da Indústria Química (REIQ).
Art. 1 adds two tiers to Lei 11.196/2005 art. 56, and Art. 2 adds the same tiers for PIS/Pasep-Importação and Cofins-Importação in Lei 10.865/2004 art. 8 §15:
| Taxable events | PIS/Pasep | Cofins |
|---|---|---|
| January 2025 – February 2026 | 1.52% | 7% |
| March 2026 – December 2026 | 0.62% | 2.83% |
Art. 1 also inserts art. 57-C §5 into Lei 11.196: a company that first obtains REIQ habilitation after the provision took effect is tested against 1 December 2025.
Art. 3 caps the 2026 cost of the REIQ benefits at R$2 billion (arts. 56, 57 and 57-A of Lei 11.196 and §§15 and 23 of Lei 10.865 art. 8) and R$1.1 billion (art. 57-D). The benefits end from the month after the Executive shows that a cap has been reached. Art. 4 disapplies art. 14-A of the Lei de Responsabilidade Fiscal and arts. 29, I and 149 of the 2026 budget guidelines law (Lei 15.321/2025). The law took effect on publication (Art. 5).
What it means
The March–December 2026 tier is in force as of November 2026, subject to the Art. 3 caps: if the Executive shows a cap was reached, the benefit ends the following month, so check for that notice before applying the rate. Read it together with LC 224/2025, whose Art. 4 §2, II, b lists the REIQ among the regimes its 10% benefit cut reaches; LC 228 came later and fixes the REIQ rates by statute. The tiers stop at December 2026, and so do PIS and Cofins: LC 214/2025 replaces them with the CBS from 2027 under EC 132, so the chemical sector’s treatment after that depends on the CBS rules, not on this law.
Proof
X – 0,62% (sessenta e dois centésimos por cento) e 2,83% (dois inteiros e oitenta e três centésimos por cento), para os fatos geradores ocorridos nos meses de março de 2026 a dezembro de 2026.X – 0.62% (sixty-two hundredths of one percent) and 2.83% (two point eighty-three percent), for taxable events occurring in the months of March 2026 to December 2026.
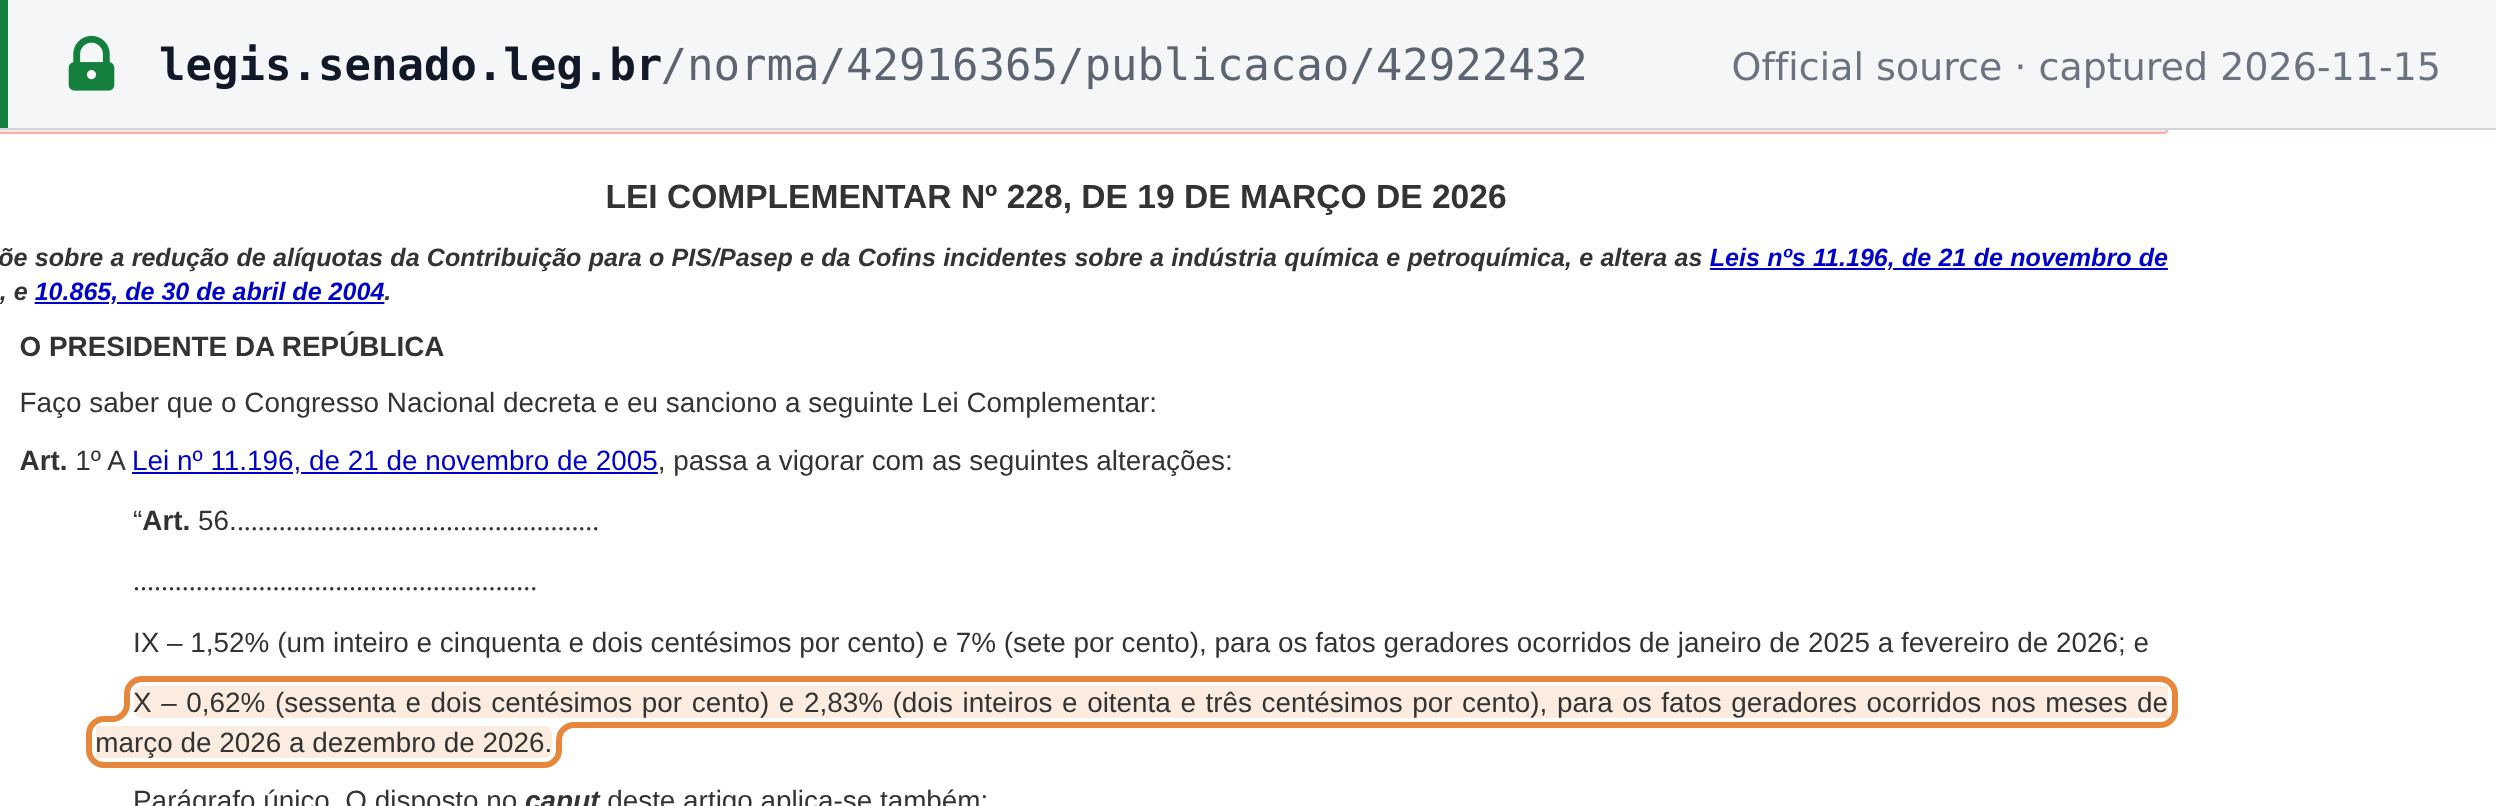 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Lei Complementar nº 228, de 19 de março de 2026 — Senado Federal, Legislação (publicação) · legis.senado.leg.br