Brazil restores the Perse zero rate for events and tourism companies, capped at R$15 billion
This page records one dated change. For the rules in Brazil as they stand today, see the Brazil guide →
- Jurisdiction
- Brazil
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 23 May 2024
- Effective
- 23 May 2024
- Authority
- Imprensa Nacional — Diário Oficial da União
- Verified
- Fetched from official source · high confidence
Events and tourism companies whose main or preponderant CNAE on 18 March 2022 was one listed in Lei 14.148/2021 art. 4, and which completed habilitation.
No action — the Perse zero rate ended from April 2025, after Receita Federal reported on 25 June 2025 that the R$15 billion cap (Lei 14.148 art. 4-A) had been exceeded; taxable events from April 2025 bear PIS/Pasep and Cofins at the normal rates. For earlier periods, check the CNAE test and habilitation.
Lei nº 14.859, de 22 de maio de 2024 (DOU 23 May 2024), restores and narrows the Perse events-sector programme. It rewrites Lei 14.148/2021 art. 4 so that the listed taxes, which include PIS/Pasep and Cofins, are reduced to 0% for 60 months for companies whose main or preponderant CNAE on 18 March 2022 was a listed events or tourism activity (§7). For lucro real or lucro arbitrado companies, the zero rate in 2025 and 2026 is restricted to incisos I and II of the caput (§12). The benefit is subject to prior habilitation (art. 4-B) and to a R$15 billion cost cap for April 2024 to December 2026, after which it ends (art. 4-A). The law revoked the MP 1.202/2023 provision that had ended Perse (Art. 5) and took effect on publication. Receita Federal reported on 25 June 2025 that the R$15 billion cap had been exceeded, which confirms that the benefit ended from April 2025.
What changed in detail
Lei nº 14.859, de 22 de maio de 2024, was published in the Diário Oficial da União on 23 May 2024 and took effect on publication (Art. 6). It rewrites the Programa Emergencial de Retomada do Setor de Eventos (Perse) in Lei 14.148/2021.
- Zero rate (art. 4): the listed taxes, which include PIS/Pasep and Cofins, are reduced to 0% for 60 months for companies in the events and tourism activities listed by CNAE code.
- Eligibility (art. 4 §7): only companies whose main or preponderant CNAE on 18 March 2022 was one of the listed activities.
- Lucro real and lucro arbitrado (art. 4 §12): in 2025 and 2026 the zero rate is restricted to incisos I and II of the caput.
- Habilitation (art. 4-B): the benefit depends on prior habilitation through a Receita Federal electronic platform.
- Cost cap (art. 4-A): the benefit’s cost for April 2024 to December 2026 is capped at R$15 billion, tracked in bimonthly Receita Federal reports. The benefit ends from the month after the Executive shows, in a public hearing of Congress, that the cap has been reached.
Art. 5 revokes art. 6, I of Medida Provisória 1.202/2023, the provision that had ended Perse.
What it means
Perse is spent. Receita Federal reported on 25 June 2025 that the benefit’s cost for April 2024 to March 2025 had passed R$15 billion, confirming that the benefit ended from April 2025, well before the 60 months ran out. Taxable events from April 2025 bear PIS/Cofins at the company’s normal rates. The cap, not the 60-month term, was what decided how long the zero rate lasted. Any remaining exposure is on the period before April 2025: whether a company met the §7 CNAE test and was habilitated. From 2027 PIS and Cofins themselves give way to the CBS under LC 214/2025.
Proof
Ficam reduzidas a 0% (zero por cento) pelo prazo de 60 (sessenta) mesesAre reduced to 0% (zero percent) for a period of 60 (sixty) months
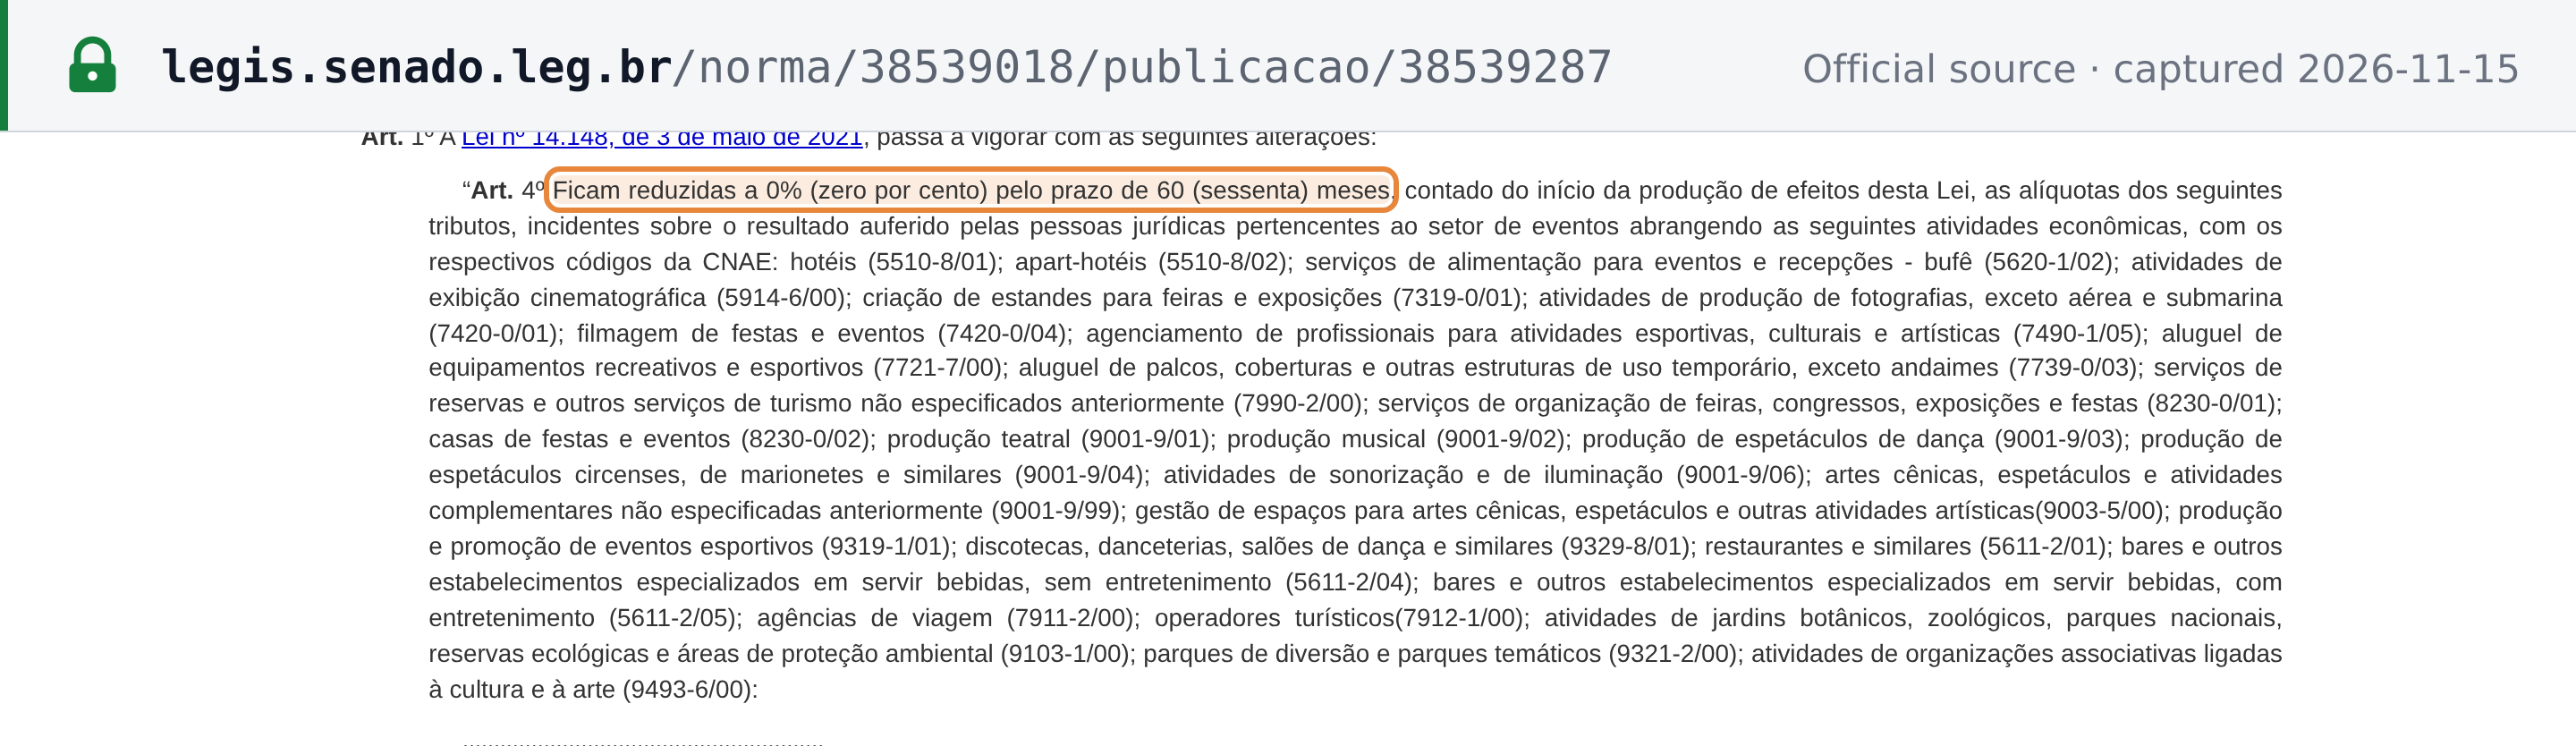 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Lei nº 14.859, de 22 de maio de 2024 — Senado Federal, Legislação (publicação) · legis.senado.leg.br