Canada exempts psychotherapy and counselling therapy services from GST/HST from 20 June 2024
This page records one dated change. For the rules in Canada as they stand today, see the Canada guide →
- Jurisdiction
- Canada
- Tax
- GST/HST
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 20 June 2024
- Effective
- 20 June 2024
- Instrument
- CA-ACT-OF-PARLIAMENT-S-C-2024-c-15
- Authority
- Department of Justice Canada (Justice Laws Website)
- Verified
- Fetched from official source · high confidence
Psychotherapists and counselling therapists who meet the Schedule V practitioner test, and clinics supplying their services to individuals.
No action required — psychotherapists and counselling therapists registered as such under applicable provincial legislation no longer charge GST/HST on professional services provided to individuals. Confirm provincial registration status.
The Fall Economic Statement Implementation Act, 2023 (S.C. 2024, c. 15), assented to June 20, 2024, s. 137, expands the GST/HST exemption for health care practitioner services by adding psychotherapy and counselling therapy to the definition of 'practitioner' and adding psychotherapy services and counselling therapy services to section 7 of Part II of Schedule V to the Excise Tax Act (new paragraphs (j.1) and (j.2)), in force on royal assent.
What changed in detail
The Fall Economic Statement Implementation Act, 2023 (S.C. 2024, c. 15) received Royal Assent on 20 June 2024. Section 137 makes two amendments to Part II of Schedule V to the Excise Tax Act, which lists exempt health care services.
- Subsection 137(1) rewrites the opening of the definition of practitioner in section 1 to add psychotherapy and counselling therapy to the list of services and professions it covers.
- Subsection 137(2) adds two paragraphs to section 7: (j.1) psychotherapy services and (j.2) counselling therapy services.
A supply of these services rendered by a practitioner to an individual is therefore exempt from GST/HST. The practitioner definition keeps its existing conditions, so the person must meet the qualification or licensing test that applies to the profession in the province where the service is supplied.
Section 137 has no deemed coming-into-force date. It took effect on Royal Assent, 20 June 2024. Section 144 of the same Act coordinates it with Bill C-323, a private member’s bill on mental health services, and provides that the other bill is deemed never to have produced its effects once this Act receives assent.
What it means
The exemption is still in force. The list it amended was rewritten again by S.C. 2026, c. 3, which kept psychotherapy and counselling therapy but removed osteopathy.
Exempt status cuts both ways. Therapists no longer charge GST/HST to clients, but they also cannot claim input tax credits on rent, equipment and software used for those services. A practice whose only supplies are exempt counselling services may no longer need to be registered and should review its registration.
Federal Budget 2026 proposes a similar exemption for massage therapy; that is not yet law.
Proof
Section 7 of Part II of Schedule V to the Act is amended by adding the following after paragraph (j): (j.1) psychotherapy services; (j.2) counselling therapy services;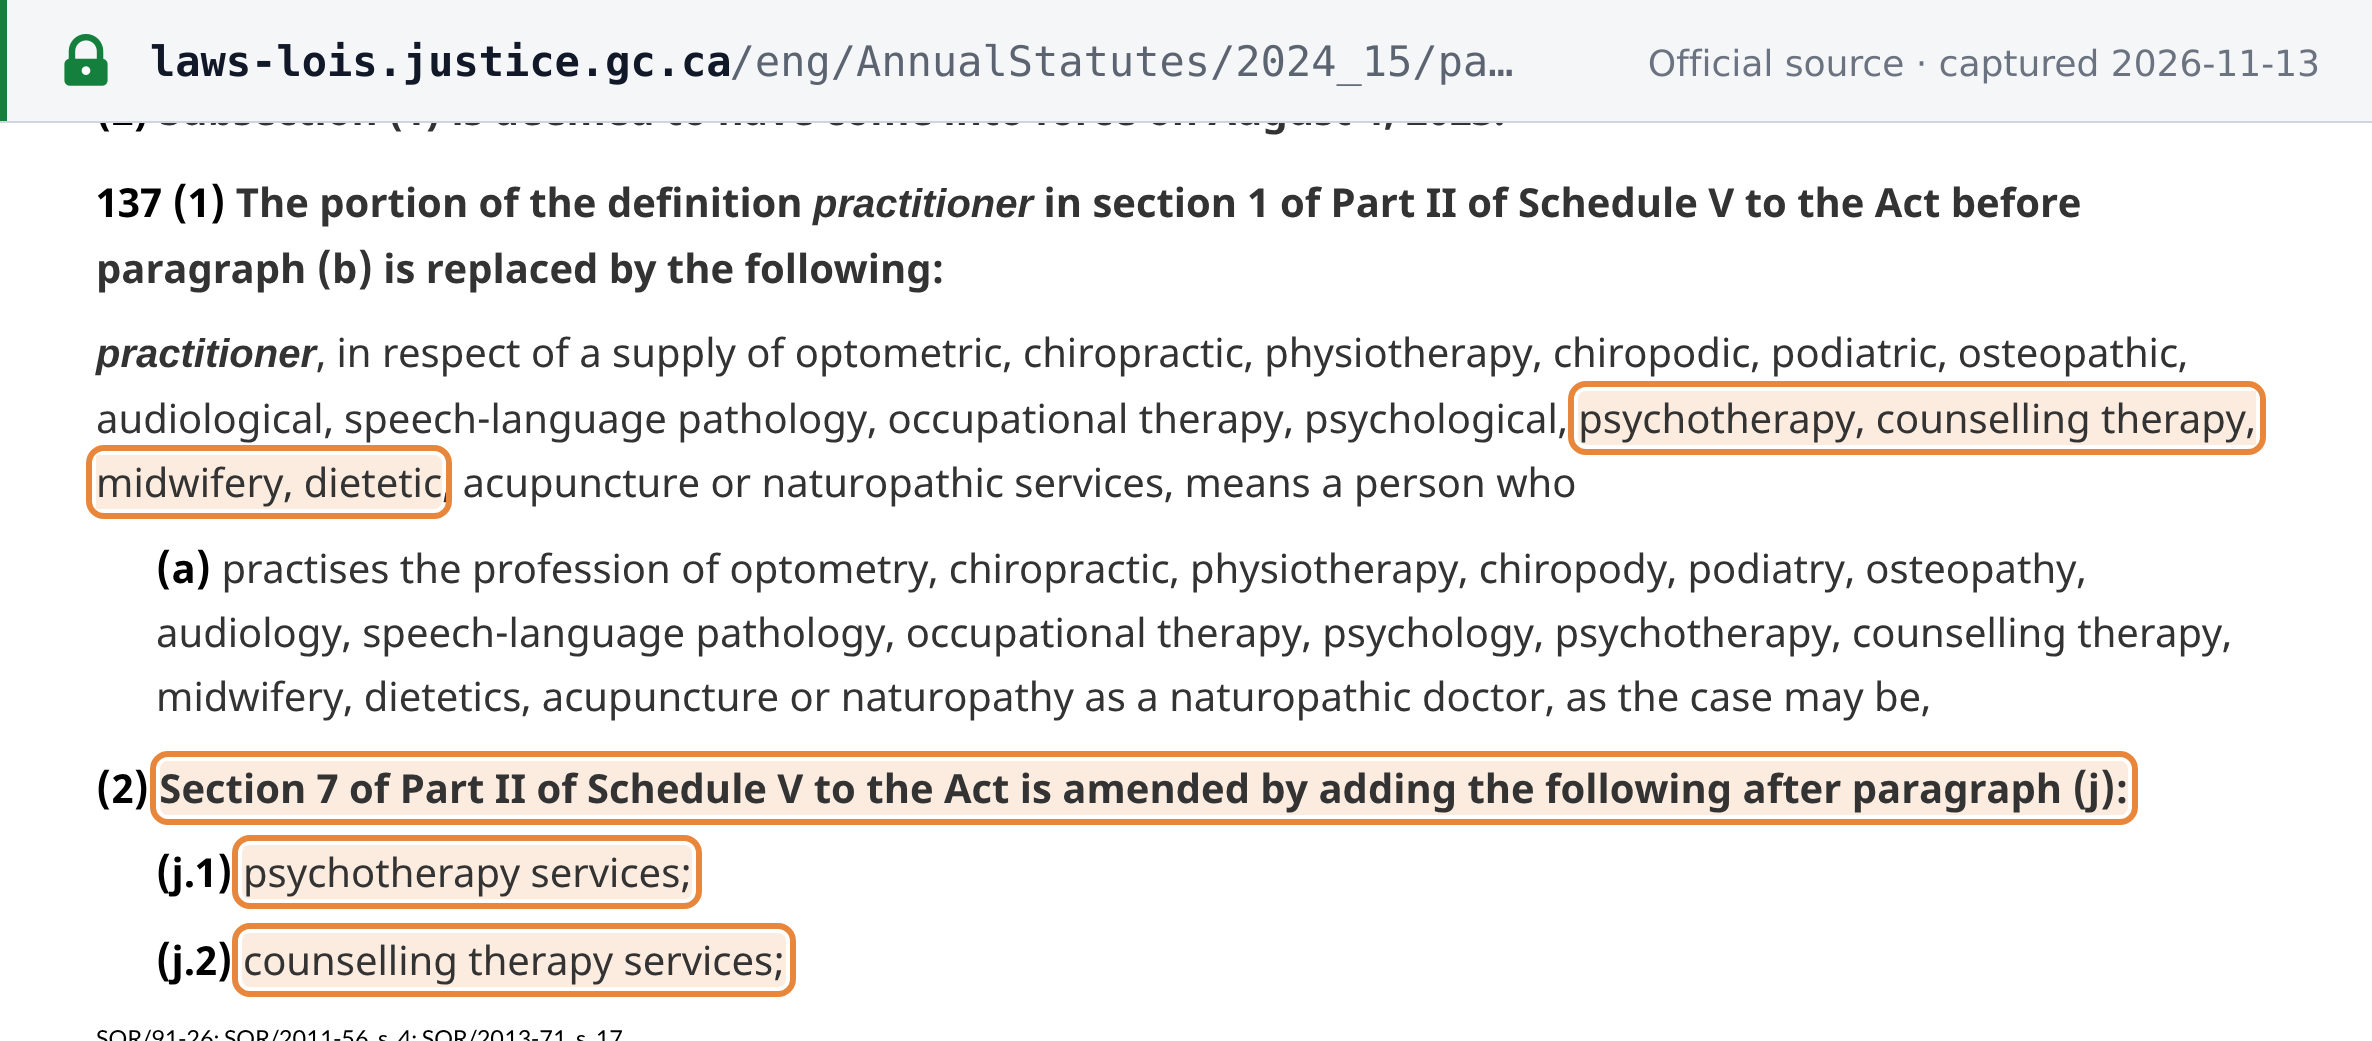 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Fall Economic Statement Implementation Act, 2023, S.C. 2024, c. 15 (annual statute, Justice Laws Website PDF) · laws-lois.justice.gc.ca