Chile extends 19% VAT to all remote services supplied by non-resident providers
- Jurisdiction
- Chile
- Tax
- VAT
- Change type
- Digital services
- Status
- In force
- Impact
- FYI
- Announced
- 24 October 2024
- Effective
- 1 November 2024
- Instrument
- CL-ACT-21713
- Authority
- Servicio de Impuestos Internos (SII), Chile
- Verified
- Fetched from official source · high confidence
Providers with no domicile or residence in Chile supplying any remotely provided service to Chilean customers who are not IVA contributors.
No action — monitoring only.
Ley 21.713 (Diario Oficial 24 October 2024, Ley de Cumplimiento de Obligaciones Tributarias) extended 19% IVA to all services provided remotely by non-domiciled, non-resident providers to non-VAT-contributor customers in Chile, removing the earlier limitation to the four categories in DL 825 article 8 letter n). Non-residents fall under the simplified regime (Párrafo 7° bis). Under the law's general commencement rule the change applies from 1 November 2024.
What changed in detail
Ley N° 21.713 (Ley de Cumplimiento de Obligaciones Tributarias) was published in the Diario Oficial on 24 October 2024 (Núm. 43.982-B). Its article 3 amends the Ley sobre Impuesto a las Ventas y Servicios (Decreto Ley N° 825).
Since Ley 21.210 of 2020, IVA at 19% had applied to services supplied remotely by non-residents only in the four categories listed in article 8 letter n) of DL 825: intermediation, digital entertainment content, software, storage and computing infrastructure, and advertising. Ley 21.713:
- removes that limitation from article 5 of DL 825, so the rule covers any service provided remotely by a person with no domicile or residence in Chile and used in Chile;
- rewrites article 35 A so that all non-resident providers of such services, and of remote sales, to non-IVA contributors fall within the simplified regime of Párrafo 7° bis;
- widens article 35 I to refer to the whole of the IVA law.
The law’s transitional article on IVA gives these changes no special date, so they take effect under its general commencement rule on the first day of the month after publication, 1 November 2024. The SII’s guidance on digital IVA states that the law extended the 19% tax to all services provided remotely by non-residents.
What it means
The extension is in force and has not been reversed. The practical change for foreign providers was that the category test fell away: a consultancy, education platform or other remote service sold to Chilean consumers became taxable even if it did not fit any of the four 2020 categories.
The SII put the administrative side in place in the following weeks: Resolución Ex. SII N° 105 (registration, from 1 November 2024) and Resolución Ex. SII N° 107 (filing and payment on form F129, from 1 December 2024). The same law’s goods and platform provisions followed a year later, in October 2025.
Proof
la Ley 21.713, publicada en el Diario Oficial el 24 de octubre de 2024, amplió la aplicación del Impuesto al Valor Agregado (IVA), con una tasa del 19%, a todos los servicios prestados en forma remota por contribuyentes sin domicilio ni residencia en Chile.Law No. 21.713, published in the Official Gazette on October 24, 2024, extended the application of the Value Added Tax (VAT), with a rate of 19%, to all taxed services remotely provided by taxpayers without domicile or residence in Chile.
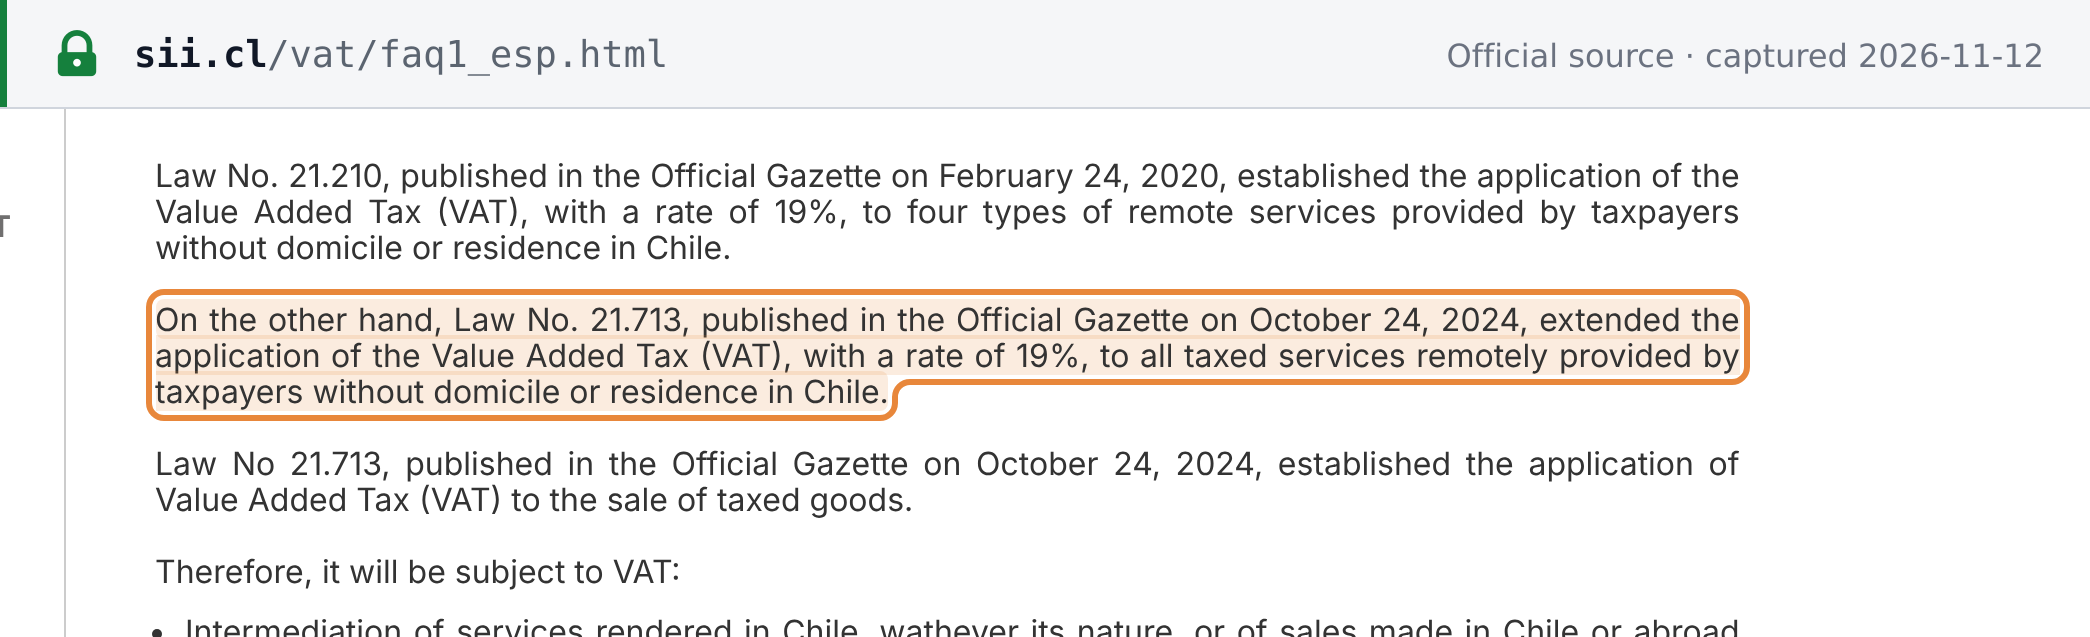 Source snapshot of the official page. Open full size ↗