Chile’s SII sets a new VAT registration procedure for non-resident service providers
- Jurisdiction
- Chile
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- FYI
- Announced
- 30 October 2024
- Effective
- 1 November 2024
- Instrument
- CL-RESOLUTION-105-2024
- Authority
- Servicio de Impuestos Internos (SII), Chile
- Verified
- Fetched from official source · high confidence
Providers with no domicile or residence in Chile supplying IVA-taxable services used in Chile to customers who are not IVA contributors.
No action — monitoring only.
Resolución Ex. SII N° 105 (30 October 2024) set a new registration procedure for non-domiciled, non-resident providers of IVA-taxable services in Chile's simplified regime (Párrafo 7° bis, DL 825), reflecting Ley 21.713's wider scope. It replaced Resoluciones 55/2020 and 21/2022 and applies from 1 November 2024; providers not yet registered must register from that date.
What changed in detail
Resolución Exenta SII N° 105, dated 30 October 2024, sets the procedure by which non-domiciled, non-resident providers of IVA-taxable services register in Chile’s simplified tax regime under Párrafo 7° bis of the IVA law (DL 825). It reflects the wider scope given to that regime by Ley 21.713, which extended IVA to all services supplied remotely by non-residents.
Registration is made through the SII’s digital IVA portal. On the registration form the provider:
- states the type of service it supplies, which may now be any IVA-taxable service used in Chile;
- chooses a monthly or quarterly tax period and a currency for filing and payment (US dollars, euros or Chilean pesos), which can be changed only by a request sent between 21 and 31 January of each year;
- names three contact persons, whose email addresses the SII validates.
The resolution also sets rules for leaving the regime, for the SII to exclude a provider (for example after 36 consecutive months with no F129 return and no payments from Chile), and for the SII to delete duplicate or invalid registrations.
It replaces Resoluciones Ex. SII N° 55 de 2020 and N° 21 de 2022. Resolutive point 9° applies it from 1 November 2024, and providers not yet registered must register from that date.
What it means
The resolution is still the registration rule for non-resident service providers. It was not replaced when the goods regime arrived: the SII issued a separate Resolución Ex. SII N° 84 de 2025 for remote sellers of low-value goods and platform operators, and its Resolución N° 93 of 2025 still refers service intermediation platforms back to this resolution.
For a provider outside the four 2020 categories, 1 November 2024 was the date registration became due, alongside the extension of IVA by Ley 21.713.
Proof
9° La presente resolución regirá a partir del 1° de noviembre de 2024. Luego, los contribuyentes indicados en el resolutivo 1° que no estén actualmente inscritos, a partir de la misma fecha deberán inscribirse en el régimen de tributación simplificada de que trata la presente resolución.9° This resolution shall apply from 1 November 2024. Accordingly, the taxpayers referred to in resolutive point 1° who are not currently registered must, from the same date, register in the simplified tax regime covered by this resolution.
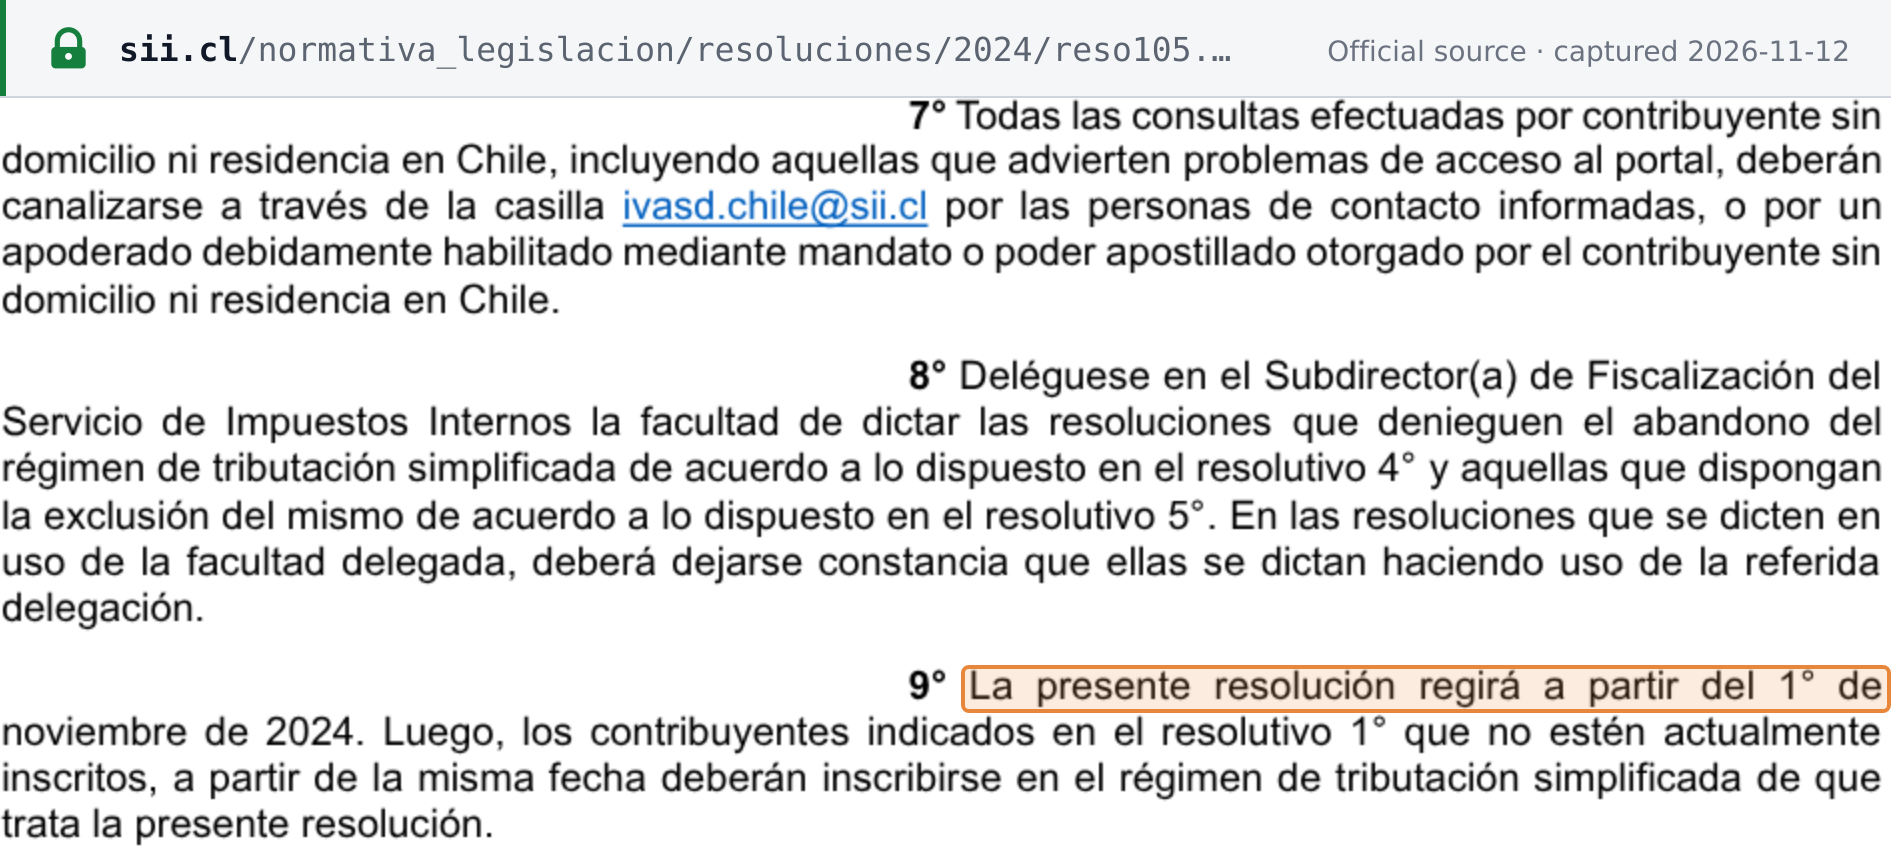 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Resolución Ex. SII N° 105, Santiago, 30 de octubre de 2024 · www.sii.cl