EU sets the ViDA implementing rules for platform deemed suppliers and special schemes, mainly from 1 July 2028
- Jurisdiction
- European Union
- Tax
- VAT
- Change type
- Compliance
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 25 March 2025
- Effective
- 1 July 2028
- Instrument
- EU-IMPLEMENTING-REGULATION-2025-518
- Authority
- Official Journal of the European Union (EUR-Lex)
- Verified
- Fetched from official source · high confidence
Platforms facilitating short-term accommodation rental or road passenger transport, suppliers using them, and users of the OSS and transfer-of-own-goods schemes.
Digital platforms facilitating accommodation rental or passenger transport should prepare for deemed-supplier rules from 1 July 2028.
Council Implementing Regulation (EU) 2025/518 of 11 March 2025 (ViDA implementing rules) amending Implementing Regulation (EU) No 282/2011 sets out information requirements for VAT schemes including: conditions under which a platform is treated as a deemed supplier for short-term accommodation rental and passenger transport (Article 9b–9g); the own-goods transfer OSS scheme rules (Articles 1(13)–1(27)); and record-keeping obligations for deemed suppliers. Articles 1(2)–1(7) apply from entry into force (14 April 2025); main provisions apply from 1 July 2028. Published OJ L, 2025/518, 25 March 2025.
What changed in detail
Council Implementing Regulation (EU) 2025/518 of 11 March 2025 amends Implementing Regulation (EU) No 282/2011 “as regards information requirements for certain VAT schemes”. It was published on 25 March 2025 (OJ L, 2025/518) and entered into force on 14 April 2025. Under Article 2 it applies from 1 July 2028, except Article 1, points (2) to (7), which applied from entry into force.
- Platform deemed supplier (new Articles 9b to 9g). For Article 28a of the VAT Directive, the regulation defines when a platform “facilitates” short-term accommodation rental or road passenger transport, how the provider supplies its VAT number and declaration that it will charge the VAT, when a platform relying on that information is not liable, and how exemptions and the SME scheme carry over to a platform acting as deemed supplier.
- Special schemes (points (13) to (27)). Detailed rules for the One Stop Shop schemes as extended by ViDA, including the new transfer-of-own-goods scheme.
- Points (2) to (7), already applying. These align the implementing rules on the location of customers and on streamed or virtually attended events with the place-of-supply rules for virtual events in Articles 54(1) and 58 of the VAT Directive.
What it means
Most of this regulation is enacted but not yet applying; it gives operational detail to Directive (EU) 2025/516, whose platform rule starts on 1 July 2028 at the earliest. Because each Member State may start that rule as late as 1 January 2030, a platform operating across the EU will apply these definitions on different dates country by country. The exchange of the resulting data between authorities is governed by Regulation (EU) 2025/517. The early points (2) to (7) complement the virtual-events rule that Directive (EU) 2022/542 applied from January 2025.
Proof
It shall apply from 1 July 2028.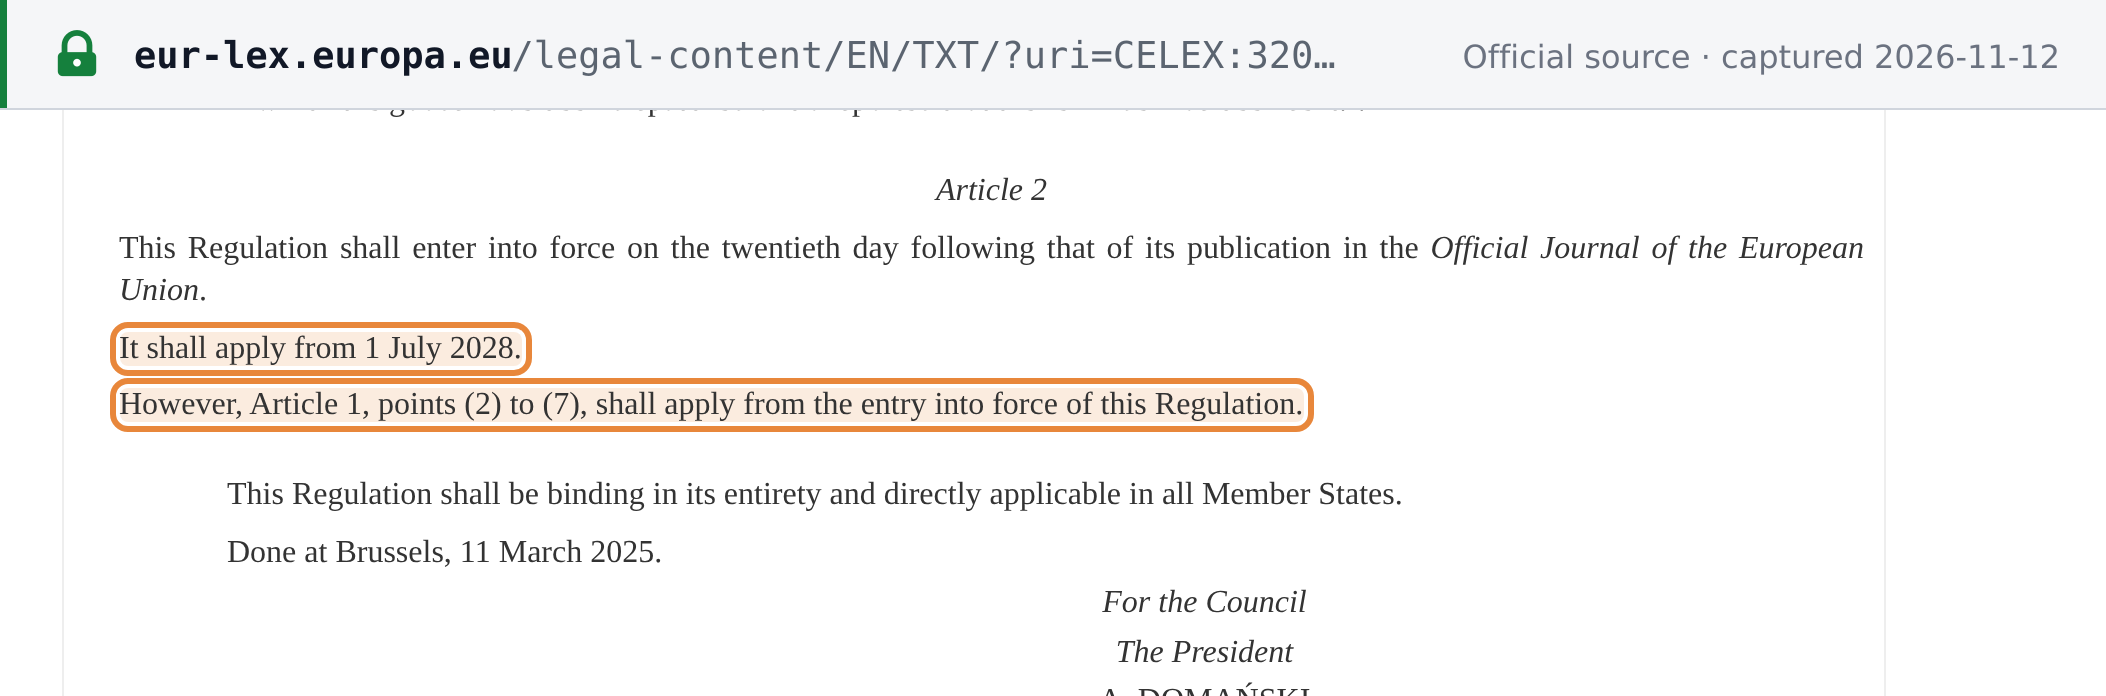 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Council Implementing Regulation (EU) 2025/518 of 11 March 2025 · OJ L, 2025/518, 25.3.2025 · publications.europa.eu