Israel accelerates the allocation-number schedule: NIS 10,000 from 2026, then NIS 5,000 from 1 June 2026
This page records one dated change. For the rules in Israel as they stand today, see the Israel guide →
- Jurisdiction
- Israel
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- FYI
- Announced
- 27 March 2025
- Effective
- 1 January 2026
- Instrument
- IL-PRIMARY-LEGISLATION-SH-3384
- Authority
- הכנסת (Knesset of the State of Israel)
- Verified
- Fetched from official source · high confidence
Israeli VAT-registered businesses issuing or receiving tax invoices above NIS 10,000 before VAT between 1 January and 31 May 2026.
No action required — the NIS 10,000 threshold (from 1 January 2026 under SH 3384) is now superseded by NIS 5,000 from 1 June 2026 (see il-ctc-allocation-number-clearance-2026).
Israel’s 2025 Budget Arrangements Law 5785-2025 (Sefer HaChukkim 3384, enacted 27 March 2025) accelerated the CTC step-down schedule: sections 17–18 set the allocation-number threshold at NIS 10,000 from 1 January 2026 (the original schedule had a different step). NIS 5,000 from 1 June 2026 follows under the same law.
What changed in detail
Israel’s Law to Achieve the Budget Targets and Implement Economic Policy for the 2025 Budget Year (Legislative Amendments), 5785-2025, was published in Sefer HaChukim 3384 on 27 March 2025. Sections 17 and 18 amend section 38 of the Economic Efficiency Law 5783-2023, which carries the allocation-number rules.
Section 17:
- removes the “temporary provision” label from VAT Law amendment no. 63, making the allocation-number model permanent;
- in section 38(b)(2), replaces the period ending 31 December 2026 with one ending 31 May 2026, and replaces NIS 15,000 with NIS 10,000;
- deletes section 38(b)(3), the step that would have set NIS 10,000 for 2027.
The effect is a threshold of NIS 10,000 before VAT from 1 January 2026 to 31 May 2026. With no later override left, the base NIS 5,000 in section 38(a1) of the VAT Law applies from 1 June 2026.
Section 18 applies section 38, as amended, to tax invoices issued from 1 January 2026.
What it means
The NIS 10,000 step is spent: it covered invoices issued from 1 January to 31 May 2026. Since 1 June 2026 the threshold is NIS 5,000, the end point set by this same law and recorded in il-ctc-allocation-number-clearance-2026.
The chain runs NIS 25,000 in 2024, NIS 20,000 in 2025, NIS 10,000 for the first five months of 2026, then NIS 5,000. This law is the reason the schedule ends in mid-2026 rather than in 2028, and it is the change that made the model permanent rather than temporary.
Proof
בפסקה (2), במקום "עד יום כ"א בטבת התשפ"ז (31 בדצמבר 2026)" יבוא "עד יום ט"ו בסיוון התשפ"ו (31 במאי 2026)" ובמקום "15,000" יבוא "10,000";In paragraph (2), instead of 'until 31 December 2026' read 'until 31 May 2026', and instead of '15,000' read '10,000';
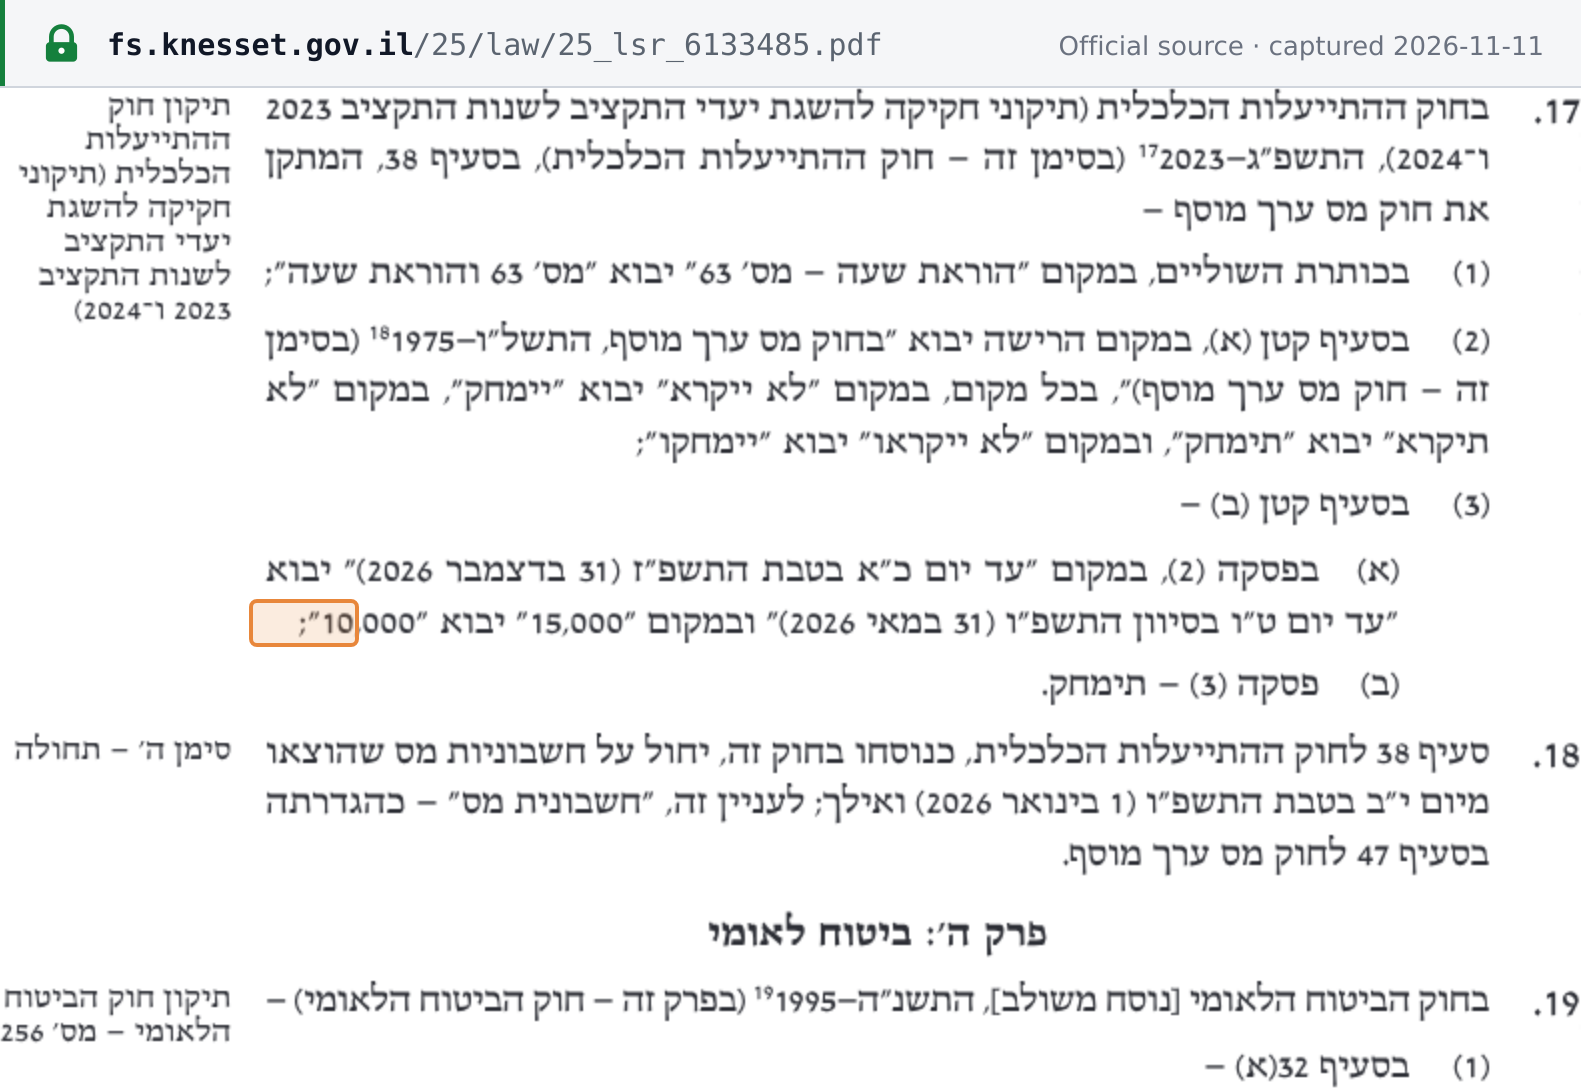 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · ספר החוקים 3384 (27.3.2025) — חוק להשגת יעדי התקציב וליישום המדיניות הכלכלית לשנת התקציב 2025 (תיקוני חקיקה), התשפ״ה-2025, סעיפים 17–18 · fs.knesset.gov.il
Sources
What this replaces
- Israel ends the allocation-number pilot and lowers the threshold to NIS 20,000 for 2025 effective 1 January 2025