Israel starts invoice allocation numbers at a NIS 25,000 threshold for 2024
This page records one dated change. For the rules in Israel as they stand today, see the Israel guide →
- Jurisdiction
- Israel
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- FYI
- Announced
- 1 January 2024
- Effective
- 5 May 2024
- Instrument
- IL-PRIMARY-LEGISLATION-SH-3045
- Authority
- הכנסת (Knesset of the State of Israel)
- Verified
- Fetched from official source · high confidence
Israeli VAT-registered businesses receiving tax invoices above NIS 25,000 before VAT in 2024, whose input-VAT deduction depended on an allocation number, and the businesses issuing those invoices.
No action required — this initial threshold (NIS 25,000) has been superseded by lower thresholds. The current threshold is NIS 5,000 from 1 June 2026 (see il-ctc-allocation-number-clearance-2026).
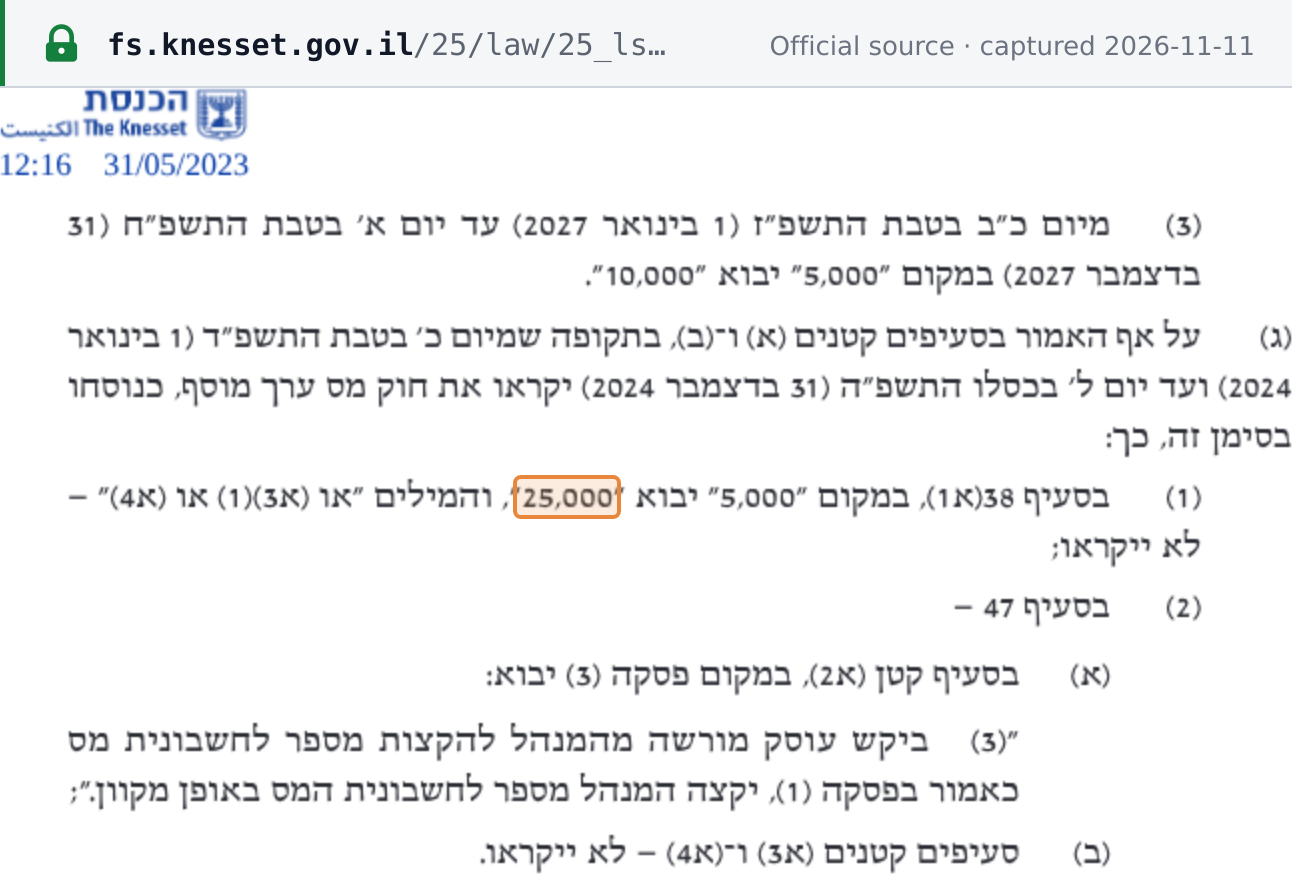
In force from 1 January 2024: Israel's Economic Efficiency Law 5783-2023 (Sefer HaChukim 3045, published 31 May 2023), section 38 (VAT Law amendment no. 63), introduced the CTC allocation-number model. Input VAT on a tax invoice above the threshold (pre-VAT) is not deductible unless the invoice carries an allocation number from the Israel Tax Authority. For 1 January to 31 December 2024 the statute set the threshold at NIS 25,000 (s.38(c)). The ITA deferred mandatory use administratively to 5 May 2024 because of the war.
What changed in detail
Israel’s Economic Efficiency Law (Legislative Amendments to Achieve the Budget Targets for the 2023 and 2024 Budget Years), 5783-2023, was published in Sefer HaChukim 3045 on 31 May 2023. Section 38 (VAT Law amendment no. 63, enacted as a temporary provision) created the allocation-number model: input VAT on a tax invoice above a threshold, measured before VAT, cannot be deducted unless the invoice carries an allocation number issued by the Israel Tax Authority.
The base threshold written into the VAT Law is NIS 5,000. Section 38(c) overrides it for 1 January 2024 to 31 December 2024: section 38(a1) is read with “25,000” in place of “5,000”. The same subsection also disapplies, for that year, the provisions that would let the Director refuse an allocation number. 2024 was therefore a pilot year in which numbers were requested and issued but not refused.
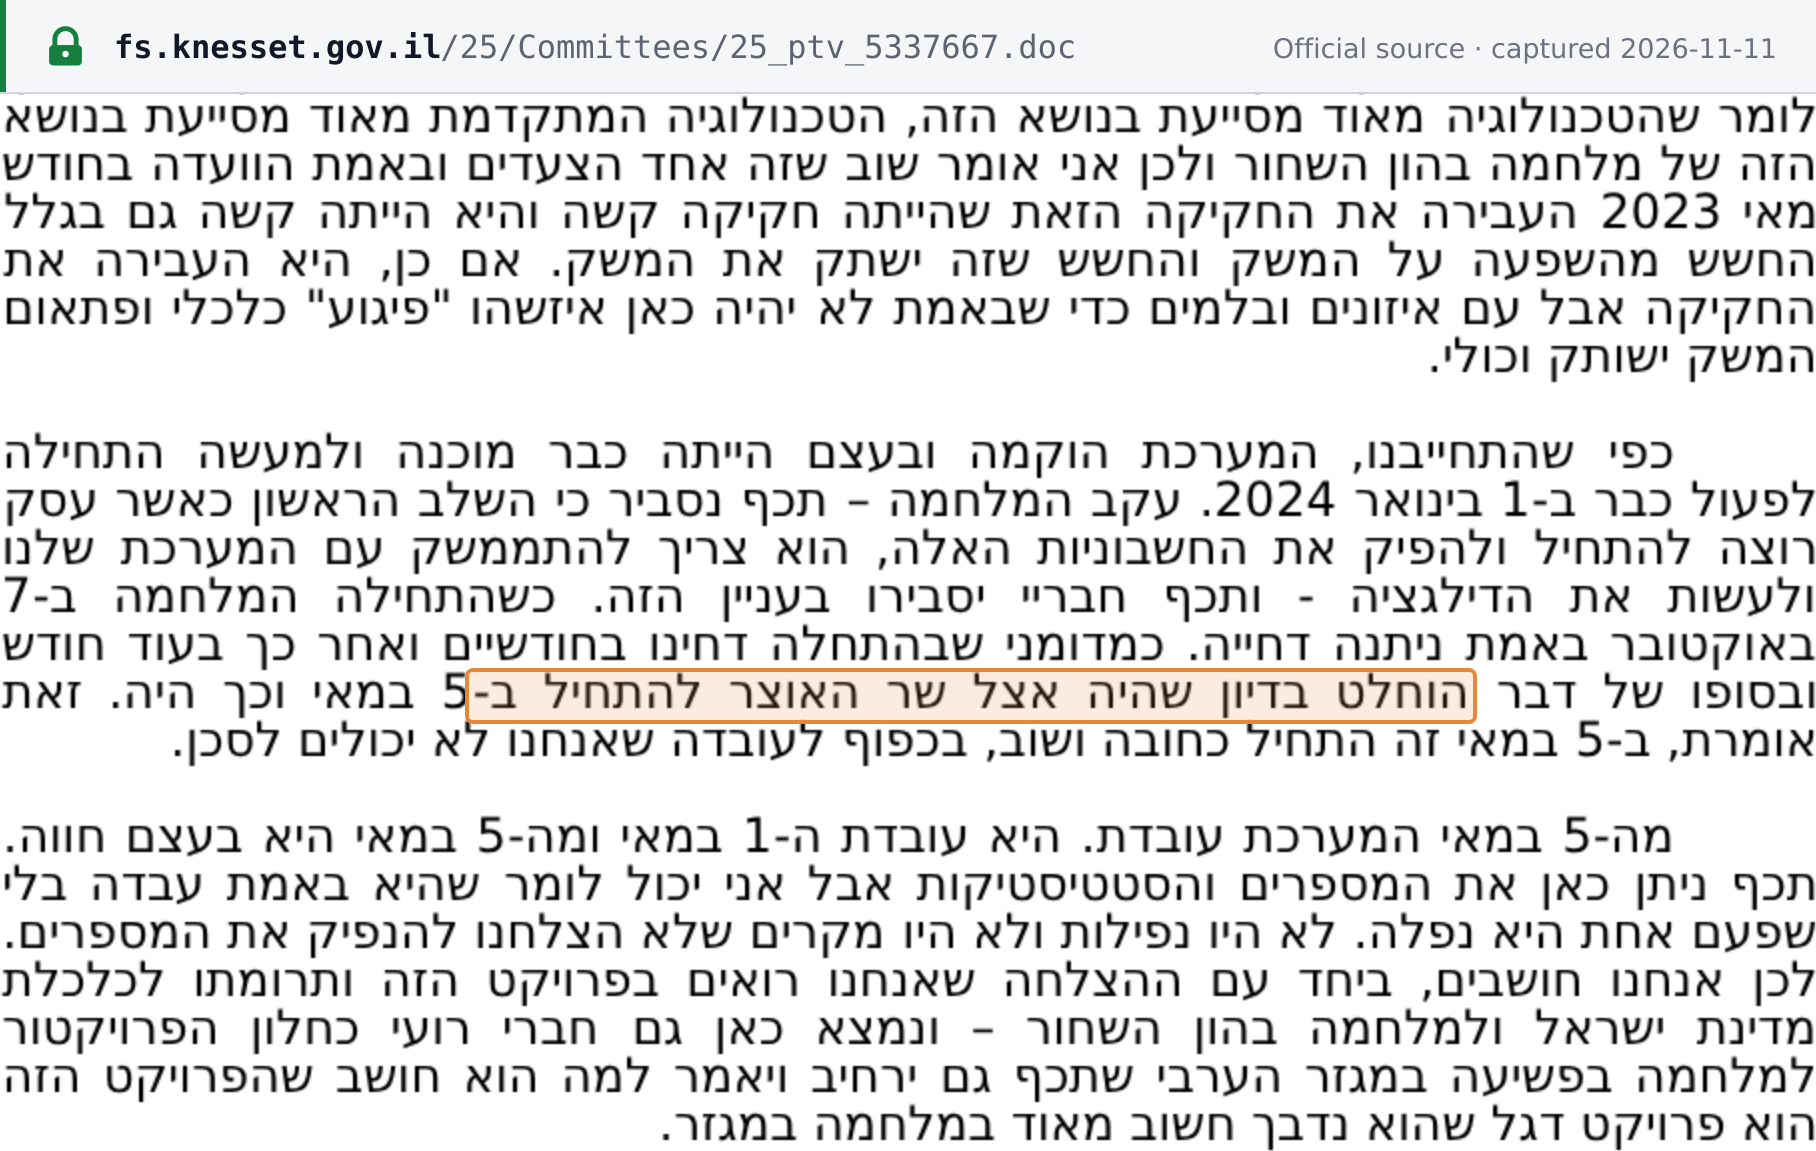
The statute set 1 January 2024 as the start. The Tax Authority’s system went live on that date. Because of the war, mandatory use was deferred administratively to 5 May 2024, by a decision taken at the Minister of Finance. The Tax Authority’s representative described this to the Knesset Finance Committee on 20 November 2024. No statute or order moved the date.
What it means
This threshold is spent. The NIS 25,000 figure applied only to 2024. It was followed by NIS 20,000 for 2025, NIS 10,000 from 1 January 2026 and NIS 5,000 from 1 June 2026, which is the current threshold.
The point most often misread is the start date: the law ran from 1 January 2024, while 5 May 2024 was the date the Tax Authority began enforcing it. For 2024 invoices dated before 5 May, a missing allocation number was not treated as blocking the deduction in practice, but the statutory period itself began on 1 January.
Proof
בתקופה שמיום כ' בטבת התשפ"ד (1 בינואר 2024) ועד יום ל' בכסלו התשפ"ה (31 בדצמבר 2024) יקראו את חוק מס ערך מוסף, כנוסחו בסימן זה, כך: בסעיף 38(א1), במקום "5,000" יבוא "25,000"For the period from 1 January 2024 to 31 December 2024 the VAT Law, as worded in this chapter, shall be read so: in section 38(a1), instead of '5,000' read '25,000'
 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · ספר החוקים 3045, י״א בסיוון התשפ״ג (31.5.2023) — חוק ההתייעלות הכלכלית, התשפ״ג-2023, סעיף 38 · fs.knesset.gov.il
כשהתחילה המלחמה ב-7 באוקטובר באמת ניתנה דחייה. כמדומני שבהתחלה דחינו בחודשיים ואחר כך בעוד חודש ובסופו של דבר הוחלט בדיון שהיה אצל שר האוצר להתחיל ב-5 במאי וכך היה. זאת אומרת, ב-5 במאי זה התחיל כחובהWhen the war began on 7 October a deferral was indeed given. I believe we first deferred by two months and then by another month, and in the end it was decided, at a meeting held with the Minister of Finance, to start on 5 May, and so it was. That is, on 5 May it started as an obligation.
 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Knesset Finance Committee, protocol no. 492, 20 November 2024 · fs.knesset.gov.il